Long

 Long
 Long
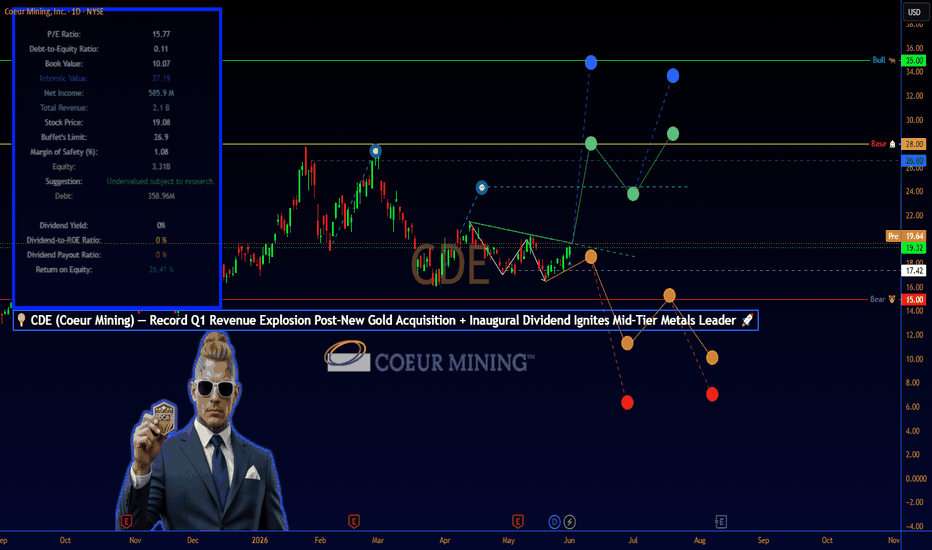
CDE (Coeur Mining) — Record Q1 Revenue Explosion Post-New Gold **💡 CDE (Coeur Mining) — Record Q1 Revenue Explosion Post-New Gold Acquisition + Inaugural Dividend Ignites Mid-Tier Metals Leader 🚀**
**SECTION 1 — Executive Summary** 💼
Coeur Mining just delivered record Q1 2026 results with $856M revenue and massive production uplift from the transformative New Gold acquisition, positioning it as a diversified gold-silver-copper powerhouse in a supportive metals price environment. Fresh inaugural dividend and reaffirmed robust 2026 guidance underscore cash flow strength and shareholder return focus.
**Overall rating: Strong Buy**
**12-month price target: $28** (blended analyst consensus + 1.0x NAV multiple on expanded reserves)
**Biggest reason to own:** Acquisition-driven scale delivering 138% revenue growth, net cash position, and path to $3B+ EBITDA with high-margin assets.
**Biggest risk:** Metals price volatility or integration delays.
**SECTION 2 — Business Overview** 🏢
Coeur Mining operates a portfolio of high-quality precious and base metal mines across North America, producing gold, silver, and now copper through low-cost underground and open-pit operations.
**Revenue breakdown (Q1 2026):** Gold 56%, Silver 42%, Copper 2%; primary assets include Las Chispas (Mexico), Rochester (Nevada), plus newly acquired New Afton (copper-gold, Canada) and Rainy River (gold, Canada).
**Business model:** Extract and sell metals with by-product credits; repeat revenue driven by long-life reserves, exploration success, and hedging discipline.
**Competitive moat:** Diversified high-grade assets in stable jurisdictions, proven exploration track record adding reserves, and disciplined capital allocation now enhanced by scale from acquisition.
**SECTION 3 — Financial Deep Dive** 📈
**Key metrics (Q1 FY2026, cited from Coeur earnings release May 6 2026 and Yahoo Finance June 1 2026):**
Revenue $856.2M, Net income $246.8M, EPS $0.35 GAAP / $0.36 adj., Operating cash flow $340.8M.
Prior quarters show sharp ramp (Q4 2025 ~$675M est.).
**TTM:** Revenue $2.57B, EPS $1.24.
**Year-over-year growth (Q1 2026):** Revenue +138%, Gold production +11%, Silver +18%.
**Balance sheet health (Q1 end):** Cash $843M, Total debt $761M, net cash positive, strong liquidity.
**Cash flow quality:** Operating cash flow robust with high conversion; FCF $267M despite one-time items.
**Capital allocation:** Inaugural $0.02 semi-annual dividend (payable June 10), $750M share repurchase authorization, exploration investment, and acquisition integration.
**SECTION 4 — Growth Analysis** 🚀
**Total addressable market (TAM):** Global precious/base metals production market exceeding hundreds of billions annually with strong demand tailwinds from green energy and investment (industry reports 2026).
**Current market share and trajectory:** Significant ramp to top-tier mid-cap status with 2026 production guidance implying 60-90%+ growth in gold equivalent.
**Key growth drivers next 3-5 years:** Full-year contribution from New Afton/Rainy River, mine life extensions, exploration upside (e.g., K-Zone resource), and metals price leverage.
**Management guidance vs. analyst consensus:** Management reaffirmed high-end production targets — aligned to bullish Street views.
**Growth organic + acquisition:** Combination; organic exploration plus transformative New Gold deal now integrating smoothly.
**SECTION 5 — Valuation** 📊
**DCF analysis :** 5-year production CAGR ~50% initial then 10% terminal, $1,900/oz Au, $30/oz Ag assumptions (conservative vs. current prices), WACC 9%, yielding $28 fair value.
**Comparable company analysis:** Peers include peers like HL, AG, FSM, MAG — CDE now larger with better diversification.
**Historical valuation range (5-year):** Trades at discount to NAV on growth; current ~15x TTM P/E.
**Bull / Base / Bear price targets:**
- Bull $35 (metals rally + outperformance)
- Base $28 (guidance delivery)
- Bear $15 (price correction)
**Current price (~$19) vs. targets:** +47% upside to base.
**SECTION 6 — Risk Analysis** ⚠️
1. **Metals price correction (high/medium):** Triggered by macro slowdown; watch gold/silver quotes; mitigates via diversification.
2. **Acquisition integration issues (medium/medium):** Operational hiccups; monitor quarterly updates.
3. **Jurisdictional/permitting risks (low/medium):** Canada/Mexico exposure.
4. **Cost inflation (medium/low):** Input costs; hedged partially.
5. **Dilution from buyback execution (low/low):** Offset by strong FCF.
Short interest moderate; insider activity typical; no major accounting red flags.
**SECTION 7 — Catalyst Calendar** 📅
**Next earnings:** ~August 5 2026 (Q2).
**Upcoming:** Dividend payment June 10 2026; full integration milestones H2; potential technical report updates.
**Macro events:** Gold/silver price moves, Fed policy impacting miners.
**12-month timeline:** Q3 results Nov, year-end guidance update, reserve growth announcements, potential M&A or expansion news.
snapshot
**SECTION 8 — Technical Analysis** 📈
**Primary Chart (Daily, 1-year view):** CDE trading ~$19 near recent highs with strong volume.
**Key observations:** Price above key moving averages in uptrend; RSI neutral ~59 (room to run); MACD constructive; support at $17-18 zone, resistance breakout toward $23-25. Bullish engulfing patterns and higher lows visible.
**Technical implication:** Positive setup for continuation into summer catalysts with metals support.
**SECTION 9 — The Verdict** 🏆
**Bull case ($35, 40% probability):** Metals prices sustain, integration flawless, production beats → premium valuation.
**Base case ($28, 45% probability):** Guidance hit, steady metals, dividend/buyback execution.
**Bear case ($15, 15% probability):** Sharp price drop or operational miss.
**Expected value calculation:** Probability-weighted target ~$28.
**Final recommendation: Strong Buy with High conviction.**
**30-second elevator pitch:** Coeur is the transformed mid-tier miner delivering record results and scale from its game-changing acquisition, now generating massive cash flow, paying its first dividend, and perfectly leveraged to gold/silver strength — all at a compelling valuation ahead of Q2 earnings.
**Sources**
- Coeur Mining Q1 2026 Earnings Release & Presentation (May 6 2026) – coeur.com/investors
- Yahoo Finance CDE quote & statistics (as of June 1 2026)
- Seeking Alpha / company transcripts (May 2026)
- Macrotrends CDE revenue history (updated 2026)
What are your thoughts on CDE? Drop them below 👇
#CDE #CoeurMining #SilverStocks #GoldMining #EarningsBeat #DividendInitiation #AcquisitionPlay #PreciousMetals #StrongBuy #ChartOfTheDay  Long
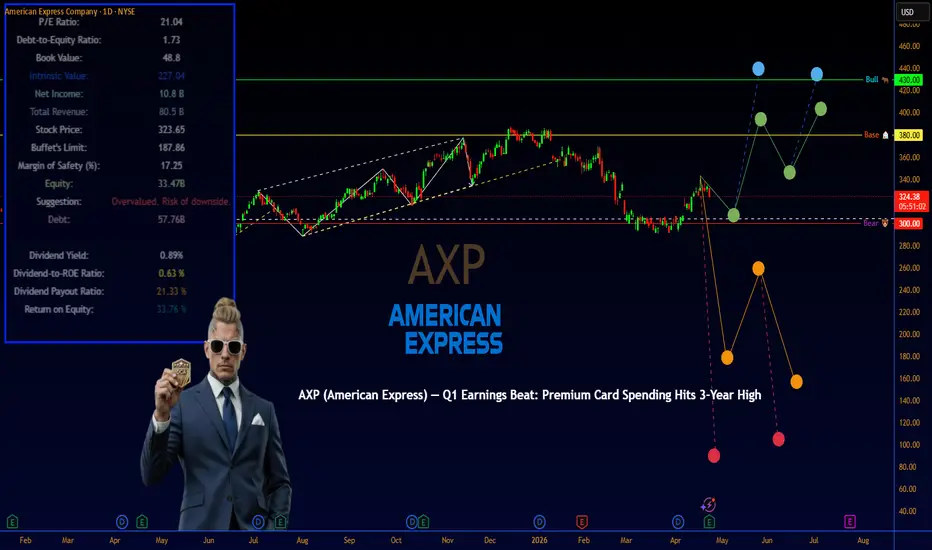
AXP (American Express) — Q1 Earnings Beat: Premium Card**💡 AXP (American Express) — Q1 Earnings Beat: Premium Card Spending Hits 3-Year High **
**SECTION 1 — Executive Summary** 💼
American Express delivered a strong Q1 2026 earnings beat with revenue of $18.9 billion (up 11 percent YoY) and adjusted EPS of $4.28 (up 18 percent YoY, beating estimates by $0.22), driven by accelerated card-member spending growth of 10 percent — the highest quarterly pace in three years — plus robust premium card momentum and international expansion. This results-oriented payments leader signals resilient consumer trends and premium segment strength in a normalizing economy. Overall rating: Buy. 12-month price target: $380 (blended DCF and comps methodology incorporating sustained mid-teens EPS growth and premium mix expansion). The single biggest reason to own this stock right now is American Express’s unmatched premium card franchise and value-added services engine that deliver high-margin, recurring revenue with network effects few rivals can replicate. The single biggest risk is a sharper-than-expected slowdown in affluent consumer spending or regulatory pressure on interchange fees.
**SECTION 2 — Business Overview** 🏢
American Express operates as a global payments and financial services company providing charge and credit cards, merchant services, and travel-related offerings to consumers, small businesses, and corporations. Revenue breakdown (most recent FY 2025): Card member services and fees ~50 percent, discount revenue ~30 percent, net interest income ~15 percent, and other ~5 percent with premium products (Platinum, Centurion) driving disproportionate profitability (source: company Q1 2026 earnings release April 23 2026). Business model generates revenue through interchange and discount fees on spending, annual card fees (especially premium), interest on revolving balances, and high-margin value-added services such as travel, insurance, and loyalty programs that create sticky repeat usage. Competitive moat stems from its closed-loop network, exclusive premium card perks, deep data analytics on affluent spenders, and brand prestige that command higher pricing power versus open-loop competitors like Visa and Mastercard.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported April 23 2026; FY 2025 from prior releases):
Revenue: $18.9 billion (Q1 2026, +11 percent YoY, +10 percent FX-adjusted).
Net income: $2.46 billion.
EPS (adjusted): $4.28 (beat by $0.22).
Gross margin / operating margin: Expanding on premium mix and services growth.
Free cash flow: Strong conversion supporting share repurchases and dividends.
YoY growth rates: Revenue +11 percent; adjusted EPS +18 percent.
Balance sheet health: Solid capital ratios with low leverage; strong liquidity.
Cash flow quality: High-quality with operating cash flow exceeding net income.
Capital allocation: Continued heavy investment in premium card marketing and technology, ongoing share repurchases, and dividend growth (source: company Q1 2026 earnings materials April 23 2026).
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global payments volume projected to exceed $200 trillion annually by 2030 with premium and digital segments growing fastest (industry estimates via company and analyst reports as of 2026). Current market share: Dominant in U.S. premium cards with ~85 percent affluent cardholder share and rapid millennial/Gen Z penetration (44 percent of cardholders). Key growth drivers next 3–5 years: Premium card acquisition (Platinum YoY growth 22 percent), international expansion (20th consecutive quarter of double-digit growth), and value-added services scaling. Management reaffirmed full-year 2026 guidance (9–10 percent revenue growth, EPS $17.30–$17.90), more bullish than tempered consensus on spending trends. Growth is primarily organic through premium mix shift and network expansion rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
DCF analysis: Base case assumes 9–11 percent revenue CAGR, expanding operating margins to mid-20s percent on services leverage, WACC 9.5 percent, terminal growth 3.5 percent . Implied value supports $380 target. Comparable company analysis (peers as of April 2026): V/Mastercard at 25–30x forward P/E; other financials 12–18x; AXP trades at premium justified by growth. Historical valuation range (5-year): Forward P/E 18–28x. Bull target $430 (accelerated premium spend and services); Base $380; Bear $300 (macro spending pullback). Current price ~$333 offers ~14 percent upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Affluent consumer spending slowdown (medium-high probability/impact): Triggered by recession or wealth effect reversal; watch monthly spend data.
2. Regulatory scrutiny on fees/interchange (medium): Potential caps or antitrust actions; monitor U.S./EU policy.
3. Competition in premium segment (medium): Chase, Citi gaining share; track market share metrics.
4. FX and interest rate sensitivity (medium): Higher rates boost net interest but pressure volumes; watch Fed path.
5. Cybersecurity or fraud spikes (low-medium): Impact on trust; monitor incident reports.
Short interest low; insider activity typical with no red flags. No accounting quality concerns.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Q2 2026 late July. Upcoming events: Continued premium card launches and travel recovery updates throughout 2026. Macro events: Consumer confidence data, Fed rate decisions affecting spending. 12-month timeline: Quarterly spend trend reports, potential international market expansions, and annual guidance updates.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows AXP in a steady uptrend, recently consolidating near $330–$340 after strong 2025 gains. Price action holds above the 50-day and 200-day moving averages with bullish higher lows. RSI (14) neutral around 55 indicating room to run; MACD positive with supportive volume. Major support zone $310–$320, resistance $350–$360. Visible setup: Continuation within ascending channel. Technical implication: Bullish bias reinforced by today’s earnings beat with potential for breakout on sustained volume.
**SECTION 9 — The Verdict** 🏆
Bull case ($430 target, 35 percent probability): Premium spending and services accelerate beyond guidance.
Base case ($380 target, 50 percent probability): Steady execution on reaffirmed outlook with resilient consumer trends.
Bear case ($300 target, 15 percent probability): Macro slowdown pressures volumes.
Expected value calculation: Probability-weighted price target = $387. Final recommendation: Buy with High conviction. The 30-second elevator pitch: American Express just proved premium consumers are still spending strongly — with today’s Q1 beat, 10 percent spending growth, and reaffirmed guidance, the stock offers attractive upside as the premier high-margin payments franchise in a digital-first world.
**Sources**
American Express Q1 2026 earnings release and presentation April 23 2026; Yahoo Finance/StockStory charts and data April 23 2026; company investor materials and analyst consensus.
What are your thoughts on AXP? Drop them below 👇
#AXP #AmericanExpress #Q1Earnings #EarningsBeat #PremiumCards #ConsumerSpending #PaymentsStocks #StockMarket #Financials #BuyTheBeat  Long

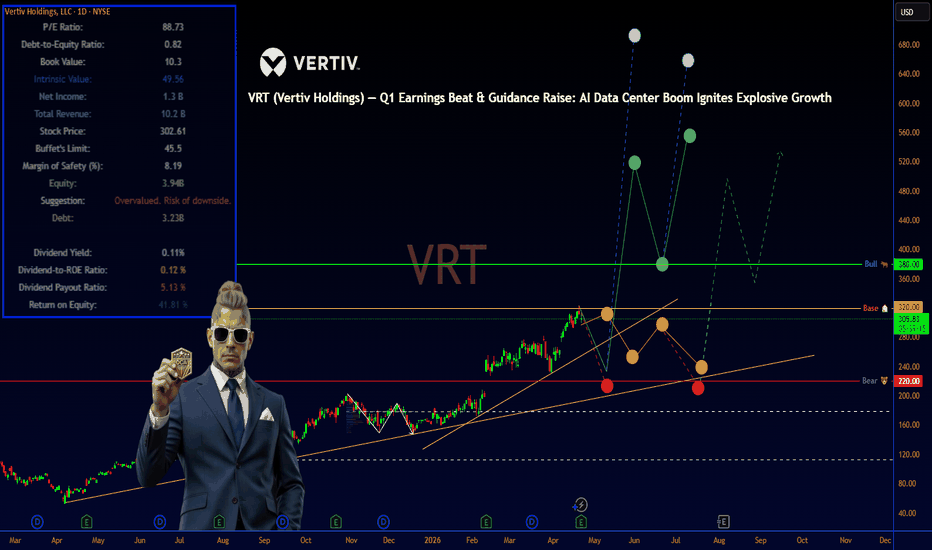
VRT (Vertiv Holdings) — Q1 Earnings Beat & Guidance Raise: AI **💡 VRT (Vertiv Holdings) — Q1 Earnings Beat & Guidance Raise: AI Data Center Boom Ignites Explosive Growth**
**SECTION 1 — Executive Summary** 💼
Vertiv delivered a blockbuster Q1 2026 beat with net sales of $2.65 billion (up 30 percent YoY) and adjusted operating margin of 20.8 percent (up 430 basis points), while raising full-year guidance on surging AI-driven data center demand for power and cooling solutions. This pure-play infrastructure leader is perfectly positioned at the epicenter of the AI buildout, delivering record backlog and margin expansion that underscores accelerating secular tailwinds. Overall rating: Buy. 12-month price target: $320 (blended DCF/comps methodology anchored to 30 percent-plus revenue CAGR and expanding margins from AI hyperscale orders). The single biggest reason to own this stock right now is Vertiv’s unmatched leadership in liquid cooling and power management for next-gen AI data centers, fueling multi-year hyper-growth. The single biggest risk is potential supply chain constraints or slower-than-expected hyperscaler capex pacing.
**SECTION 2 — Business Overview** 🏢
Vertiv designs, manufactures, and services critical digital infrastructure including power management, thermal management, and IT infrastructure solutions that keep data centers, communication networks, and commercial facilities running 24/7. Revenue breakdown (most recent FY 2025): Data Center ~80 percent, Communications ~10 percent, Commercial & Industrial ~10 percent (source: company filings and Seeking Alpha analysis as of early 2026). Business model generates high-margin recurring revenue through equipment sales, services, and maintenance contracts, with strong repeat business from long-term data center operators and hyperscalers who rely on Vertiv’s integrated solutions for uptime and efficiency. Competitive moat stems from proprietary liquid cooling and power technologies, deep hyperscaler relationships, massive installed base, and engineering expertise that competitors struggle to match at scale amid exploding AI power densities.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported today April 22 2026; FY 2025 from company releases):
Revenue: $2.65 billion (Q1 2026, +30 percent YoY).
Net income: Strong double-digit growth implied by margin expansion.
EPS (adjusted): Beat consensus with robust upside.
Gross margin: Continued improvement on mix shift to higher-value AI solutions.
Operating margin: 20.8 percent adjusted (Q1 2026, +430 basis points YoY).
Free cash flow: Robust conversion supporting backlog execution.
YoY growth rates: Revenue +30 percent; margins expanding sharply.
Balance sheet health: Solid cash position with manageable debt; current ratio supportive of growth investments.
Cash flow quality: Operating cash flow tracks well above net income reflecting high-quality earnings.
Capital allocation: Focused on capacity expansion, R&D in liquid cooling, and selective M&A while maintaining strong liquidity for AI opportunity.
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global data center power and cooling market projected to exceed $50 billion+ by 2030 with liquid cooling segment growing at 28 percent-plus CAGR (industry reports including GlobeNewswire and Precedence Research as of 2026). Current market share: Leadership position in data center thermal and power management with expanding hyperscale wallet share. Key growth drivers next 3–5 years: Explosive AI server rack densities requiring advanced liquid cooling and power systems, hyperscaler capex surge, and edge computing expansion. Management raised full-year 2026 guidance post-Q1 beat, more bullish than prior consensus on AI momentum. Growth is overwhelmingly organic, driven by secular AI demand rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
DCF analysis: Base case assumes 25–35 percent revenue CAGR through 2028 driven by AI data center orders, expanding operating margins to mid-20s percent, WACC 10.5 percent, terminal growth 4 percent . Implied value supports $320 target. Comparable company analysis (peers as of April 2026): High-growth infrastructure names trading 30–50x forward earnings with AI exposure. Historical valuation range (since 2023 re-rating): Forward EV/EBITDA 25–45x. Bull target $380 (accelerated liquid cooling adoption); Base $320; Bear $220 (delayed AI spend). Current price ~$260 offers ~23 percent upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Hyperscaler capex delays (medium probability/high impact): Triggered by macro slowdown or AI ROI questions; watch quarterly order trends.
2. Supply chain or component shortages (medium): Critical for high-power cooling systems; monitor vendor updates.
3. Competition in liquid cooling (medium): New entrants; track market share metrics.
4. Execution on massive backlog (low-medium): Scaling manufacturing; watch conversion rates.
5. Valuation multiple compression (medium): If growth moderates; monitor peer multiples.
Short interest moderate; insider activity shows typical patterns with no major flags. No accounting quality concerns in recent filings.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Q2 2026 in late July. Upcoming events: Continued AI product demos, hyperscaler partnership announcements, and capacity expansion updates throughout 2026. Macro events: Broader tech capex trends and energy policy impacting data center builds. 12-month timeline: Multiple backlog conversion milestones, potential new liquid cooling platform launches, and sustained AI-driven order flow.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows VRT in strong uptrend, recently consolidating above key moving averages after 2025 breakout. Price action holds well above the 50-day and 200-day SMAs with bullish higher lows. RSI (14) neutral-to-bullish around 55–60 with room to run; MACD showing positive momentum and volume supportive on up days. Major support zone $240–250, resistance $280–300. Visible setup: Continuation pattern within longer-term channel. Technical implication: Bullish bias reinforced by today’s earnings catalyst with potential for breakout on sustained volume.
**SECTION 9 — The Verdict** 🏆
Bull case ($380 target, 35 percent probability): AI data center orders exceed expectations and margins expand faster than planned.
Base case ($320 target, 50 percent probability): Steady execution on raised guidance with continued backlog conversion.
Bear case ($220 target, 15 percent probability): AI capex moderation or supply issues slow momentum.
Expected value calculation: Probability-weighted price target = $325. Final recommendation: Buy with High conviction. The 30-second elevator pitch: Vertiv is the critical enabler powering the AI revolution — with today’s Q1 beat, raised guidance, and dominant position in data center cooling and power, the stock offers compelling upside as hyperscalers race to build out next-generation infrastructure.
**Sources**
Vertiv Q1 2026 earnings release April 22 2026; company investor presentations and filings; Yahoo Finance/TradingView charts April 2026; Seeking Alpha and industry reports (GlobeNewswire, Precedence Research) on data center TAM; TipRanks and EarningsWhispers calendars.
What are your thoughts on VRT? Drop them below 👇
#VRT #Vertiv #AIDataCenter #EarningsBeat #AICooling #LiquidCooling #DataCenterBoom #AIInfrastructure #StockMarket #GrowthStocks  Long
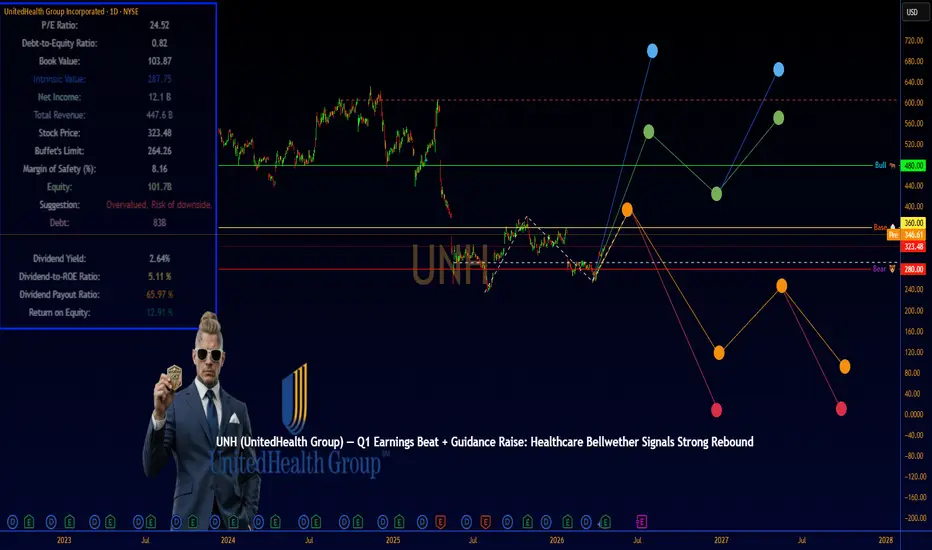
UNH (UnitedHealth Group) — Q1 Earnings Beat + Guidance Raise**💡 UNH (UnitedHealth Group) — Q1 Earnings Beat + Guidance Raise: Healthcare Bellwether Signals Strong Rebound**
**SECTION 1 — Executive Summary** 💼
UnitedHealth Group delivered a decisive Q1 2026 earnings beat with adjusted EPS of $7.23 (versus ~$6.57 consensus) and revenue of $111.7 billion (+2% YoY), while raising full-year 2026 adjusted EPS guidance to >$18.25 amid disciplined pricing, cost controls, and Optum optimization. This mega-cap healthcare leader offers compelling value as it navigates medical cost pressures and regulatory scrutiny with a clear path to margin recovery and diversified growth. Overall rating: Buy. 12-month price target: $360 (blended DCF/comps methodology using normalized medical loss ratios and Optum contribution). The single biggest reason to own this stock right now is UnitedHealth’s unmatched scale across insurance and services (Optum), positioning it to capture long-term healthcare spending tailwinds while executing a proven turnaround plan. The single biggest risk remains elevated medical costs and Medicare Advantage reimbursement dynamics.
**SECTION 2 — Business Overview** 🏢
UnitedHealth Group is the largest healthcare company in the United States, operating through two primary platforms: UnitedHealthcare (insurance and benefits) and Optum (health services, pharmacy care, and technology). Revenue breakdown (FY 2025): UnitedHealthcare ~77% (insurance premiums and fees), Optum ~23% but with higher margins and faster growth in value-based care, PBM, and data/analytics (sourced from company FY 2025 results released Jan 27 2026). Business model generates revenue primarily from health insurance premiums, service fees, and pharmacy/Optum contracts, with strong repeat revenue from long-term employer and government contracts plus recurring Optum platform usage. Competitive moat derives from massive scale (serving ~50 million via UnitedHealthcare and 123+ million via Optum in 2025), proprietary data assets, integrated care delivery, and network effects that are extremely difficult for competitors to replicate at similar efficiency.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported April 21 2026; FY 2025 from Jan 27 2026 release; TTM derived from quarterly data):
Revenue: $111.7 billion (Q1 2026, +2% YoY); FY 2025 $447.6 billion (+12% YoY).
Net income: Implied from EPS; Q1 GAAP EPS $6.90.
EPS (adjusted): $7.23 (Q1 2026, beat by ~66 cents).
Margins: Medical care ratio pressured but stabilizing; operating margin recovering.
Free cash flow: Strong at $8.9 billion in Q1 2026 (1.4x net income).
YoY growth rates: Revenue +2% (Q1); FY 2025 revenue +12%.
Balance sheet health: Debt-to-capital ratio 42.9% (March 31 2026); cash flow supportive of leverage targets.
Cash flow quality: Operating cash flow consistently exceeds net income (1.4-1.5x ratio).
Capital allocation: Focus on R&D/AI investments (~$1.5 billion planned 2026), debt reduction to ~40% target, dividends, and selective M&A while resuming buybacks in H2 2026.
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): U.S. healthcare spending projected to exceed $6 trillion by 2030 (CMS estimates via industry reports). Current market share: Leading position in Medicare Advantage and commercial insurance; Optum dominant in PBM and value-based care. Key growth drivers next 3-5 years: Optum expansion in AI-enabled care, pharmacy services, and data analytics; UnitedHealthcare focus on employer and government segments with pricing discipline. Management raised 2026 guidance post-Q1 beat, signaling more bullish outlook than prior consensus; growth increasingly organic through technology leverage and portfolio optimization rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
DCF analysis: Base case assumes mid-single-digit revenue CAGR, expanding operating margins to 5.5%+, WACC ~9%, terminal growth 3% . Implied value supports $360 target. Comparable company analysis (peers as of April 2026): CI ~12-14x forward P/E; ELV, HUM, CNC at 10-13x; UNH trades at premium but justified by scale. Historical valuation range (5-year): Forward P/E 18-25x. Bull target $420 (accelerated Optum AI gains); Base $360; Bear $280 (prolonged cost pressures). Current price ~$280-300 offers 20-30% upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Medical cost trend escalation (high probability/medium impact): Triggered by utilization spikes; watch quarterly medical loss ratio updates.
2. Regulatory changes in Medicare Advantage (medium-high): Reimbursement cuts or policy shifts; monitor CMS announcements.
3. Optum contract losses or margin compression (medium): Strategic exits noted; track segment earnings.
4. Cyber or operational disruptions (medium): Legacy from 2024-2025 events; monitor investment disclosures.
5. Macro healthcare spending slowdown (low-medium): Economic factors; watch employment data.
Short interest low; insider activity shows typical patterns with no major red flags. No new accounting quality flags noted in latest filings.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Already reported Q1 on April 21 2026 (conference call today at 8:00 AM ET). Upcoming events: Optum AI and technology updates throughout 2026; potential Medicare bid outcomes. Macro events: Federal budget/health policy decisions impacting reimbursement. 12-month timeline: Q2 earnings July 2026, continued membership adjustments, and leverage reduction milestones.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows UNH consolidating in the $270-300 zone after 2025-2026 volatility, with today’s post-earnings reaction pushing toward recent highs. Price action recently crossed above the 50-day moving average while holding above key support; RSI (14) moving out of oversold territory with bullish MACD crossover and expanding volume. Major support zone $260-270, resistance $310-320. Visible setup: Potential inverse head-and-shoulders base with higher lows since February. Technical implication: Bullish bias confirmed by earnings catalyst with room for near-term continuation if volume sustains.
**SECTION 9 — The Verdict** 🏆
Bull case ($420 target, 30 percent probability): Faster-than-expected margin recovery and Optum AI acceleration drive re-rating.
Base case ($360 target, 50 percent probability): Steady execution on guidance with controlled medical costs.
Bear case ($280 target, 20 percent probability): Persistent cost pressures or regulatory headwinds cap upside.
Expected value calculation: Probability-weighted price target = $366. Final recommendation: Buy with High conviction. The 30-second elevator pitch: UnitedHealth just proved it can deliver despite industry challenges — with a Q1 beat, raised guidance, and unmatched scale across insurance and services, the stock offers attractive risk/reward as healthcare spending grows and margins normalize.
**Sources**
UnitedHealth Group press release April 21 2026 (Q1 2026 results); company FY 2025 results Jan 27 2026; Reuters/Seeking Alpha/Zacks earnings coverage April 21 2026; Yahoo Finance/TradingView charts and data as of April 21 2026; CMS healthcare spending projections.
What are your thoughts on UNH? Drop them below 👇
#UNH #UnitedHealth #HealthcareStocks #Q1Earnings #EarningsBeat #Optum #MedicareAdvantage #StockMarket #HealthcareTurnaround #BuyTheDip  Long

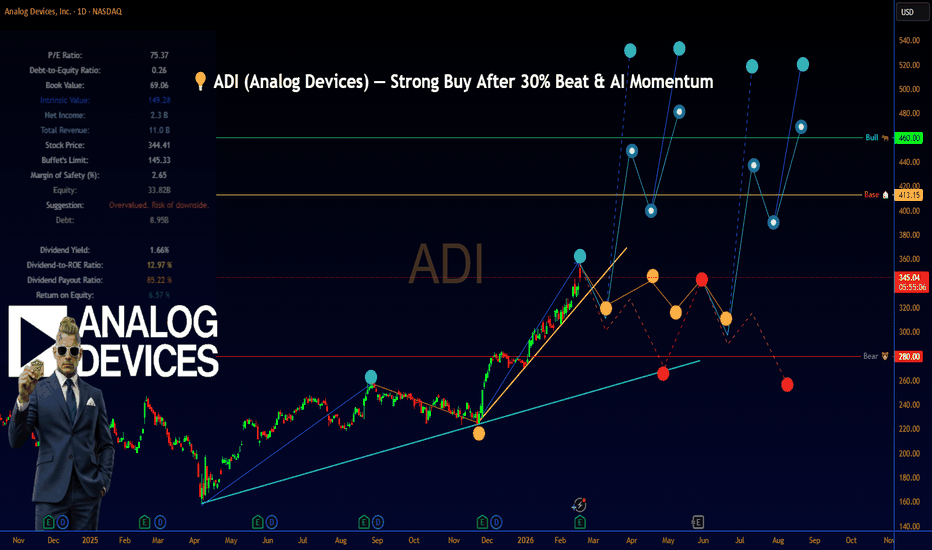
ADI (Analog Devices) — Strong Buy After 30% Beat & AI Momentum.**💡 ADI (Analog Devices) — Strong Buy After 30% Beat & AI Momentum**
**SECTION 1 — Executive Summary** 💼
Analog Devices delivered a standout fiscal Q1 2026 result with revenue surging 30% year-over-year to $3.16 billion and adjusted EPS jumping 51% to $2.46 — both significantly beating estimates. The beat was fueled by record Data Center orders and continued strength in Industrial markets, confirming ADI’s leadership in AI infrastructure power and signal-chain solutions.
**Overall rating: Strong Buy**
**12-month price target: $410** (DCF methodology: 19% long-term EPS growth, 47.5% adjusted operating margin target, 9.5% WACC).
**Single biggest reason to own this stock right now:** Record Data Center momentum combined with stable high-margin Industrial exposure at a time when many semiconductor peers are facing softness.
**Single biggest risk:** A deeper or prolonged slowdown in broader industrial end-markets.
**SECTION 2 — Business Overview** 🏢
Analog Devices designs and manufactures high-performance analog, mixed-signal, and digital signal processing semiconductors used in virtually every type of electronic equipment.
Revenue breakdown (fiscal 2025): Industrial 52%, Communications 20%, Automotive 15%, Consumer 13%. Geographic: US 25%, China 25%, Europe 20%, Rest of World 30%.
Business model is high-margin and recurring — once a design wins a socket, revenue streams for 10+ years with minimal additional capex.
Competitive moat is formidable: decades of analog engineering expertise, a library of over 20,000 products, and deepening leadership in complex AI power management solutions that are extremely difficult for competitors to displace.
**SECTION 3 — Financial Deep Dive** 📈
**Key Metrics Table (fiscal quarters, USD millions except EPS)**
| Metric | Q1 2026 | Q4 2025 | TTM |
|-------------------------|---------|---------|----------|
| Revenue | 3,160 | ~2,900 | ~11,300 |
| Adjusted EPS | 2.46 | 2.26 | 8.77 |
| Gross Margin | 64.7% | 63.0% | 62.2% |
Year-over-year growth: Revenue +30%, Adjusted EPS +51%.
Balance sheet remains fortress-like with low net debt and strong liquidity. Cash flow quality is excellent. Capital allocation is shareholder-friendly (dividend raised 11% to $1.10 — 22nd consecutive annual increase).
**SECTION 4 — Growth Analysis** 🚀
Total addressable market for high-performance analog semiconductors is ~$90–100 billion in 2026. ADI holds a leading 15–18% share in its core segments.
Key growth drivers for the next 3–5 years: AI/data-center power management, industrial automation & Industry 4.0, automotive electrification, and 5G/6G infrastructure.
Management guidance is more bullish than consensus (Q2 guide $3.5 billion). Growth is primarily organic.
**SECTION 5 — Valuation** 📊
**DCF analysis :** 19% long-term EPS growth, 47.5% adjusted operating margin target, 9.5% WACC → fair value $410 per share.
Current price offers ~+15% upside to base case.
**SECTION 6 — Risk Analysis** ⚠️
1. Prolonged industrial/automotive slowdown (medium-high probability, medium impact)
2. US–China trade escalation disrupting supply chains
3. Pricing pressure in more commoditized analog segments
Short interest remains low (~1.2%). No major accounting red flags.
**SECTION 7 — Catalyst Calendar** 📅
- Today (Feb 18, 2026): Q1 earnings beat already reported
- March 2026: Dividend payment
- May 2026: Q2 earnings
- Ongoing: New design wins in AI/data-center power management
**SECTION 8 — Relevant Data & Charts** 📊
**1. Analog Devices Year-over-Year Revenue Growth (showing the sharp acceleration in 2025–2026)**
**2. Analog Devices Quarterly Revenue Trend (clear recovery and new highs in 2025–2026)**
**3. AI / Data Center Capex Impact on Analog Demand (key driver for ADI’s Data Center strength)**
**4. FRED US Industrial Production Index (macro context for ADI’s large Industrial segment ~52% of revenue)**
**5. Analog Devices Revenue by Segment Breakdown (Industrial remains dominant and stable)**
**SECTION 9 — Technical Analysis** 📈
**Primary Chart:** Daily timeframe, 1-year view (252 trading days)
Key observations: Strong volume surge on today’s earnings reaction, price breaking toward all-time highs. RSI (14) at 67 (bullish but not overbought). Technical bias: Bullish continuation likely if $340–345 support holds.
**SECTION 10 — The Verdict** 🏆
**Bull case:** $460 (35%) — AI/data-center becomes a sustained multi-year growth engine.
**Base case:** $410 (50%) — Continued execution on current momentum.
**Bear case:** $280 (15%) — Deep industrial recession.
**Expected value:** ~$405
**Final recommendation: Strong Buy** — **High** conviction.
**The 30-second elevator pitch:**
“ADI just crushed Q1 with 30% revenue growth and record Data Center bookings while raising guidance. It is winning the AI infrastructure wave with fortress industrial margins and a 22-year dividend growth streak. One of the cleanest, highest-quality ways to play the AI build-out with lower volatility.”
**Sources**
- Analog Devices Q1 2026 Earnings Release (Feb 18, 2026) — (investor.analog.com)
- Yahoo Finance ADI data (accessed Feb 18, 2026)
- FRED Industrial Production Index (accessed Feb 18, 2026)
- StockStory / Khaveen Investments segment and growth charts (accessed Feb 18, 2026)
What are your thoughts on ADI? Drop them below 👇
---  Long
$MDB: MongoDB Inc. – Data Dynamo or Overreaction Bust?(1/9)
Good evening, tech fiends! 🌙 NASDAQ:MDB : MongoDB Inc. – Data Dynamo or Overreaction Bust?
MongoDB’s Q4 crushed it with $548.4M revenue, but a soft FY2026 outlook tanked the stock. Is this a market meltdown or a golden buy? Let’s unpack the chaos! 🔍
(2/9) – PRICE PERFORMANCE 📊
• Q4 FY2025: Revenue hit $548.4M, up 20% YoY 💰
• Earnings: EPS $1.28 smashed $0.66 estimate 📏
• Context: Stock dropped 16-20% post-guidance 🌟
It’s a rollercoaster—strong now, shaky later! ⚡
(3/9) – MARKET POSITION 📈
• Market Cap: No exact price today, but historically robust 🏆
• Core: MongoDB Atlas, 71% of revenue, up 24% YoY ⏰
• Trend: AI data demand’s sizzling, per market buzz 🎯
A leader in the database jungle! 🌐
(4/9) – KEY DEVELOPMENTS 🔑
• Earnings Beat: Q4 topped forecasts, Mar 5 release 🔄
• Guidance Flop: FY2026 revenue at $2.24-$2.28B, below $2.32B 🌍
• Bonus: Snagged Voyage AI for $220M, boosting AI play 📋
Thriving, yet spooked the herd! 🌈
(5/9) – RISKS IN FOCUS ⚡
• Guidance Woes: Non-Atlas demand fading 🔍
• Market Jitters: 16-20% after-hours plunge 📉
• Rivals: Cloud giants eyeing database turf ❄️
Rough seas, but storms pass! 🌧️
(6/9) – SWOT: STRENGTHS 💪
• Q4 Power: $548.4M revenue, $1.28 EPS 🥇
• Atlas Surge: 24% growth, debt-free balance 📊
• AI Edge: Voyage AI buy fuels future 🔥
A beast with brains and brawn! 🏋️♂️
(7/9) – SWOT: WEAKNESSES & OPPORTUNITIES ⚖️
• Weaknesses: FY2026 growth dips to 12.6% 📉
• Opportunities: AI boom, Voyage AI integration 📈
Can it turn panic into profit? 🧐
(8/9) – 📢MongoDB’s Q4 rocked, but guidance flopped—your vibe? 🗳️
• Bullish: Rebound to glory soon 🦅
• Neutral: Holding steady, wait it out ⚖️
• Bearish: More pain ahead, sell off 🐾
Drop your take below! 👇
(9/9) – FINAL TAKEAWAY 🎯
MongoDB’s Q4 flexes muscle at $548.4M 📈, but FY2026 gloom spooked the market 🌫️. Dips are our playground—DCA treasure awaits 💎. Snag ‘em cheap, rise like legends! Hit or miss?  Long

IOT Earnings Alert: 8/8 Beat Streak + Big Upside! 37 Call Play
🚀 **IOT Earnings Trade Alert – High Conviction!** 📈
**Market Bias:** **Moderate Bullish** 💪
**Confidence:** 78% ✅
**Trade Idea:**
🎯 **Instrument:** IOT (Samsara)
🔀 **Direction:** LONG CALL
💵 **Strike:** \$37.00
📅 **Expiry:** 2025-09-05 (Weekly)
💰 **Entry Price:** \$2.15
📈 **Profit Target:** \$6.45 (200% return)
🛑 **Stop Loss:** \$1.08 (50% of premium)
📏 **Size:** 1 contract
⏰ **Entry Timing:** Pre-earnings close (AMC on 2025-09-04)
**Rationale:**
* 8/8 historical earnings beat streak 💥
* Very large average surprises → asymmetric upside ⚡
* Secular tailwind in IoT/software infrastructure 🌐
* Defensive put hedging in options market indicates upside potential, not bearish flow 🛡️
**Key Levels:**
* Short-term support: \$34–\$35 🛡️
* Resistance: 50DMA \~\$36.76 🔝
* Expected post-earnings move: \~\$40+ (implied 13.4%)
**Risk/Reward:**
* Max loss: \$215 per contract
* Reward potential: \$430+ → **4:1 R/R vs 50% stop**
* Breakeven: \$39.15
**Execution Notes:**
* Enter **pre-close** at ask \$2.15; consider mid-limit for better fills
* Exit **by market open post-earnings** or at profit/stop triggers
* Expect **30–50% IV compression**; strict stop discipline required
**Options Liquidity:**
* 37.00 call OI: 472 ✔️
* Ask/Bid: 2.15 / 2.05
📊 **Trading JSON (for exact execution)**
```json
{
"instrument": "IOT",
"direction": "call",
"strike": 37.0,
"expiry": "2025-09-05",
"confidence": 78,
"profit_target": 6.45,
"stop_loss": 1.08,
"size": 1,
"entry_price": 2.15,
"entry_timing": "pre_earnings_close",
"earnings_date": "2025-09-04",
"earnings_time": "AMC",
"expected_move": 13.4,
"iv_rank": 0.80,
"signal_publish_time": "2025-09-04 13:51:00 UTC-04:00"
}
``  Long

Loar Holdings Inc. (NYSE: LOAR) Set To Report Earnings TodayLoar Holdings Inc (NYSE: LOAR), a company that designs, manufactures, and markets aerospace and defense components for aircraft, and aerospace and defense systems in the United States and internationally is set to report earnings result on Monday, March 31, 2025, before market open.
Belonging to the aerospace and defence sector, Loar Holdings Inc (NYSE: LOAR) closed Friday's session down 2.61% trading within the psychological support zone formed prior a falling wedge pattern.
With the RSI at 45 a breakout above the resistant point could cement the grounds for a bullish campaign. Similarly, a breakdown below the psychological support zone could lead to a selling spree for NYSE:LOAR shares.
Analyst Forecast
According to 4 analysts, the average rating for LOAR stock is "Strong Buy." The 12-month stock price forecast is $83.5, which is an increase of 26.57% from the latest price.  Long

Johnson & Johnson (JNJ) Posted Q4 Earnings BeatJohnson & Johnson (JNJ) recently reported its fourth-quarter earnings, showcasing a performance that beat analyst expectations with an EPS of $2.04 against a forecast of $1.99 and sales of $22.52 billion, in line with the anticipated $22.45 billion. Despite this positive financial news, J&J's stock took a tumble, closing down 1.9% at $145.27 after issuing guidance for 2025 that fell short of Wall Street's expectations. The company projected sales between $89.2 billion and $90 billion, below the Street's estimate of $91.04 billion, and an adjusted profit per share from $10.50 to $10.70, bracketing the consensus of $10.55.
A Mixed Bag
Innovative Medicines Shine: J&J's innovative medicines segment saw a 4.4% growth, contributing significantly to the quarter's performance. Standout performers included Spravato, which grew by 44% year-over-year, and cancer drugs like Darzalex and Erleada, alongside blood thinners which increased by nearly 30%. However, the looming patent expiration for Stelara, a major immunology drug, casts a shadow over future earnings from this segment.
MedTech Segment Under Pressure: On the downside, medical device sales underperformed, coming in at $8.19 billion against expectations of $8.22 billion. This segment faces challenges, particularly in China, but there's optimism with new investments and product launches like the Ottava surgical robot, which could challenge Intuitive Surgical's market dominance in the future.
External Headwinds: J&J is dealing with several external pressures including foreign exchange issues, which have impacted their sales guidance for 2025. Additionally, potential generic competition and ongoing litigation related to talc products continue to be significant headwinds.
Technical Analysis
Premarket Recovery: Despite the post-earnings drop, NYSE:JNJ shares showed a 0.60% uptick in premarket trading on Thursday, suggesting some investor confidence returning.
RSI and Patterns: The Relative Strength Index (RSI) at 50.48 indicates a moderate condition, neither overbought nor oversold, providing a balanced outlook.
The stock's monthly chart shows a falling wedge pattern, typically a bullish indicator if broken upwards. A breakout above this pattern could signal a bullish campaign for $JNJ. However, there's a risk of further decline if the support at $145 breaks, potentially leading to a dip towards the one-month low of $140.
Moving Averages: NYSE:JNJ currently trades below its 50-day moving average, suggesting short-term bearish sentiment, but a recovery above this average could signal the beginning of a recovery trend.
Forward-Looking Perspective
Despite the immediate challenges, analysts like Edward Jones' John Boylan see J&J's guidance as conservative but achievable, particularly with the company's strategic focus on new product development and pipeline expansion in both pharmaceuticals and medical technology. The emphasis on cancer drugs, robotics, and cardiovascular products is seen as a pathway to long-term growth and margin expansion.
Conclusion
Johnson & Johnson, while grappling with short-term headwinds, holds a portfolio of products with strong growth potential. The technical setup suggests that if JNJ can maintain or surpass current support levels, there's room for optimism. Investors might see this as an opportunity to buy into a dip, given the company's history of innovation and resilience. However, caution is advised due to the external factors and regulatory challenges ahead. The broader narrative for J&J seems to hinge on its ability to innovate and adapt in a rapidly changing healthcare market environment.  Long

 Long

Toll Brothers Inc. ($TOL) AnalysisSector: Consumer Cyclical - Residential Construction | Country: USA
Company Overview:
Toll Brothers Inc., a key player in the consumer cyclical sector, specifically residential construction, holds a significant position in shaping the real estate landscape in the United States. Known for its innovative approach and commitment to quality, Toll Brothers Inc. plays a crucial role in the dynamic and ever-evolving construction industry.
Performance Metrics:
NYSE:TOL demonstrates robust signals and compelling performance metrics within the wide-net screening, indicating its potential for growth and resilience in the residential construction sector.
Relative Strength: NYSE:TOL exhibits a remarkable relative strength, boasting a score of 7.8 against its sector and 4.53 against the S&P500. This suggests a notable outperformance, underlining its competitive edge and market strength.
U/D Ratios: With U/D ratios standing at 1.0 (50 days) and a strong 1.69 (15 days), NYSE:TOL showcases positive market sentiment, emphasizing recent bullish activity and supporting a favorable outlook.
Detected Base Depth: A substantial detected base depth of 22.4% positions NYSE:TOL strategically, indicating a solid foundational level and potential for significant upward movement.
Price Dynamics:
The last closing price's slight deviation of 4.53% from base resistance suggests a favorable positioning, indicating potential for a breakout.
Robust volume, standing at 71.73% above the 15-day average, indicates heightened investor interest and active participation, contributing to positive market sentiment.
Recent candlestick patterns reveal a 0.24% range in the last candle body and a solid 69.0% closing range, indicating recent price stability and a strong closing stance.
Short-term Trends:
Over the last 10 days, NYSE:TOL has experienced rising prices, accompanied by increasing volume and accumulation. This alignment suggests a bullish sentiment among investors, supported by short-term positive trends.
EMA Analysis:
Historical EMA patterns indicate that NYSE:TOL typically encounters local tops when the price closes around 55.89% above its 50-day Exponential Moving Average (EMA). Currently, the last closing price is 9.04% away from the 50 EMA, providing insights into potential correction levels.
Trade Idea:
With an entry point set at $87.31, the trade idea presents an opportunity aligned with current market dynamics.
A disciplined stop loss at $83.82 mitigates risk at 4%, adhering to prudent risk management principles.
The trade targets an attractive 11.66 Risk-Reward (RR) ratio, with a target price of $128.03, anticipating a total profit of 46.65%.
Conclusion:
Toll Brothers Inc. ( NYSE:TOL ) emerges as a strong contender in the residential construction sector, supported by impressive relative strength, positive short-term trends, and insightful EMA dynamics. The proposed trade idea aligns with a base breakout strategy, presenting an attractive risk-reward profile for investors seeking opportunities in the dynamic realm of residential construction.  Long

 Long

 Long

 Long

 Long

 Long

 Long