Long
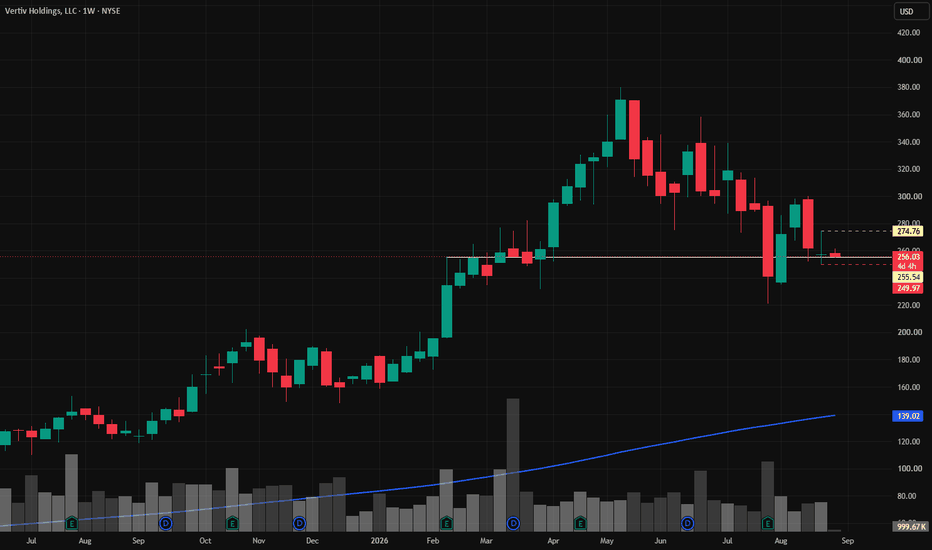
TD Cowen Lifts Price Target on Vertiv Following Strong Q1 ResultOn May 20, 2026, TD Cowen analyst Lance Vitanza raised the firm's price target on Vertiv Holdings Co (NYSE: VRT) to 387 from 347. Vitanza also maintained a Buy rating on the shares, signaling continued confidence in the company's prospects.
In its research note, TD Cowen highlighted that Vertiv left its 2026 guidance unchanged, which may have been seen by some as a cautious move. However, the firm placed greater emphasis on the company's updated long-term outlook. Vertiv now projects a five-year organic revenue compound annual growth rate (CAGR) of between 20% and 22%, along with adjusted operating margins exceeding 27% by the year 2030. TD Cowen commented that it views both the long-term revenue target and the margin target as conservative, suggesting that actual results could potentially surpass these figures if market conditions remain favorable.
RBC Capital Also Boosts Its Price Target
Separately, RBC Capital analyst Deane Dray also raised the firm's price target on Vertiv. Dray increased the target to 435 from 356 and maintained an Outperform rating on the shares. In its note to clients, RBC explained that Vertiv's investor event, held on May 19 and May 20, is expected to highlight the company's strong positioning within the rapidly expanding market for data center power and cooling technologies.
RBC added that it expects Vertiv to grow revenue organically by at least 20% to 25% annually through 2030. The firm also anticipates that Vertiv will generate incremental margins of between 25% and 30%, a level of operational leverage that RBC believes will support what it calls sector-leading earnings per share (EPS) growth potential. Taken together, these projections paint a picture of a company poised to benefit from sustained, multi-year demand drivers.
Company Overview
Vertiv Holdings Co (NYSE: VRT) designs, manufactures, and services critical infrastructure technologies and solutions for a variety of demanding environments. Its core markets include data centers, communication networks, and industrial facilities around the world. As the demand for reliable, efficient, and scalable digital infrastructure continues to grow—driven by cloud computing, AI, and edge computing—Vertiv's offerings have become increasingly essential to the global economy. Long 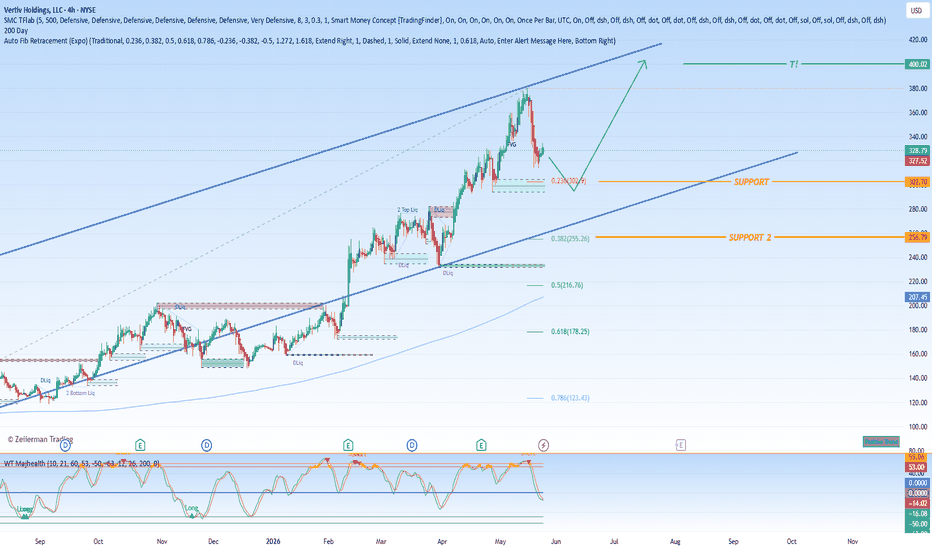
VRT (Vertiv Holdings) — Q1 Earnings Beat & Guidance Raise: AI **💡 VRT (Vertiv Holdings) — Q1 Earnings Beat & Guidance Raise: AI Data Center Boom Ignites Explosive Growth**
**SECTION 1 — Executive Summary** 💼
Vertiv delivered a blockbuster Q1 2026 beat with net sales of $2.65 billion (up 30 percent YoY) and adjusted operating margin of 20.8 percent (up 430 basis points), while raising full-year guidance on surging AI-driven data center demand for power and cooling solutions. This pure-play infrastructure leader is perfectly positioned at the epicenter of the AI buildout, delivering record backlog and margin expansion that underscores accelerating secular tailwinds. Overall rating: Buy. 12-month price target: $320 (blended DCF/comps methodology anchored to 30 percent-plus revenue CAGR and expanding margins from AI hyperscale orders). The single biggest reason to own this stock right now is Vertiv’s unmatched leadership in liquid cooling and power management for next-gen AI data centers, fueling multi-year hyper-growth. The single biggest risk is potential supply chain constraints or slower-than-expected hyperscaler capex pacing.
**SECTION 2 — Business Overview** 🏢
Vertiv designs, manufactures, and services critical digital infrastructure including power management, thermal management, and IT infrastructure solutions that keep data centers, communication networks, and commercial facilities running 24/7. Revenue breakdown (most recent FY 2025): Data Center ~80 percent, Communications ~10 percent, Commercial & Industrial ~10 percent (source: company filings and Seeking Alpha analysis as of early 2026). Business model generates high-margin recurring revenue through equipment sales, services, and maintenance contracts, with strong repeat business from long-term data center operators and hyperscalers who rely on Vertiv’s integrated solutions for uptime and efficiency. Competitive moat stems from proprietary liquid cooling and power technologies, deep hyperscaler relationships, massive installed base, and engineering expertise that competitors struggle to match at scale amid exploding AI power densities.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported today April 22 2026; FY 2025 from company releases):
Revenue: $2.65 billion (Q1 2026, +30 percent YoY).
Net income: Strong double-digit growth implied by margin expansion.
EPS (adjusted): Beat consensus with robust upside.
Gross margin: Continued improvement on mix shift to higher-value AI solutions.
Operating margin: 20.8 percent adjusted (Q1 2026, +430 basis points YoY).
Free cash flow: Robust conversion supporting backlog execution.
YoY growth rates: Revenue +30 percent; margins expanding sharply.
Balance sheet health: Solid cash position with manageable debt; current ratio supportive of growth investments.
Cash flow quality: Operating cash flow tracks well above net income reflecting high-quality earnings.
Capital allocation: Focused on capacity expansion, R&D in liquid cooling, and selective M&A while maintaining strong liquidity for AI opportunity.
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global data center power and cooling market projected to exceed $50 billion+ by 2030 with liquid cooling segment growing at 28 percent-plus CAGR (industry reports including GlobeNewswire and Precedence Research as of 2026). Current market share: Leadership position in data center thermal and power management with expanding hyperscale wallet share. Key growth drivers next 3–5 years: Explosive AI server rack densities requiring advanced liquid cooling and power systems, hyperscaler capex surge, and edge computing expansion. Management raised full-year 2026 guidance post-Q1 beat, more bullish than prior consensus on AI momentum. Growth is overwhelmingly organic, driven by secular AI demand rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
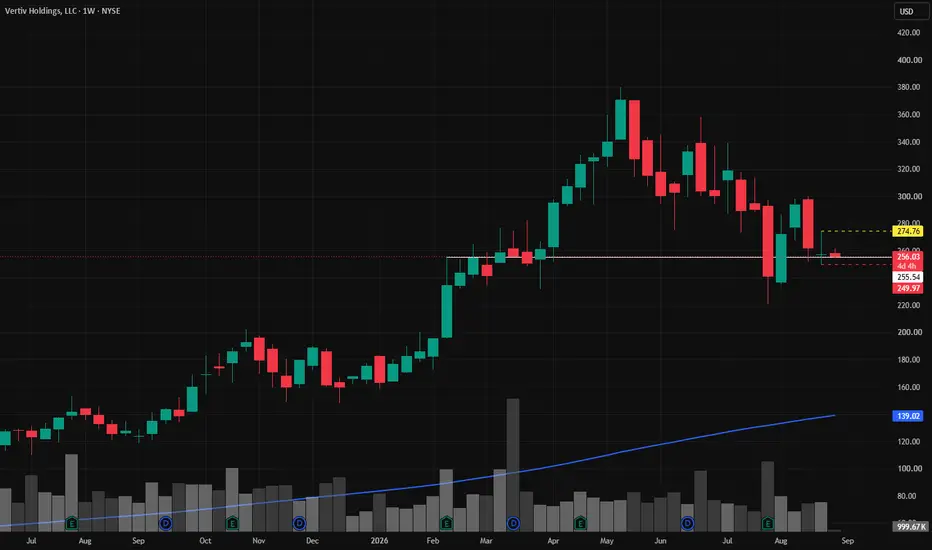
DCF analysis: Base case assumes 25–35 percent revenue CAGR through 2028 driven by AI data center orders, expanding operating margins to mid-20s percent, WACC 10.5 percent, terminal growth 4 percent . Implied value supports $320 target. Comparable company analysis (peers as of April 2026): High-growth infrastructure names trading 30–50x forward earnings with AI exposure. Historical valuation range (since 2023 re-rating): Forward EV/EBITDA 25–45x. Bull target $380 (accelerated liquid cooling adoption); Base $320; Bear $220 (delayed AI spend). Current price ~$260 offers ~23 percent upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Hyperscaler capex delays (medium probability/high impact): Triggered by macro slowdown or AI ROI questions; watch quarterly order trends.
2. Supply chain or component shortages (medium): Critical for high-power cooling systems; monitor vendor updates.
3. Competition in liquid cooling (medium): New entrants; track market share metrics.
4. Execution on massive backlog (low-medium): Scaling manufacturing; watch conversion rates.
5. Valuation multiple compression (medium): If growth moderates; monitor peer multiples.
Short interest moderate; insider activity shows typical patterns with no major flags. No accounting quality concerns in recent filings.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Q2 2026 in late July. Upcoming events: Continued AI product demos, hyperscaler partnership announcements, and capacity expansion updates throughout 2026. Macro events: Broader tech capex trends and energy policy impacting data center builds. 12-month timeline: Multiple backlog conversion milestones, potential new liquid cooling platform launches, and sustained AI-driven order flow.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows VRT in strong uptrend, recently consolidating above key moving averages after 2025 breakout. Price action holds well above the 50-day and 200-day SMAs with bullish higher lows. RSI (14) neutral-to-bullish around 55–60 with room to run; MACD showing positive momentum and volume supportive on up days. Major support zone $240–250, resistance $280–300. Visible setup: Continuation pattern within longer-term channel. Technical implication: Bullish bias reinforced by today’s earnings catalyst with potential for breakout on sustained volume.
**SECTION 9 — The Verdict** 🏆
Bull case ($380 target, 35 percent probability): AI data center orders exceed expectations and margins expand faster than planned.
Base case ($320 target, 50 percent probability): Steady execution on raised guidance with continued backlog conversion.
Bear case ($220 target, 15 percent probability): AI capex moderation or supply issues slow momentum.
Expected value calculation: Probability-weighted price target = $325. Final recommendation: Buy with High conviction. The 30-second elevator pitch: Vertiv is the critical enabler powering the AI revolution — with today’s Q1 beat, raised guidance, and dominant position in data center cooling and power, the stock offers compelling upside as hyperscalers race to build out next-generation infrastructure.
**Sources**
Vertiv Q1 2026 earnings release April 22 2026; company investor presentations and filings; Yahoo Finance/TradingView charts April 2026; Seeking Alpha and industry reports (GlobeNewswire, Precedence Research) on data center TAM; TipRanks and EarningsWhispers calendars.
What are your thoughts on VRT? Drop them below 👇
#VRT #Vertiv #AIDataCenter #EarningsBeat #AICooling #LiquidCooling #DataCenterBoom #AIInfrastructure #StockMarket #GrowthStocks Long 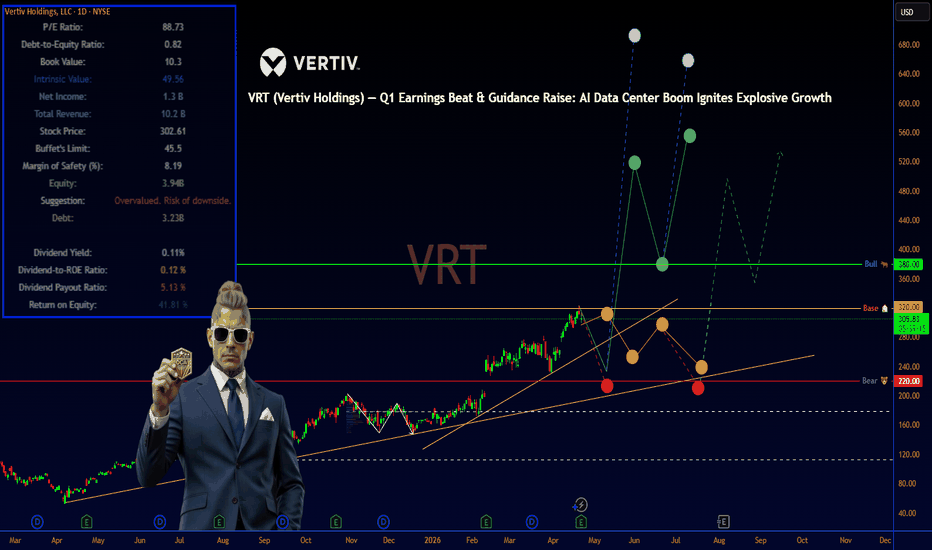
Education 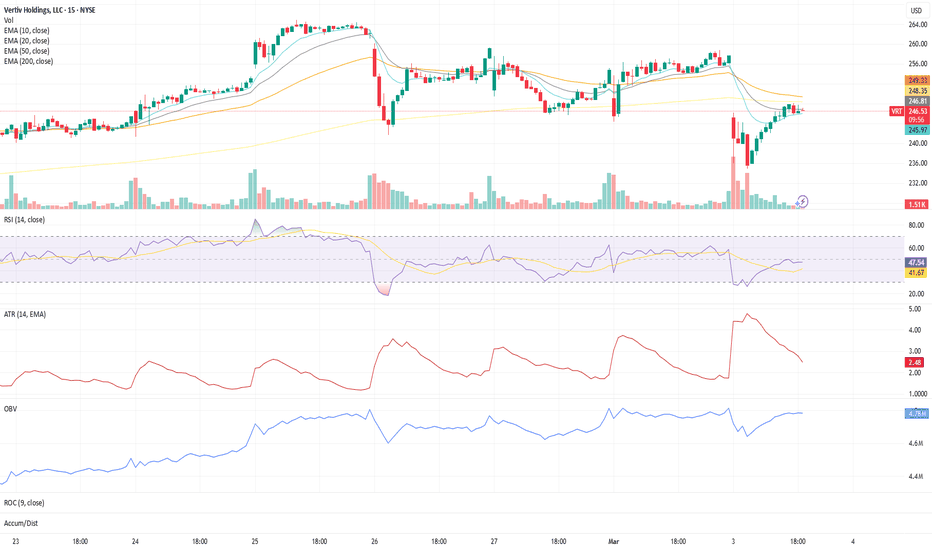
Education 
$VRT: The Critical Infrastructure Enabler in the AI EpochVertiv Holdings Co. (NYSE: VRT) stands at the electrifying confluence of two of the most powerful secular trends of our time: the relentless global adoption of artificial intelligence (AI) and the consequent, hyper-accelerated build-out of next-generation data center infrastructure. As the indispensable provider of the critical power, thermal management, and infrastructure solutions that make these digital cathedrals possible, Vertiv is not merely participating in a boom—it is laying its very foundation. The company's recent financial and operational performance paints a picture of an enterprise operating at the zenith of market demand, yet its premium valuation and the emergence of formidable competitors frame a complex and pivotal investment narrative of extraordinary growth tempered by execution risk.
The Core Bull Thesis: Structural Demand, Unrivaled Positioning, and Unprecedented Visibility
The investment case for Vertiv is anchored in its role as a system-level architect for the AI revolution. With approximately 80% of its revenue tied to data centers, Vertiv is a pure-play on the infrastructure bottleneck created by AI's insatiable appetite for power and cooling. Its product portfolio—spanning advanced thermal management, liquid cooling, uninterruptible power supplies (UPS), and power distribution—is not a collection of components but an integrated ecosystem. This is evidenced by its deep, collaborative partnerships with industry titans like NVIDIA, with whom Vertiv is co-developing the 800-volt DC power portfolio for NVIDIA's future Rubin Ultra platform.
The financial evidence of this privileged position is staggering:
Explosive Growth: The Americas region saw organic sales surge 43% in Q3 2025, with APAC growing 21%, underscoring the geographic spread of AI infrastructure demand.
Unparalleled Forward Visibility: A book-to-bill ratio of 1.4x and a backlog that swelled to $9.5 billion (up 30% year-over-year) provide multi-year revenue visibility, arguably extending into 2026 and beyond. This is not speculative demand; it is contracted, tangible future work.
Strategic Evolution: Vertiv is intelligently shifting its model towards higher-value, system-level solutions like OneCore and SmartRun, which increase its "content per rack" and deepen customer stickiness. Its growing Services segment (over 20% of revenue) builds a high-margin, recurring revenue moat around its hardware, further solidified by strategic acquisitions like PurgeRite in liquid cooling maintenance.
The Looming Challenge: An Arena of Giants and the Valuation Ceiling
However, Vertiv’s arena is attracting other well-capitalized and ambitious players, transforming a niche into a fiercely competitive battleground.
Super Micro Computer (SMCI) is expanding beyond servers into full-rack, liquid-cooled AI solutions, directly competing on the performance-per-rack density that hyperscalers crave.
Hewlett Packard Enterprise (HPE), with its broad IT portfolio and recent Juniper Networking integration, is positioning itself as a one-stop shop for AI-native infrastructure, from compute to networking to operations.
This competitive intensification raises critical questions. Can Vertiv maintain its pricing power and margin trajectory as more players vie for the same massive contracts? Its current premium valuation leaves little room for error.
Valuation at a Crossroads:
Trading at a trailing P/E of ~60x and a forward P/E of ~30x, with a Price/Book multiple of 18.12x (far above the sector's 10.65x), the market has unequivocally priced in years of continued high-teens growth and margin expansion. The stock’s ‘D’ Value Score is a stark reminder of this premium. Future returns from the current ~$160 level are likely to be driven almost entirely by earnings delivery rather than further multiple expansion. Any stumble in growth or margin compression could trigger a severe derating.
Technical Analysis: Mapping the High-Stakes Risk/Reward Landscape
The stock's meteoric rise has been followed by a consolidation phase, creating defined technical levels that outline the potential paths forward and zones of critical support.
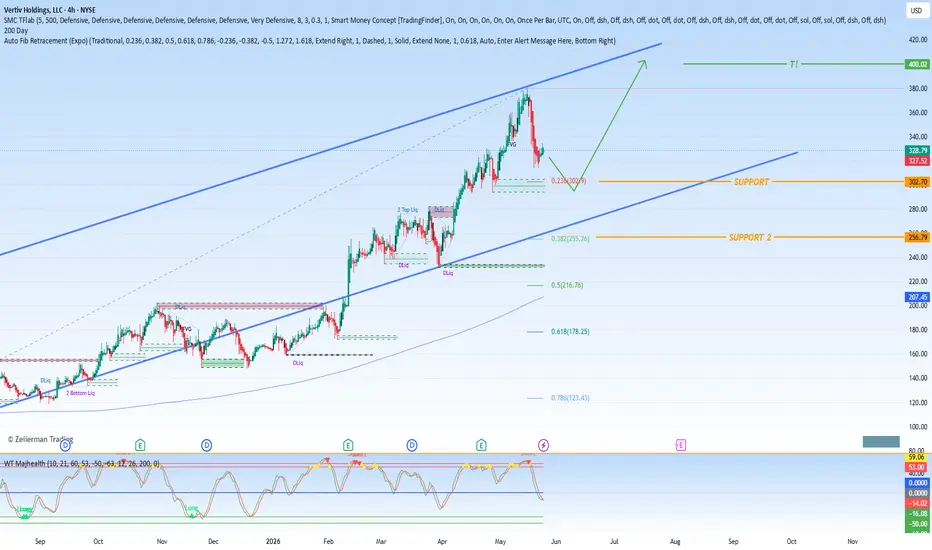
Major Psychological & Technical Support at ~$150: This round-number level represents the first major line of defense for the bull trend. A sustained hold above $150 would indicate that the underlying institutional conviction in the long-term story remains intact, treating the recent pullback as a healthy digestion of gains.
Fibonacci Retracement Support Ladder (Post-Surge Correction):
Should selling pressure intensify, a series of Fibonacci retracement levels from the stock’s prior major advance offer logical areas for potential stabilization and buyer re-entry:
Initial Support Zone at ~$145.59 (0.382 Fib): A shallow, healthy correction level. A rebound from here would signal strong ongoing momentum.
Intermediate Support Zone at ~$128.03 (0.5 Fib): A deeper correction to this midpoint would reflect growing investor caution over valuation or near-term execution. It would represent a more significant test of the trend’s strength.
Critical Support Zone at ~$110.46 (0.618 Fib): A decline to this level would signify a major technical breakdown, likely coinciding with a broader sector sell-off, a significant earnings miss, or rising fears of an AI capex slowdown. For long-term believers, this zone could present a high-conviction, albeit high-risk, entry point.
Take-Profit Target at $200: This represents the next major psychological and technical milestone. A climb to $200 would require the bull thesis to play out flawlessly: consistent quarterly beats, sustained backlog conversion, and successful navigation of competitive pressures. It frames a meaningful ~25% upside from current levels, but the journey will be contingent on perfect execution in a dynamic market.
Final Synthesis: A Premium Bet on the AI Physical Layer
Vertiv is a quintessential "picks and shovels" play in the AI gold rush, with a proven execution track record and a visibility horizon that is the envy of the industrial sector. The structural demand drivers—AI monetization, geographic expansion, and grid/power constraints—are powerful and long-dated.
However, the investment decision at this juncture is one of risk calibration. The stock is no longer a hidden gem; it is a widely held, richly valued leader. The compelling growth story is now balanced against a lofty valuation that discounts near-perfect execution and the emerging threat of deep-pocketed competitors.
For investors, the key is to align entry points with the defined support zones ($150, followed by the Fibonacci ladder down to ~$110) to improve the margin of safety. The $200 take-profit target offers a clear objective, but reaching it will depend less on hype and more on Vertiv's ability to continually demonstrate that it is not just riding a wave, but actively defining the infrastructure standards of the AI era. It remains a top-tier, high-beta vehicle for exposure to a transformative trend, but one that demands respect for both its potential and its present price. Long 
Long 
Long 
Vertiv Holdings (VRT) AnalysisCompany Overview: Vertiv Holdings NYSE:VRT is strategically positioned to capitalize on the increasing demand for data center infrastructure, with a particular focus on edge computing and the expanding 5G networks. As companies across various sectors accelerate their digital transformation, Vertiv's role in providing critical infrastructure solutions, including liquid cooling technology, is crucial for the operation and efficiency of modern data centers.
Key Catalysts:
Edge Computing & 5G Growth: The rise of edge computing and 5G networks increases the need for efficient, reliable data center infrastructure, a core competency for Vertiv.
Critical Infrastructure Expertise: Vertiv's leadership in liquid cooling and other essential data center technologies will be increasingly in demand as data centers evolve and expand.
Energy Consumption in Data Centers: With U.S. data centers projected to account for a growing share of electricity consumption, Vertiv’s infrastructure solutions—designed to enhance energy efficiency and optimize operations—are expected to become even more vital.
Digital Transformation: The ongoing shift toward cloud services, AI, and machine learning will fuel greater data center demand, benefitting Vertiv’s business model.
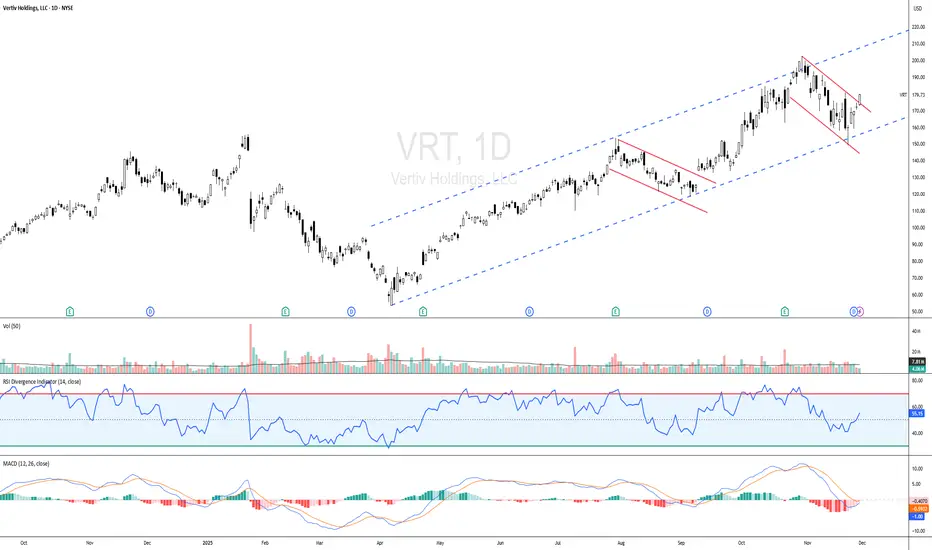
Investment Outlook: Bullish Outlook: We are bullish on VRT above $89.00-$91.00, driven by its market-leading solutions in data center infrastructure and strong growth potential. Upside Potential: Our target range for VRT is $140.00-$145.00, reflecting the company’s strategic position in critical growth sectors like 5G, edge computing, and data centers.
🚀 VRT—Leading Data Center Infrastructure into the Digital Future. #DataCenters #EdgeComputing #5G Long 
Vertiv Spikes 14.6% On Earnings Report Vertiv ( NYSE:VRT ) has ignited a market frenzy with its stellar earnings report, soaring 14.6% to unprecedented highs. While Vertiv ( NYSE:VRT ) isn't a direct player in the artificial intelligence (AI) sector, its pivotal role in providing critical infrastructure for data centers positions it at the forefront of the AI revolution.
With a staggering 79% surge in earnings and a remarkable 60% increase in organic orders, Vertiv's performance underscores the exponential growth in demand for data center solutions. This surge not only bodes well for Vertiv but also signals a broader trend in the AI market, benefiting tech giants like Nvidia (NVDA), Super Micro Computer (SMCI), and Broadcom (AVGO).
As AI applications continue to proliferate across industries, the need for robust data infrastructure becomes paramount. Vertiv's ascent reflects the indispensable role it plays in supporting the backbone of AI technology, positioning itself as an essential player in the digital transformation era.
Investors eyeing the AI sector should take note of Vertiv's meteoric rise, recognizing the symbiotic relationship between data center infrastructure and AI innovation. With Vertiv at the helm, the data center boom offers a compelling opportunity for growth-minded investors seeking exposure to the AI revolution.
Technical Outlook
Vertiv ( NYSE:VRT ) stock is up 14.36% trading above the 200-day Moving Average (MA) with a Relative Strength Index of 64 indicating bullish momentum and room for further growth. Long 
VRT a run up into earnings?VRT has been on a tear lately and they are expected to have good earnings. Vertiv Holdings, LLC Class A Common Stock is expected to report earnings on 02/21/2024. Not financial advice, DYOR...
This is the facts according to Zacks.com
Vertiv Holdings Co. (VRT) has been one of the most searched-for stocks on Zacks.com lately. So, you might want to look at some of the facts that could shape the stock's performance in the near term.
Shares of this company have returned +24.5% over the past month versus the Zacks S&P 500 composite's +6.5% change. The Zacks Computers - IT Services industry, to which Vertiv Holdings Co. belongs, has gained 11.9% over this period. Now the key question is: Where could the stock be headed in the near term?
While media releases or rumors about a substantial change in a company's business prospects usually make its stock 'trending' and lead to an immediate price change, there are always some fundamental facts that eventually dominate the buy-and-hold decision-making.
Earnings Estimate Revisions
Rather than focusing on anything else, we at Zacks prioritize evaluating the change in a company's earnings projection. This is because we believe the fair value for its stock is determined by the present value of its future stream of earnings.
Our analysis is essentially based on how sell-side analysts covering the stock are revising their earnings estimates to take the latest business trends into account. When earnings estimates for a company go up, the fair value for its stock goes up as well. And when a stock's fair value is higher than its current market price, investors tend to buy the stock, resulting in its price moving upward. Because of this, empirical studies indicate a strong correlation between trends in earnings estimate revisions and short-term stock price movements.
For the current quarter, Vertiv Holdings Co. is expected to post earnings of $0.53 per share, indicating a change of +89.3% from the year-ago quarter. The Zacks Consensus Estimate remained unchanged over the last 30 days.
For the current fiscal year, the consensus earnings estimate of $1.74 points to a change of +228.3% from the prior year. Over the last 30 days, this estimate has remained unchanged.
For the next fiscal year, the consensus earnings estimate of $2.22 indicates a change of +27.6% from what Vertiv Holdings Co. is expected to report a year ago. Over the past month, the estimate has remained unchanged. Long