Long
 Long
 Long
 Long
 Long
EHang: Commercial Takeoff Could Reignite the Bull CaseEHang remains the only publicly traded eVTOL (electric vertical takeoff and landing aircraft) manufacturer to have obtained all required Chinese certifications for its autonomous passenger-carrying EH216-S, while its operators have already obtained the first AOCs for commercial passenger flights. The market has largely priced in the weak Q1 results. A better-than-expected earnings report could serve as a strong upside catalyst amid renewed momentum in the eVTOL sector, with EH shares remaining deeply oversold.
EHang Holdings Ltd. Sponsored ADR Class A (EH)
Aerospace Industry
Entry price: $5.93
Target price: $8.55
Stop-loss: $4.20
Investment Thesis
EHang remains the only publicly traded manufacturer to have obtained all required Chinese certifications for its autonomous passenger-carrying EH216-S, while its operators have already obtained the first Air Operator Certificates (AOCs) for commercial passenger flights.
China has laid the groundwork for scaling its UAS ecosystem, including autonomous air taxi operations. In May, the Civil Aviation Administration of China (CAAC) issued training requirements for remote pilots operating large civil unmanned aircraft. Meanwhile, EHang and its partners already have more than 40 operational sites.
The key catalyst over the next two months is the transition from demonstration flights to revenue-generating commercial passenger operations, along with a reaffirmation of the company’s full-year revenue guidance of RMB 600 million.
Another positive factor is growing international validation of EHang’s business model. Following previously announced test flights in Abu Dhabi, the EH216-S completed the first autonomous passenger flight in Central Asia in Astana on August 10. Shortly before that, Kazakhstan introduced an initial regulatory framework covering eVTOL aircraft, vertiports, and UTM, a digital traffic-management framework for unmanned aircraft.
The market has already priced in a weak first quarter. Revenue came in at just RMB 25.7 million, with only four aircraft delivered, while the company reported a net loss of RMB 126.4 million. However, gross margin remained strong at 62.5%, liquidity stood at RMB 1.03 billion, and the company’s share buyback program of up to $30 million, equivalent to roughly 7% of its current market capitalization, could help limit further downside.
Moreover, a better-than-expected earnings report could serve as a powerful upside catalyst. The company has consistently beaten EPS expectations, while the broader eVTOL sector has recently gained momentum and EH shares remain deeply oversold.
From a technical perspective, the chart appears to be forming a gradual reversal pattern similar to the one seen in October 2022. At the same time, at 2.7x EV/Sales, EHang trades at an attractive valuation relative to its Western peers, providing further support for the bullish case.
The main risk is a further delay in large-scale commercialization, coupled with weak aircraft deliveries.  Long

Boeing deal changes everything: catching a long on $ACHRNYSE:ACHR
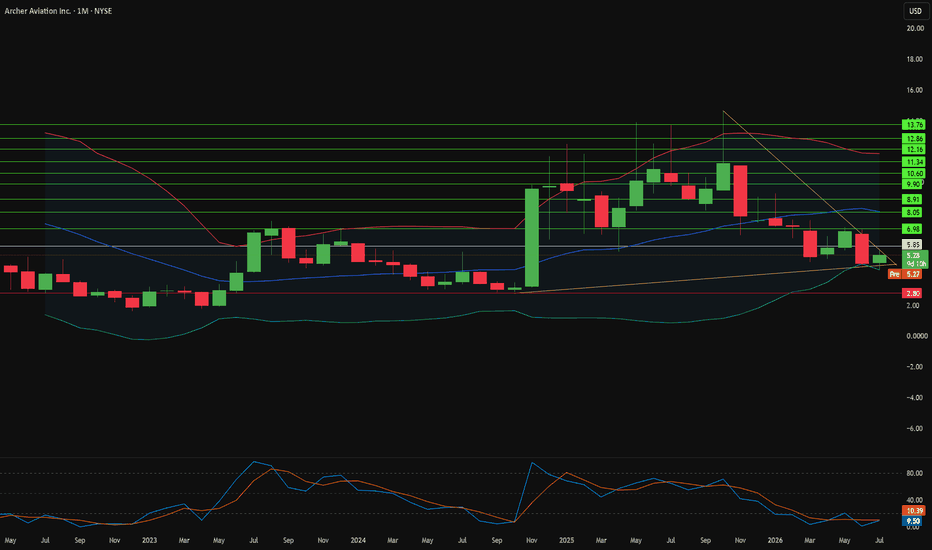
On the daily chart, conditions for opening a long position have formed. The main technical factor is the true breakout above the upper boundary of the long-term descending channel. Price exited it with a powerful impulse, met resistance at the MA200, and then turned into a correction from it. Now the asset is falling toward the gap fill zone. This decline is purely technical and is targeting the 5.47–5.60 range. This area represents a strong price confluence zone: full gap fill, liquidation of the price imbalance, the 50% Fibonacci retracement level, and the MA100.
The technical channel breakout is fully confirmed by the fundamental triggers of August 2026. The acquisition of Archer's Boeing Wisk Aero, Insitu, and SkyGrid divisions transforms the company into a significantly more diversified platform for the aerospace and defense industries, combining eVTOL, autonomous systems, drone technologies, and AI. Insitu adds more than $200 million in annual revenue, while Boeing receives a 19.75% stake in Archer and becomes a strategic partner. This significantly strengthens Archer's financial and technological base during its scaling and final FAA certification phase.
An important market marker is the nature of the volumes: the channel breakout occurred on abnormally high institutional volumes, with average volume rising to 52 million shares, while the current pullback is happening on sharply declining volumes, around 31 million shares. This indicates a reduction in seller pressure after the impulse breakout and allows us to view the current correction as a potential retest of the broken structure.
Position entry is planned with limit orders within the 5.47–5.60 zone. The first target is 8.80, and the medium-term target is 13.00.
The scenario loses relevance if price confidently returns back below the broken descending structure and loses the support zone.
This publication is for analytical purposes only and does not constitute individual investment advice. Share your thoughts in the comments and don't forget to support the idea with a like if you found the analysis useful!  Long

 Long

 Long
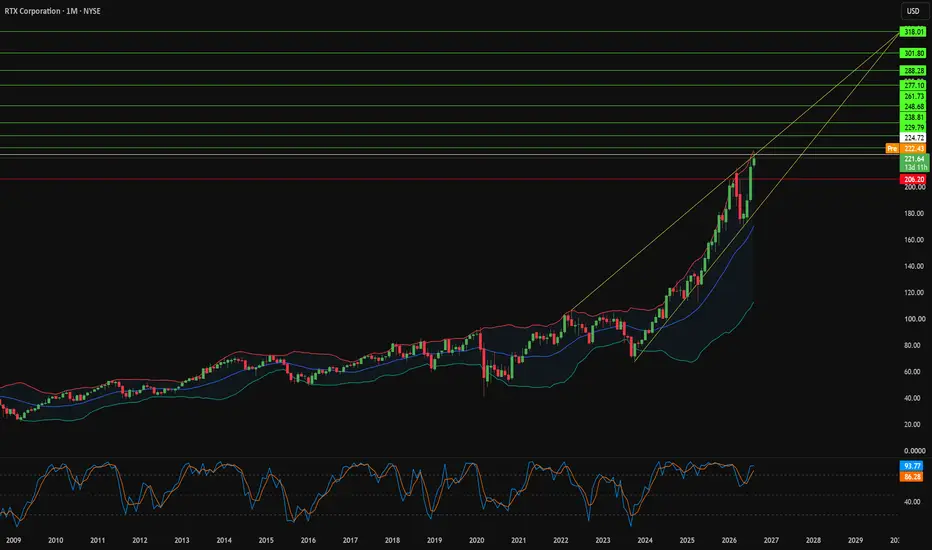
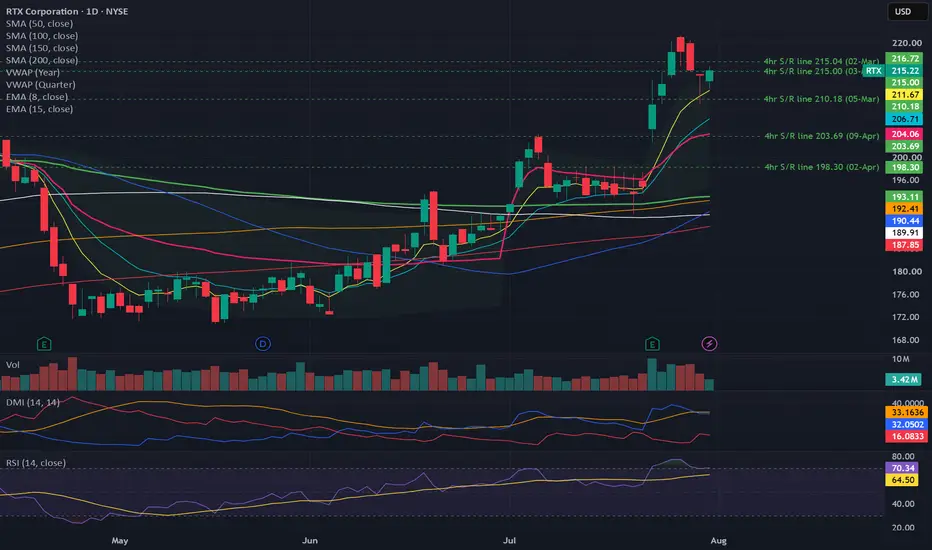
Why Is RTX Building 1,000 Tomahawks a Year?Raytheon Technologies is converting global rearmament into contracted revenue at remarkable speed. The U.S. Navy awarded the company a seven-year, $22.9 billion Tomahawk missile agreement that lifts annual output from under 100 units to more than 1,000. The Missile Defense Agency added $745 million for SM-3 Block IIA interceptors, and Raytheon committed $115 million to expand its Alabama integration facility by half. The Department of War also selected the company under its Arsenal of Freedom program, which hardens allied defense supply chains across coalition partners.
The commercial side runs equally hot. Pratt & Whitney logged over 800 Geared Turbofan orders and commitments early in 2026, pushing the commercial backlog past 8,000 engines across more than 90 airline customers. BOC Aviation alone ordered up to 220 GTF engines. On the military propulsion side, a $1.3 billion F135 sustainment contract funds spare parts and depot equipment across 42 airbases and 13 active ships. Collins Aerospace layered on a $472 million Chinook modernization award for open-architecture avionics.
Technology supplies the moat. Patented reduction gearing lets GTF fan blades spin slower and cuts aircraft fuel burn by twenty percent. The SPY-6 radar family uses standardized two-foot Radar Modular Assemblies, scaling across seven Navy ship classes from one shared patent architecture. In undersea autonomy, the all-carbon-fiber HADALUS platform traveled more than 2,000 nautical miles in trials at roughly one-third to one-fifth the cost of conventional long-endurance submersibles. Raytheon moved that program from sketch to sea demonstration in under 18 months.
Government cost-sharing rounds out the picture. Pratt & Whitney Canada partnered with Canadian authorities on a CAD $275 million modernization of its Longueuil plant, lowering capital outlay while insulating margins from inflation and rate pressure. Backlog visibility now extends across the next decade, spanning missiles, radar, propulsion, and autonomous systems. The question is no longer whether demand exists, but whether production capacity can keep pace with it.
 Long

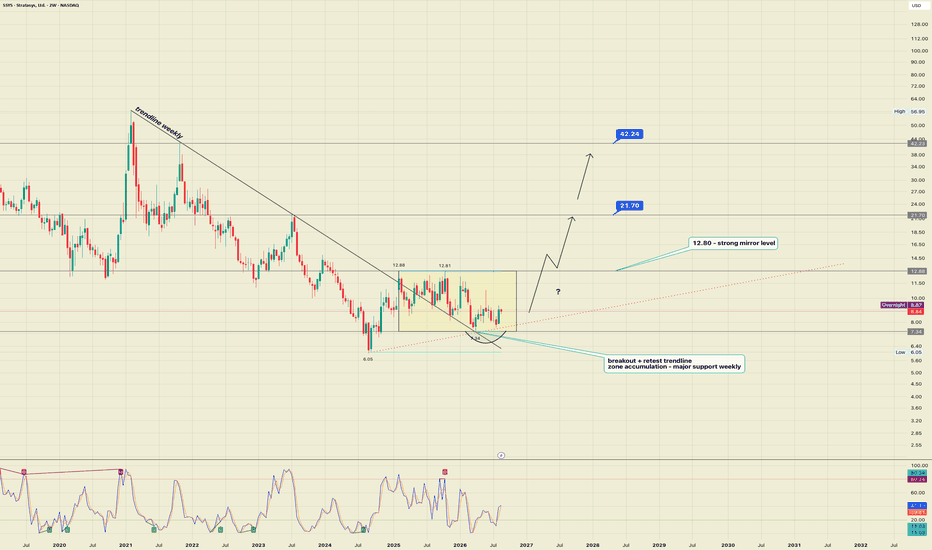
SSYS: Reversal base before the impulse?NASDAQ:SSYS
The key reversal factor is the confirmed breakout of the multi-year downtrend that had been containing the price since 2021. The asset has entered a deep accumulation phase. Rising local lows have formed a stable ascending diagonal support. The double bottom pattern with support at 7.34 indicates strong defense of positions by large capital. The current consolidation is a process of institutional parking of capital against the backdrop of a strong quarterly report that showed record sales of high-margin consumables.
The main trigger for launching the active distribution phase is the breakthrough of the strong horizontal mirror level at 12.80, which is currently acting as rigid resistance. Technical indicators confirm a long-term cycle change. Price is testing the 50-period moving average, and a confirmed hold above it historically opens the path to growth. The volume-weighted average price indicates the maximum concentration of traded volume within the current consolidation. The moving average convergence divergence has registered a bullish crossover on the two-week interval, signaling seller exhaustion.
The targets are fully justified. The first target at 21.70 is a zone of strong volume imbalance from past years and will attract price immediately after the range breakout. The second target at 42.24 is a global long-term objective. A safe tactic involves entering after a true breakout of the 12.80 level on its subsequent retest from above. A stop-loss should be placed below the absolute low of 7.34. In summary, the stock currently looks like a combination of a long technical base and potential fundamental catalysts. The reversal base is formed, where 12.80 is the main confirmation of the scenario. If buyers cannot break this level, the asset will remain in the range, and a loss of 7.34 would completely invalidate the idea.
P.S. The fundamental catalyst for the story is the announced acquisition of Markforged. On May 27, 2026, Stratasys announced an agreement to buy Markforged for $42.5 million in cash. The deal has not yet closed and is expected in the second half of 2026. The key value of the acquisition is the Continuous Carbon Fiber technology, which expands Stratasys’ capabilities in producing strong composite parts and strengthens the company’s position in aerospace, defense, automotive, and other industrial sectors. After the deal closes, Stratasys expects to achieve cost synergies and a positive contribution to adjusted EBITDA within the first year. Therefore, the fundamental thesis here is based not on Markforged being already fully integrated, but on the potential expansion of production capabilities and synergies after the deal closes.
This publication is for analytical purposes only and does not constitute individual investment advice. Technical levels are scenarios, not guarantees of price movement.  Long
 Long

 Long

 Long

XAR BREAKS TO A NEW ALL-TIME HIGH — Is Aerospace & Defense Start
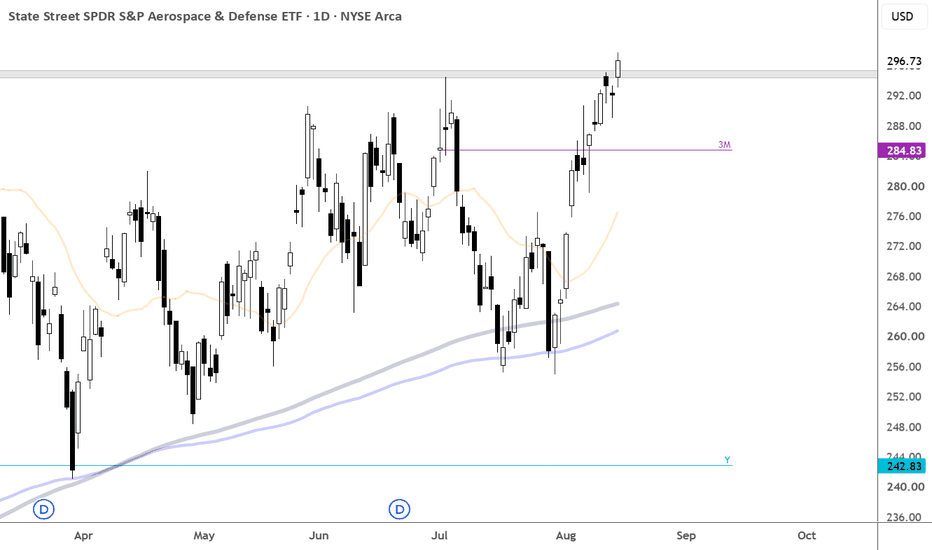
AMEX:XAR just closed at $296.73, after reaching $297.79, pushing through its previous all-time-high area.
But the ATH is only part of the story.
TECHNICAL PICTURE
On the weekly chart, XAR appears to have completed a large inverse Head & Shoulders formation.
The structure is interesting:
Left shoulder formed during the first part of 2026.
The deeper correction created the head.
Buyers stepped back in around the rising long-term trend.
The right shoulder held substantially above the major 2025 lows.
Price has now broken the ~$290–295 neckline / previous ATH zone.
That means two important technical events are happening together:
1. Breakout from a multi-month bullish reversal/continuation structure.
2. Breakout into price discovery above the previous ATH.
If the breakout holds, the chart opens potential upside zones around $320, $327 and eventually the $340–350 area based on the projection shown on the chart.
The level I would watch most closely now is not $320.
It is $290–295.
A successful retest of the old resistance as new support would make the breakout considerably more convincing. A weekly move back below that area would raise the possibility of a failed breakout.
FUNDAMENTALS ARE SUPPORTING THE CHART
XAR isn't a single defense contractor. It tracks a modified equal-weighted basket of U.S. aerospace and defense companies, which spreads exposure across the industry rather than allowing a few mega-cap names to dominate the ETF.
And the spending backdrop remains unusually strong.
At the 2025 Hague Summit, NATO members committed to moving toward 5% of GDP in defense and defense-related investment by 2035, including at least 3.5% for core defense requirements. European Allies and Canada had already increased combined defense expenditure by nearly 20% in real terms in 2025.
Meanwhile, S&P Global's 2026 aerospace & defense outlook describes strong commercial and defense demand, with suppliers increasing production to meet demand. It also points to the proposed U.S. 2027 defense budget of nearly $1.5 trillion, although the final enacted amount remains uncertain.
So this isn't simply a technical breakout occurring in isolation.
Price is breaking out while the industry's underlying demand cycle remains strong.
THE RISK
New ATH breakouts can also become crowded very quickly.
Supply-chain constraints remain an issue for aerospace manufacturers, higher production requires more capital, and future defense spending still depends on political and budget decisions.
So chasing a vertical move is very different from seeing the breakout confirmed.
For me, $290–295 is now the battlefield.
Above it → price discovery remains intact.
Below it → the breakout deserves another look.
What would you do here?
🟢 Buy the ATH breakout ?
🔵 Wait for a $290–295 retest ?
🔴 Too extended — stay away ?
I’m curious to see how traders are reading this one.
 Long
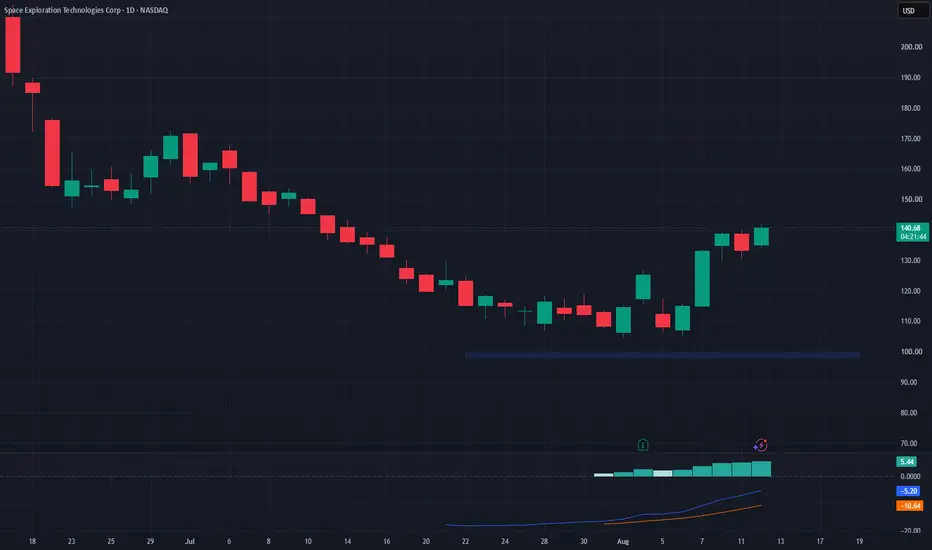
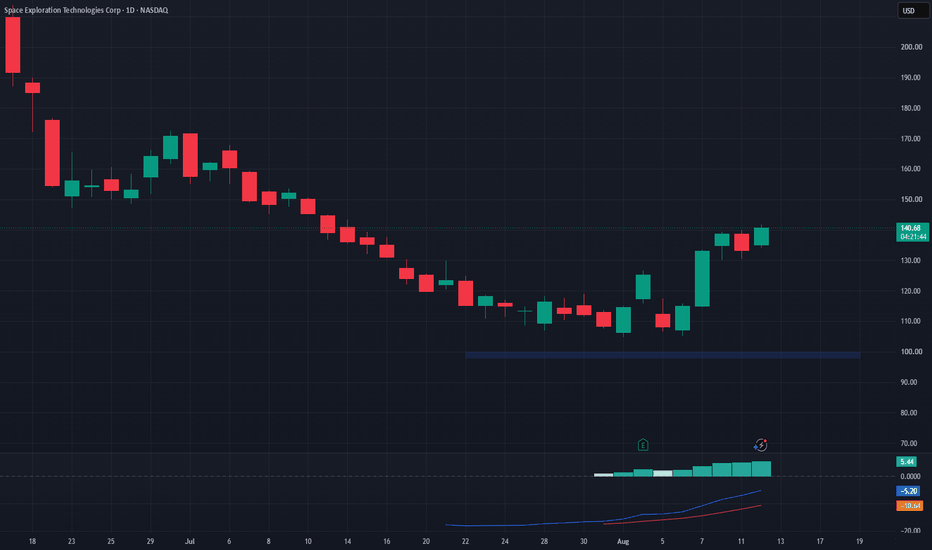
SPCX — Building a Full-Stack Space Infrastructure PlatformSpace Exploration Technologies Corp. NASDAQ:SPCX is a leading aerospace and space technology company focused on reusable launch systems, Starlink satellite connectivity, and the Starship platform.
Key Catalysts:
Reusable launch leadership:
SpaceX’s Falcon 9 platform has transformed launch economics through reusability, enabling higher launch frequency, lower costs, and a strong competitive position across commercial and government missions.
Starlink recurring-revenue engine:
Starlink provides SpaceX with a scalable subscription-based connectivity business, complementing its launch operations with recurring revenue as its satellite network and global customer base expand.
Starship represents the next growth phase:
Successful commercialization of Starship could significantly increase payload capacity and reduce launch costs, accelerating Starlink deployment while opening opportunities across defense, lunar missions, deep-space exploration, and orbital infrastructure.
Vertical integration advantage:
SpaceX combines rocket manufacturing, launch operations, satellite production, communications infrastructure, and reusable spacecraft, creating an integrated ecosystem that is difficult for competitors to replicate.
Defense & space infrastructure tailwinds:
Rising government spending on secure satellite communications, national security space systems, and resilient orbital infrastructure provides another potential long-term growth engine.
Investment Outlook:
Bullish above: $98.00–$100.00
Upside target: $200.00–$205.00
Supported by reusable launch leadership, Starlink’s recurring-revenue model, and Starship’s long-term potential, SpaceX represents a differentiated opportunity across connectivity, aerospace, and next-generation space infrastructure.
📢 SPCX — Combining reusable rockets, satellite connectivity, and next-generation spacecraft to build an integrated global space platform.  Long
 Long
Long 
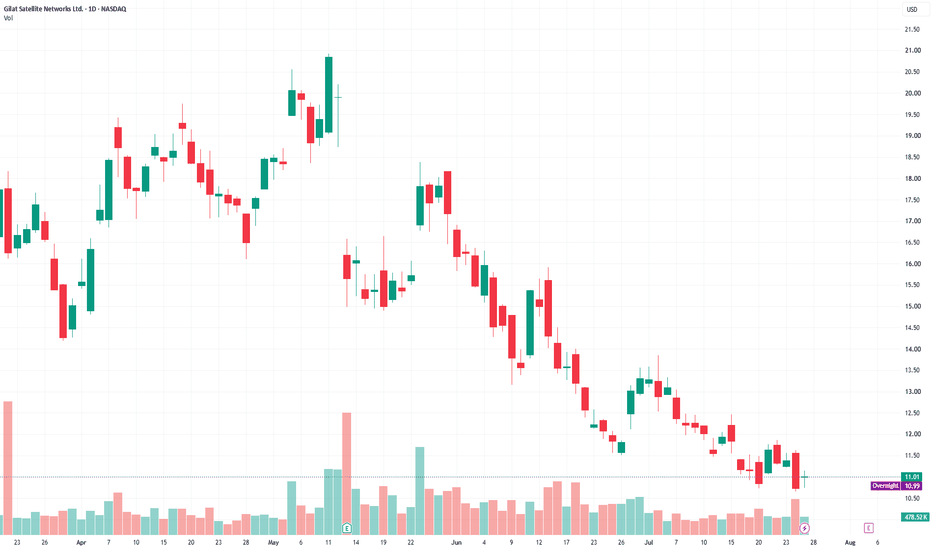
GILT: Expansion in AviationGILT: Expansion in Aviation and Defence Supports a Move Towards $15
Gilat is expanding its diversified satellite communications business, strengthening its presence in commercial aviation and defence while broadening its capabilities in multi-orbit networks. The acquisition of Stellar Blu has expanded the company’s presence in the markets for in-flight connectivity and electronically steered antennas. Meanwhile, the agreement to acquire most of Comtech’s satellite and space communications operations is expected to significantly expand Gilat’s defence business, broaden its technology portfolio and deepen its presence in the United States.
In our view, the growth of the business and the increasing contribution of commercial aviation and defence solutions to revenue and earnings support a further re-rating of the shares.
Gilat Satellite Networks Ltd. (GILT)
Sector: Aerospace & Defence
Curent price (July 27, 2026) : $10.87
Target price: $15
Stop-loss: $8.80
Investment Highlights
The main near-term catalyst is the release of second-quarter results on 5 August. In the first quarter, revenue increased by 20% to $110.5 million, while adjusted EBITDA nearly doubled to $15.1 million. Since the end of the quarter, Gilat has received $43 million in orders for Sidewinder terminals, $11 million in orders for US defence solutions and more than $20 million in orders for SkyEdge systems and services. These orders will not contribute to second-quarter revenue, but they improve revenue visibility and increase confidence in the company’s full-year guidance.
Another potential catalyst is the agreement to acquire most of Comtech’s satellite and space communications business for $157.5 million. The business to be acquired generated adjusted revenue of $195.2 million for the 12 months ended 31 January 2026. Following completion of the transaction, Gilat expects annual revenue to exceed $700 million, with defence revenue more than doubling.
The acquisition is expected to strengthen the company’s presence in the United States and expand its portfolio to include solutions for satellite ground infrastructure, space electronics and secure beyond-line-of-sight communications. The transaction is expected to close by the end of 2026, subject to the necessary regulatory approvals.
Conclusion: We expect GILT shares to reach $15 and maintain our Buy recommendation. We recommend a stop-loss level of $8.80.  Long
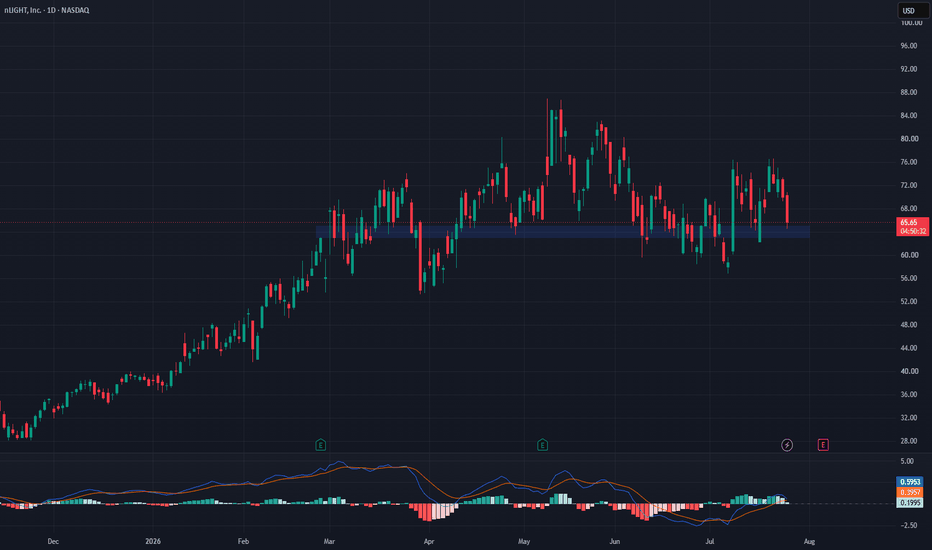
LASR — Powering the Next Generation of Defense Laser SystemsnLIGHT, Inc. NASDAQ:LASR develops high-power laser technologies for the defense, aerospace, industrial manufacturing, and precision sensing markets, with an increasing focus on advanced defense applications.
Key Catalysts:
Growing defense exposure:
nLIGHT has strategically shifted toward higher-value defense programs, benefiting from rising demand for directed-energy weapons, counter-drone systems, missile defense, and advanced sensing technologies.
Major defense program opportunity:
The company holds a position on the Joint Laser Weapon System (JLWS) program, which carries a potential contract value of up to $627 million, providing a significant long-term growth opportunity.
Strong backlog and revenue visibility:
An expanding defense backlog supports future revenue growth while increasing the company's exposure to long-term government and military contracts.
Vertically integrated U.S. manufacturing:
nLIGHT's U.S.-based vertically integrated manufacturing capabilities strengthen supply chain resilience, improve production efficiency, and provide a competitive advantage in defense markets.
Long-term defense modernization tailwinds:
Rising global defense spending and increased investment in laser-based weapons, precision targeting, and advanced sensing technologies continue to create favorable long-term demand for the company's solutions.
Investment Outlook:
Bullish above: $63.00–$65.00
Upside target: $115.00–$120.00
Supported by growing defense programs, a strong contract pipeline, vertically integrated manufacturing, and increasing demand for directed-energy technologies, nLIGHT is well positioned for long-term growth in the defense sector.
📢 LASR — Positioned to benefit from the growing adoption of advanced laser technologies across modern defense systems.  Long
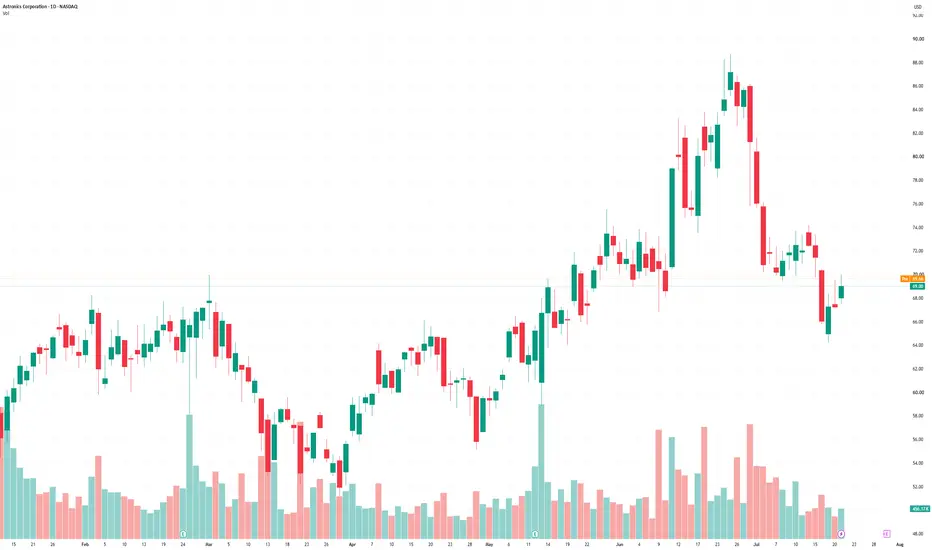
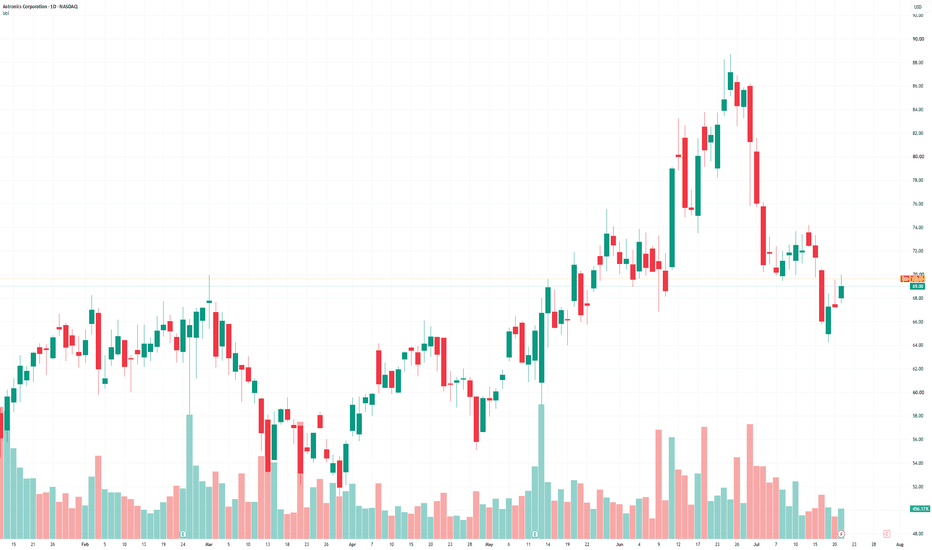
ATRO: Pullback Creates an Attractive Entry Ahead of Q2 EarningsAstronics Corporation (NASDAQ: ATRO)
Industry: Aerospace and Defense
Astronics has completed its recovery cycle and entered a phase of structural growth. We expect Astronics shares to recover over the next two months. Meanwhile, the recent pullback in its share price has created an attractive entry point ahead of the second-quarter earnings release.
Management raised its 2026 revenue guidance to $970 million–$1 billion, while first-quarter revenue growth of 12% year over year and an adjusted EBITDA margin of 16.4% demonstrate the scalability of the company’s business model.
Ticker: #ATRO
Price at the time of analysis: $68.38
Target price: $81.00
Stop-loss: $60.00
Investment Highlights
Strong foundation for reaffirming full-year guidance
For the second quarter, Astronics expects record revenue of $245–250 million, representing year-over-year growth of approximately 20–22%.
Confidence in this outlook is supported by record quarterly orders of $290 million, a book-to-bill ratio of 1.26, a backlog of $734 million, and sustained demand in the Commercial Transport market.
A result near the upper end of the quarterly guidance range would strengthen the case for the company to reaffirm its 2026 outlook and could lead to upward revisions to consensus estimates.
Military test program entering full-rate production
A $44.7 million U.S. Army order marks the start of full-rate production of the TS-4549/T radio test sets, with initial deliveries scheduled for August.
Approximately $145 million in potential contract value remains available under the IDIQ agreement. Higher production volumes and improved capacity utilization should support the recovery of the Test Systems segment, whose operating margin improved to 2.4% from negative 15.3% a year earlier.
Aerospace growth and operating leverage
Aerospace segment revenue increased by 11.7%, supported by an almost threefold increase in Seat Motion revenue and 16.2% growth in Flight Critical Electrical Power.
The acquisition of Bühler strengthens Astronics’ position in aircraft seat-control systems, while Envoy expands the company’s engineering capabilities and expertise in FAA certification for aircraft modifications.
Conclusion: we expect ATRO shares to rise to $81 and assign the stock a Buy rating. We recommend setting a stop-loss at $60.
 Long
Can One Defense Deal Rewrite Archer Aviation's Future?Archer Aviation (NYSE: ACHR) is repositioning itself from a pure-play air-taxi manufacturer into a dual-use aerospace ecosystem, teaming with defense technology firm Anduril Industries to unveil "Thunder," an autonomous Group 5 attack rotorcraft built on the same hybrid-electric architecture as Archer's civilian aircraft. Investors reacted enthusiastically: shares jumped nearly 20% following the announcement at the Farnborough International Airshow, even though the stock remains down sharply for the year. The defense variant can carry heavy weapons payloads, including Hellfire missiles, and fits inside a standard shipping container for rapid field deployment; critically, it bypasses the multi-year FAA passenger-certification process weighing on Archer's commercial timeline.
The financial backdrop explains why that shortcut matters so much. In Q1 2026, Archer generated just $1.6 million in revenue, up from $0.3 million the prior quarter and ahead of the roughly $0.9 million analysts had expected, while net loss widened to $217.7 million as R&D and certification spending accelerated. Adjusted EBITDA loss came in at $172.5 million, within management's guidance range, and the company still holds about $1.8 billion in liquidity, implying a runway of roughly two and a half years at the current burn rate. The Anduril partnership offers a faster, non-FAA revenue channel that could start contributing well before Archer's flagship air taxi, Midnight, reaches full commercial service.
Beyond defense, Archer is building several other growth levers. The company unveiled its own aviation-specific AI model, "Zee," designed to run offline onboard the aircraft and eventually be licensed to airlines. It also launched a charging-infrastructure consortium, ACES, with BETA Technologies and Macquarie Capital, targeting 250 sites by 2030 a strategy management explicitly models on Tesla's early Supercharger rollout. On the regulatory front, Archer became the first eVTOL company to close FAA Phase 3 type certification and secured a streamlined path in the UAE for early commercial Midnight flights.
Taken together, Archer's pitch has shifted from "when will passenger air taxis fly" to "how many revenue streams can this platform generate before that happens." Whether Thunder, Zee, and ACES can close a $217 million quarterly loss is the bet investors are now pricing in. Long