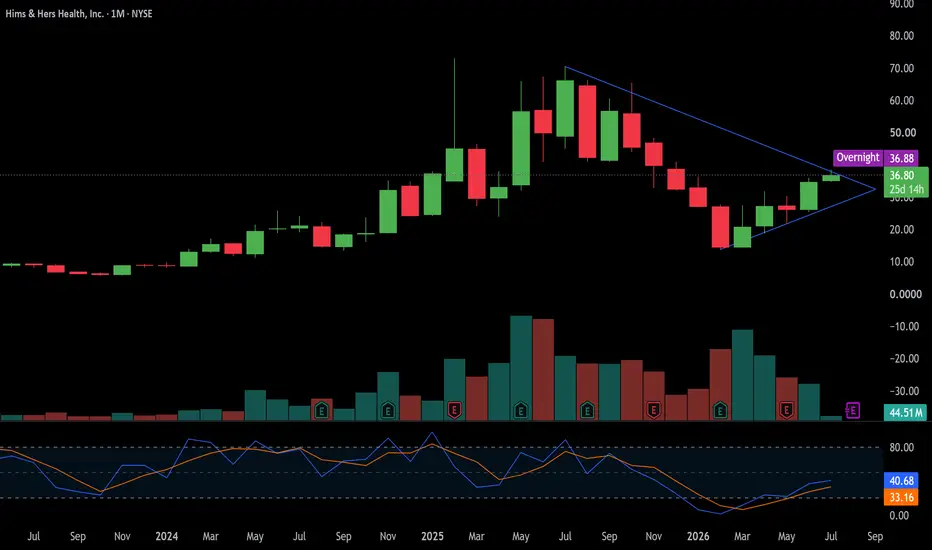
Is Hims & Hers Disrupting Medicine or Chasing a Bubble?Hims & Hers Health sits at the intersection of consumer technology and clinical care. The stock recently hit fresh 2026 highs. Canaccord Genuity boosted its price target to $40. Meanwhile, a massive $400 million JPMorgan facility unlocks unparalleled corporate liquidity. This digital platform faces both immense market enthusiasm and deep regulatory scrutiny.
Telehealth Borders and Geostrategy
Telehealth borders are expanding beyond domestic markets. The company actively diversifies its geographic footprint. For instance, international segments anchor recent top-line acceleration. This footprint balances the risk of localized regulatory gridlock. Global expansion insulates the enterprise against localized economic disruptions.
Macroeconomics and Capital Flexibility
High inflation and shifting credit landscapes test consumer retail spending power. Despite these headwinds, Hims & Hers exhibits strong consumer credit card data. The platform raised its full-year 2026 revenue guidance up to $3 billion. A resilient subscription model drives predictable cash flows during volatile periods.
Evolving Industry Trends and Business Models
Consumer behavior demands frictionless, on-demand medical access. Hims & Hers transforms the traditional patient journey into a digital experience. The platform shifts users away from physical waiting rooms. It capitalizes on high-margin, recurring software subscriptions. Partnerships with giants like Novo Nordisk expand the branded product shelf.
Corporate Vision, Culture, and Leadership
CEO Andrew Dudum embraces a bold corporate vision. He routinely shrugs off wild stock market swings. Dudum focuses the executive team on building a permanent healthcare institution. Leadership aggressively prioritizes capital flexibility to expand market share. This steady approach provides crucial confidence to institutional equity investors.
Driving Internal Innovation
The corporate culture rewards relentless operational agility and strategic pivots. Hims & Hers rapidly expanded its weight-loss catalog to capture consumer demand. Teams continuously launch novel wellness verticals. This culture of speed transforms theoretical concepts into profitable revenue lines.
High-Tech and Wearable Integration
The platform builds toward a comprehensive, full-stack AI healthcare matrix. The company plans imminent data integrations with advanced wearables like the Oura Ring. These high-tech diagnostic loops track personalized biometric signals over time. Consequently, the system creates an automated feedback loop for every subscriber.
Cybersecurity and Risk Management
Managing sensitive personal health information creates profound cyber risks. Data breaches can instantly destroy consumer trust and trigger massive penalties. Therefore, the company maintains rigorous digital defenses and secure databases. Advanced cybersecurity architecture shields vital patient data from global hackers.
Science and the Pharmaceutical Supply Chain
The legacy pharmaceutical supply chain remains rigid and expensive. Hims & Hers bypasses traditional bottlenecks by utilizing specialized compounding pharmacies. This scientific approach allows the platform to formulate customized, accessible treatments. The company successfully serves large, historically neglected consumer cohorts at scale.
Patent Analysis and Regulatory Catalysts
An upcoming July 2026 FDA advisory committee meeting could reshape the market. Regulators will evaluate easing restrictions on several prominent research peptides. FDA staff briefing documents released ahead of the meeting already recommend against several of these substances, citing insufficient human safety and efficacy evidence, though the committee’s recommendation is non-binding. Hims & Hers actively prepares for this potential commercial opportunity. The company acquired specialized peptide manufacturing facilities last year. A robust intellectual property moat protects these compounding methodologies from replication.
Strategic Outlook
Hims & Hers Health combines technological agility with financial discipline. It forces legacy healthcare providers to adapt or fail. The company skillfully balances severe regulatory risks against immense market demand. Winners in this space must innovate continuously. Hims & Hers proves it has the capital and vision to dominate.  Long

The $30 Stock Wall Street Values at $93?Viking Therapeutics (VKTX) finds itself at a dramatic crossroads in 2026, a clinical-stage biopharmaceutical company whose shares trade near $30 while analysts assign a fair value of $92.72, implying a staggering 67.6% undervaluation. The company posted a Q1 2026 net loss of $158.3 million, largely fueled by $150.2 million in R&D expenditures as it aggressively advances its lead asset, VK2735, through pivotal Phase 3 VANQUISH trials targeting obesity and type 2 diabetes. Despite zero product revenue, Viking holds $603 million in cash reserves, enough, management projects, to fund operations into 2028. With 17 of 18 Wall Street analysts rating the stock a "Buy" and a consensus 12-month price target of $95.50, institutional conviction remains remarkably strong even as short sellers maintain a 21% short interest, underscoring the profound polarization around the stock.
The scientific and commercial opportunity Viking is chasing is enormous. The global GLP-1 obesity market, valued at $8.21 billion in 2025, is projected to reach $66.57 billion by 2035, growing at a 23.28% CAGR. VK2735, a dual GIP/GLP-1 receptor agonist, demonstrated up to 14.7% mean body weight reduction in Phase 2, with 93% of treated patients achieving at least 5% weight loss results that rival the best-in-class benchmarks set by Eli Lilly's Tirzepatide. Perhaps most strategically significant is Viking's oral tablet formulation, which showed 12.2% weight reduction over 13 weeks in Phase 2, with Phase 3 initiation targeted for Q4 2026. An effective oral GLP-1 therapy would be a game-changer in patient compliance and direct-to-consumer telehealth channels.
Yet the path to commercialization is laden with serious structural risks. Geopolitical trade wars, including 100% pharmaceutical import tariffs and the BIOSECURE Act, severing Chinese supply chains, threaten the active ingredient pipelines essential to GLP-1 manufacturing. Cybersecurity threats targeting clinical research organizations have intensified dramatically, with destructive data-wiping attacks and large-scale ransomware incidents compromising millions of healthcare records in early 2026 alone. Competitive pressure from Novo Nordisk and Eli Lilly, whose pipelines continue advancing, could narrow the market window Viking needs.
Ultimately, Viking Therapeutics is best understood as a binary high-conviction bet: an exceptionally well-validated drug pipeline in one of the fastest-growing pharmaceutical categories on earth, encased in the fragility of a pre-revenue company burning cash toward a 2027 data readout. The appointment of a Chief Commercial Officer with Amgen and Eli Lilly pedigree signals the company is actively positioning for either a commercial launch or an acquisition, likely the more probable exit given industry giants like Pfizer and AbbVie are desperately seeking obesity market entry. Whether Viking becomes the next blockbuster or gets absorbed into a pharma giant, its role in reshaping the obesity treatment landscape appears assured.
 Long

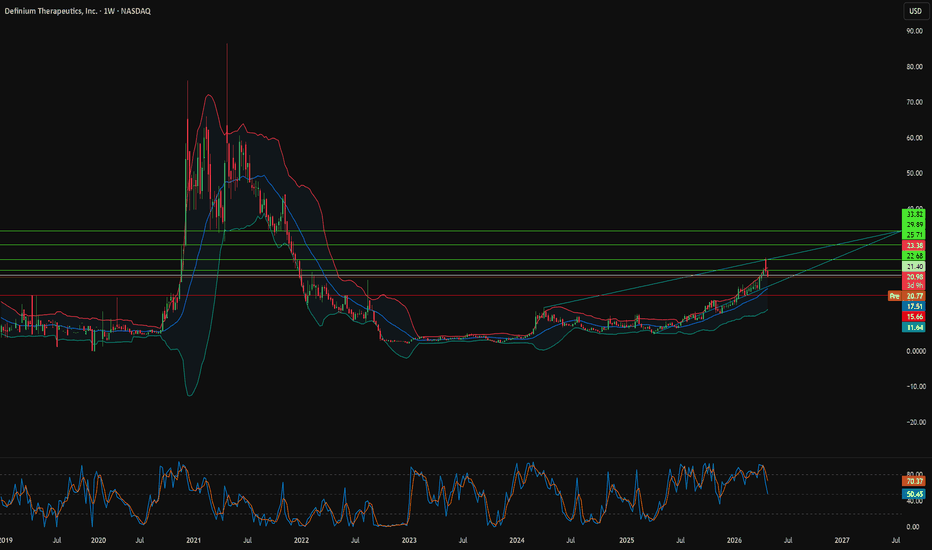
Can a Forgotten Molecule Fix the Mental Health Crisis?Definium Therapeutics (DFTX), formerly Mind Medicine, rebranded in January 2026, has emerged as the leading clinical-stage company in psychedelic-assisted psychiatry, built on a focused pipeline of optimized lysergide formulations targeting generational-scale unmet needs. Its flagship asset, DT120 ODT, is a pharmaceutical-grade, orally disintegrating lysergide tartrate tablet developed using Zydis fast-dissolve technology, which improves tolerability and eliminates the logistical burdens of traditional psychedelic delivery. The science centers on serotonin-2A receptor agonism, which produces transient but profound neuroplastic shifts hypothesized to disrupt the entrenched neural patterns underlying major depressive disorder (MDD), generalized anxiety disorder (GAD), and PTSD. Four pivotal Phase 3 trials, EMERGE, ASCEND, VOYAGE, and PANORAMA, are advancing concurrently, with three topline readouts expected before year-end 2026, each representing a binary catalyst for the company's valuation.
Despite a hostile macroeconomic backdrop including oil above $118 per barrel, elevated Fed rates, and a broadly frozen biotech funding environment, Definium entered 2026 in a position of unusual financial resilience. The company raised $259 million in equity financing during late 2025 and reported total cash and investments of $411.6 million, providing a funded runway through 2028 that insulates it from the capital constraints suffocating smaller peers. On the regulatory front, the April 2026 White House Executive Order to accelerate psychedelic drug development provided historic federal validation for the sector, mandating cross-agency collaboration, priority review pathways, and swift DEA rescheduling upon FDA approval. This political tailwind, combined with Definium's rigorous clinical infrastructure, positions the company as the primary beneficiary of what amounts to an unprecedented policy opening.
Commercially, Definium is engineering DT120 to fit within existing interventional psychiatry infrastructure rather than requiring a wholesale overhaul of the care system. By eliminating mandatory psychotherapy sessions, management targets a streamlined five-to-eight-hour supervised dosing window per treatment, modeled closely after the Spravato (esketamine) reimbursement framework already accepted by Medicare, Medicaid, and commercial payers at approval rates exceeding 85%. Projected annual treatment costs of $28,000–$70,000 per patient, combined with analyst consensus revenue estimates of $206.9 million by 2029, illustrate the scale of the commercial opportunity, though the wide divergence between bullish and bearish revenue estimates reflects the binary nature of late-stage clinical risk. Layered over this is a robust intellectual property moat extending into the early-to-mid 2040s, supplemented by five years of regulatory exclusivity upon approval, giving Definium a formidable barrier against generic competition should its Phase 3 program succeed.
 Long
 Long

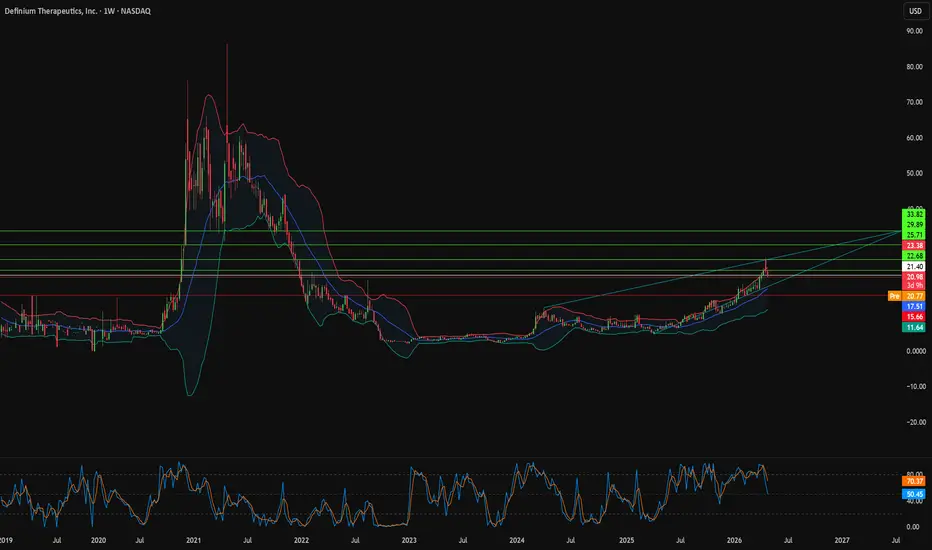
Why Definium Therapeutics Inc. $DFTX Looks Poised for a BreakoutThis chart shows a classic long-term base > trend reversal > momentum expansion setup.
NASDAQ:DFTX
1. Multi-year base = structural reset
After the 2021 blow-off top and full capitulation, Definium Therapeutics Inc. spent nearly 2+ years building a flat, low-volatility base in the $2–$6 range. That kind of time compression typically resets shareholder structure and washes out weak hands. Long bases matter because they often precede outsized directional moves.
2. Higher lows + rising moving averages
Price is now making consistently higher lows, and the 50-day MA has crossed above the 200-day MA (golden cross). More importantly, price is holding above both averages. That signals a transition from accumulation to a new primary uptrend, not just a dead-cat bounce.
3. Volume confirms institutional interest
The recent advance is accompanied by expanding volume, not declining volume. That’s critical. Breakouts that fail usually do so on weak participation. Here, volume is increasing as price moves higher, suggesting real demand, not retail chasing.
4. Momentum expansion (MACD)
MACD is turning positive and accelerating, which aligns with the price trend rather than diverging from it. This tells you momentum is supporting continuation, not exhaustion.
5. Overhead resistance is thin
Once price cleared the ~$10–$12 zone, it entered an area with little historical resistance until much higher levels. Markets tend to move faster when there’s less prior supply overhead.
6. Relative strength
The relative performance vs. the broader market (shown at the top) is sharply rising. That means this isn’t just a market beta move — DFTX is outperforming, which is what strong breakouts do.
---
There’s a lot of tension in the article around “pharma gatekeeping” vs grassroots access to natural mushrooms. But if you strip away the politics and look at what actually came out of this, it reinforces something we’ve seen over and over. When states get serious, they default to hospital-based, physician-led, FDA-aligned models.
NJ Psilocybin Legislation Exposes Conflicts Between Advocates for Different Therapeutic Models
---
Definium Therapeutics stock price target raised to $36 from $20 at RBC Capital NASDAQ:DFTX
---
Definium Therapeutics Sets 2026 Milestones: Three Phase 3 Trial Readouts Poised to Transform Psychiatric Care
Key Developments: DFTX is Targeting Data-Driven Breakthroughs in Mental Health
Definium Therapeutics (NASDAQ:DFTX), formerly Mind Medicine (MindMed), has sharpened its focus and reemerged with a mission: deliver transformative psychiatric treatments anchored in rigorous clinical evidence. With three Phase 3 trial readouts scheduled for 2026—including the highly anticipated Voyage study of DT120 ODT (orally dissolving tablet) for generalized anxiety disorder (GAD)—investors and clinicians alike are taking notice as DFTX aims to reshape the standard of care for anxiety and depression.
Clinical Pipeline: Multiple Late-Stage Trials Set for Results in 2026
DFTX’s late-stage pipeline features four ongoing Phase 3 trials evaluating DT120 ODT, a candidate that has already received FDA Breakthrough Therapy Designation for its novel approach in GAD. The company plans to deliver data across two of the largest psychiatric indications, affecting over 50 million people in the United States alone. Highlights for 2026 include:
Trial Name Indication Expected Milestone
Voyage Generalized Anxiety Disorder (GAD) Phase 3 Topline Data (Q2 2026)
Panorama GAD Topline Data (H2 2026)
Emerge Major Depressive Disorder (MDD) Topline Data (Mid-2026)
Ascend MDD Initiation (Mid-2026)
Long 
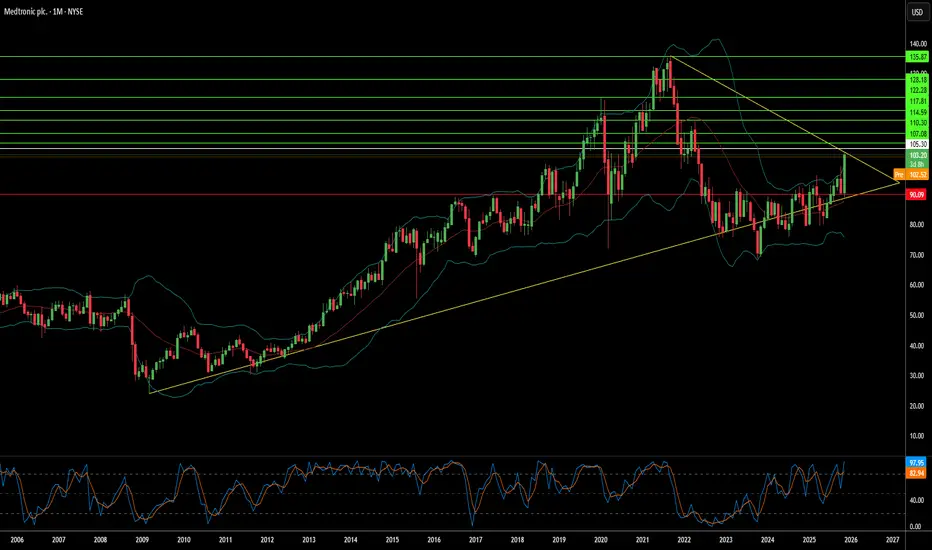
Can a Medical Giant Transform Into a Growth Story?Medtronic has demonstrated significant momentum entering 2026, with its recent 23% share price appreciation reflecting fundamental improvements rather than speculative enthusiasm. The company delivered strong fiscal Q2 2026 results with revenue reaching approximately $9 billion, up 6.6% year-over-year, while adjusted earnings per share rose 8% to $1.36, surpassing both internal projections and analyst expectations. Most notably, cardiovascular revenue surged 10.8% to roughly $3.4 billion, marking the strongest growth in over a decade outside pandemic periods and suggesting sustainable acceleration across its core business.
The company's pulsed-field ablation technology has emerged as a transformative growth driver, with the PulseSelect system achieving FDA clearance as the first PFA platform for treating atrial fibrillation. This innovation propelled a 71% revenue surge in Cardiac Ablation Solutions during Q2, including 128% growth in the United States. Beyond cardiology, Medtronic's Hugo robotic-assisted surgery system represents a strategic initiative to penetrate the underdeveloped surgical robotics market. The system has recently been submitted for FDA clearance following successful urologic trials, achieving a 98.5% success rate. These technological advances position Medtronic across multiple high-growth segments, including neuromodulation, renal denervation, and diabetes management.
From an investment perspective, Medtronic offers a compelling combination of quality, income, and growth potential. The company has raised its dividend for 48 consecutive years, maintaining Dividend Aristocrat status with a current yield in the low-3% range above the S&P 500 average while preserving capital for R&D investment and strategic acquisitions. Management has demonstrated improved execution with consistent guidance raises, and balanced capital allocation between shareholder returns and innovation funding. While risks remain around robotics execution, diabetes strategy decisions, and payer negotiations, the fundamental thesis appears intact for long-term investors seeking defensive growth with rising cash flows and exposure to structural healthcare trends driven by aging demographics and minimally invasive procedure adoption.  Long

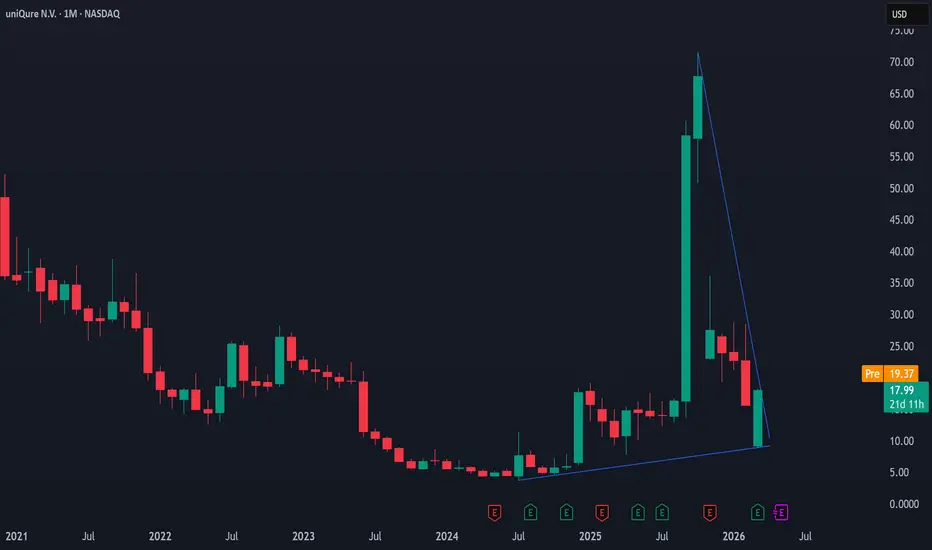
When Does Progress Move Backward?UniQure N.V. experienced a catastrophic 75% stock plunge in November 2025 following an unexpected FDA reversal on its Huntington's disease gene therapy, AMT-130. Despite having received Breakthrough Therapy Designation and Regenerative Medicine Advanced Therapy designation, the company learned during a pre-BLA meeting that the FDA now considers its Phase I/II data, which relied on external controls from the Enroll-HD natural history database, insufficient for approval. This contradicted prior regulatory guidance and forced UniQure to abandon its planned Q1 2026 submission, immediately destroying billions in market capitalization and rendering near-term revenue projections obsolete.
The regulatory reversal reflects broader instability within the FDA's Center for Biologics Evaluation and Research (CBER), where leadership turnover and philosophical shifts have created systemic uncertainty across the gene therapy sector. New CBER leadership, particularly Director Vinay Prasad, favors traditional evidence standards over accelerated pathways that rely on surrogate endpoints or external controls. This policy hardening invalidates development strategies that biotechnology companies had pursued based on previous regulatory assurances, demonstrating that breakthrough designations no longer guarantee acceptance of innovative trial designs.
The financial consequences extend beyond UniQure's immediate valuation collapse. Every year of regulatory delay erodes patent exclusivity. AMT-130's patents expire in 2035, directly destroying net present value. Analysis suggests that a three-year delay could render 33-66% of rare disease therapies unprofitable, and UniQure now faces the prospect of funding expensive randomized controlled trials while operating with negative profit margins and declining revenues. The company's only viable hedges involve pursuing approval through European regulators (EMA) or the UK's MHRA, where regulatory philosophies may prove more accommodating.
This case serves as a critical warning for the entire gene therapy sector: accelerated approval pathways are contracting, single-arm trials using external controls face heightened scrutiny, and prior regulatory agreements carry diminishing reliability. Investors must now price significantly higher regulatory risk premiums into biotech valuations, particularly for companies dependent on single assets and novel trial methodologies. The UniQure experience confirms that in biotechnology investment, regulatory predictability, not just scientific innovation, determines commercial viability. Short 
A

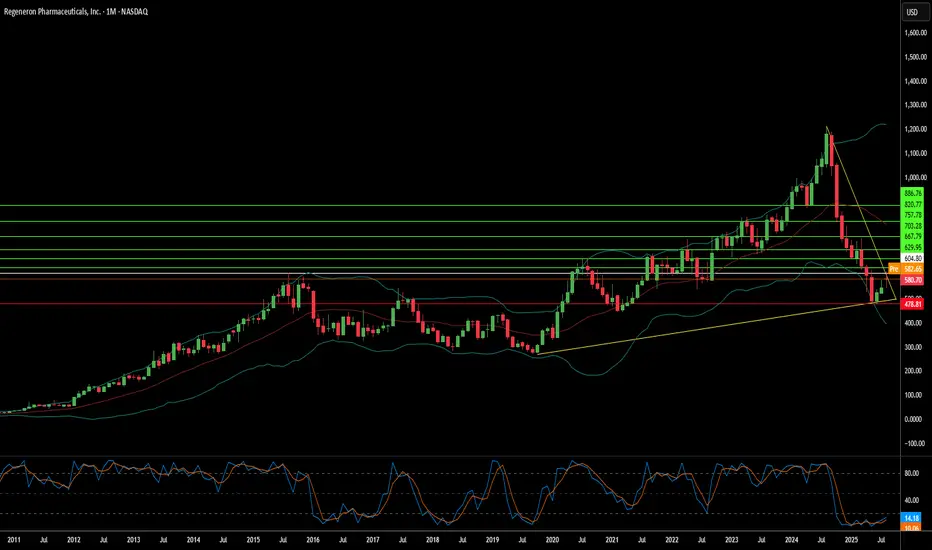
Can Innovation Survive Manufacturing Chaos?Regeneron Pharmaceuticals stands at a fascinating crossroads, embodying the paradox of modern biotechnology: extraordinary scientific achievement shadowed by operational vulnerability. The company has successfully transformed from a blockbuster-dependent enterprise into a diversified biopharmaceutical powerhouse, driven by two key engines. Dupixent continues its remarkable ascent, achieving 22% growth and reaching $4.34 billion in Q2 2025. Meanwhile, the strategic transition from legacy Eylea to the superior Eylea HD demonstrates forward-thinking market positioning, despite apparent revenue declines.
The company's innovation engine supports its aggressive R&D strategy, investing 36.1% of revenue, nearly double the industry average, into discovery and development. This approach has yielded tangible results, with Lynozyfic's FDA approval marking Regeneron's first breakthrough in blood cancer, achieving a competitive 70% response rate in multiple myeloma. The proprietary VelociSuite technology platform, particularly VelocImmune and Veloci-Bi, creates a sustainable competitive moat that competitors cannot easily replicate, enabling the consistent generation of fully human antibodies and differentiated bispecific therapies.
However, Regeneron's scientific triumphs are increasingly threatened by third-party manufacturing dependencies that have created critical vulnerabilities. The FDA's second rejection of odronextamab, despite strong European approval and compelling clinical data, is due to manufacturing issues at an external facility, rather than scientific deficiencies. This same third-party bottleneck has delayed crucial Eylea HD enhancements, potentially allowing competitors to gain market share during a pivotal transition period.
The broader strategic landscape presents both opportunities and risks that extend beyond manufacturing concerns. Although the company's strong victories in intellectual property cases against Amgen and Samsung Bioepis showcase effective legal defenses, the proposed 200% drug tariffs and industry-wide cybersecurity breaches, such as the Cencora incident impacting 27 pharmaceutical companies, highlight significant systemic vulnerabilities. Regeneron's fundamental strengths-its technological platforms, diverse pipeline spanning oncology to rare diseases, and proven ability to commercialize breakthrough therapies-position it for long-term success, provided it can resolve the operational dependencies that threaten to derail its scientific achievements.  Long

 Short
 Short

 Long

 Long

 Long

 Long

 Long

 Long