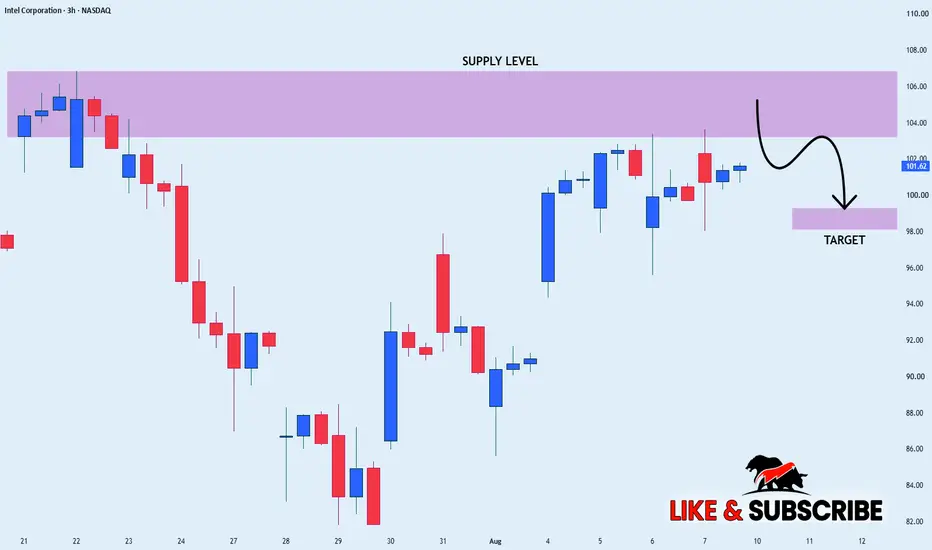
Short

Long 
Intel Corporation ($INTC) - Potential Squeeze After Rate CutIntel Corporation ( NASDAQ:INTC ) is setting up for an exciting squeeze potential following an anticipated rate cut. Here's why the technical landscape could be shaping up for a big move:
Fibonacci Support Holding Strong
The stock is currently holding well above the 0.786 Fibonacci retracement level, which is a critical area of support. Historically, holding this level is a strong indicator that a reversal could be imminent. A rate cut would provide a fundamental catalyst to accelerate a recovery from this level, as lower borrowing costs typically improve market sentiment, especially for large-cap tech stocks like Intel.
Worst-Case Scenario: Testing $13–$14 Support
While we are optimistic about the current setup, the worst-case scenario to watch for is a potential retest of the $13–$14 range. This level marks a significant historical support zone and, if touched, could provide a final flush-out of weak hands before the stock rebounds. Should this happen, it would likely signal a capitulation event, paving the way for long-term bulls to step back in at attractive prices.
Squeeze Potential and Rebound Targets
If Intel holds its current Fibonacci support, we could be setting up for a short squeeze driven by fresh liquidity entering the market post-rate cut. With technical and fundamental catalysts aligning, the stock has potential to rally toward the $40+ level over the medium term. This would mark a massive rebound, and a retest of previous highs would not be out of the question.
Key Levels to Watch
Immediate Support: 0.786 Fib level
Worst-Case Support: $13–$14
Upside Target: $40+ Long 
Long 
Intel’s Rally May Be Over: Why INTC Could Fall Toward $43Intel’s powerful rally may have reached a major turning point.
After advancing from around $17.65 to a high of $142.42, Intel (INTC) has already delivered an extraordinary move. However, the structure on the daily chart now suggests that the advance may have completed, opening the door to a much deeper correction.
--
The Bigger Picture
The rally from the 2025 low around $17.65 can be interpreted as a developing five-wave impulsive structure.
Several corrective phases along the way were followed by renewed upside momentum, eventually pushing Intel above $100 and toward the $142.42 high. From an Elliott Wave perspective, this move appears to have completed the final wave of the larger advance.
That makes the recent rejection particularly important.
Rather than viewing the decline as simply another short-term pullback, the current structure raises the possibility that Intel has entered a much larger corrective phase.
--
The Current Setup
Since reaching $142.42, INTC has already retraced sharply.
The stock initially found support around $81.64, corresponding to the previous wave iv area. However, the subsequent rebound has so far failed to reclaim the key Fibonacci retracement levels shown on the chart.
The 0.5, 0.618 and 0.786 retracement levels now act as important resistance zones.
Unless Intel can regain these levels and establish sustained momentum above them, the recovery could simply be part of the corrective structure rather than the beginning of another major bullish leg.
--
What I’m Watching Next
The most important area on the chart is the $66–$80 region.
This zone contains an unfilled gap and could provide the next major area of support as the correction develops. A move into this region would also fit the current wave interpretation, with the decline potentially developing into a larger Wave 2 correction.
If that scenario plays out, the next phase could be considerably more aggressive.
The projected Wave 3 could eventually take INTC toward the $43.47 area.
That would represent a significant decline from current levels, but it would also be consistent with the idea that the entire advance from $17.65 has completed and Intel is now undergoing a larger-degree correction.
--
The Level That Changes Everything
There is one level that would invalidate this bearish outlook:
$142.42.
As long as Intel remains below this high, the possibility of a completed five-wave advance followed by a larger correction remains valid.
A sustained move above $142.42 would invalidate the current wave count and force a reassessment of the structure.
For now, however, the chart suggests that the burden of proof is on the bulls.
Intel has already experienced an enormous rally, and the current price action may be signaling that the market is transitioning from expansion into correction. The $66–$80 gap zone is therefore the first area I would watch closely, while $43.47 remains the larger downside objective if the bearish structure develops as anticipated. Short 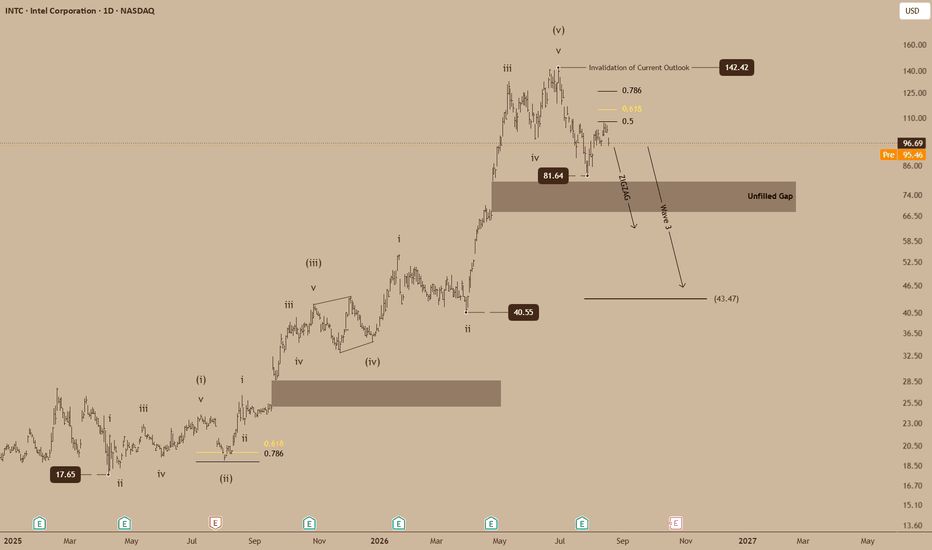
Long 
Why Is Intel Building Fortinet's Next Firewall Chip?Fortinet closed the second quarter of 2026 with results that beat its own upper guidance. Total revenue reached $2.05 billion, a 26% year-over-year gain. Product revenue told the sharper story, climbing 52% to $773 million on higher FortiGate shipments and enterprise model upgrades. Billings rose 33% to $2.37 billion. Non-GAAP gross margin held at 80.9% while operating margin expanded 490 basis points to a record 38%. Adjusted free cash flow hit $996 million, a 49% margin. Management returned capital aggressively, repurchasing 12.5 million shares for $973 million year to date.
The strategic headline sits in silicon, not in the income statement. Intel Foundry will co-develop and manufacture Fortinet's sixth-generation SP6 firewall ASIC. Fortinet becomes the first external cybersecurity customer for Intel Foundry and the first external customer on the Intel 4 node. Production runs at Fab 34 in Ireland. That geography matters. Fortinet controls roughly 48% of global firewall appliance unit shipments, and protecting that volume requires supply continuity outside East Asian foundries. The SP6 also abandons the monolithic 7nm design of the SP5 for a disaggregated chiplet architecture, which improves yields and lowers unit costs.
Demand drivers are converging from three directions. Data sovereignty rules are pushing enterprises toward local inspection, which Fortinet addresses with FortiSASE Outpost, a customer-premises point of presence for restricted traffic. Labor scarcity is forcing automation, with 56% of leaders citing skill gaps as a breach cause and 60% struggling to hire AI security talent. Enterprise AI adoption is creating a new attack surface, which FortiAIGate targets using NVIDIA Blackwell and Hopper acceleration, the Dynamo inference framework, and Nemotron safety models for inline prompt monitoring. The segment numbers reflect it. SASE firewall billings grew 34% past $2 billion, OT security billings grew over 55%, and AI-driven SecOps billings rose 25%.
Guidance moved higher across the board. Full-year revenue is now targeted at $8.02 billion to $8.18 billion, billings at $9.35 billion to $9.55 billion, and non-GAAP EPS at $3.41 to $3.47. The main modeling caution is memory component pricing, which management flags as a high-single-digit billings headwind in the second half. Fortinet mitigates that through wallet share expansion inside existing accounts and higher selling prices on performance-heavy appliances. The combination of custom silicon, Western manufacturing, and AI security integration builds a moat that software-only competitors will find expensive to cross.  Long

Short 
Long 
Short 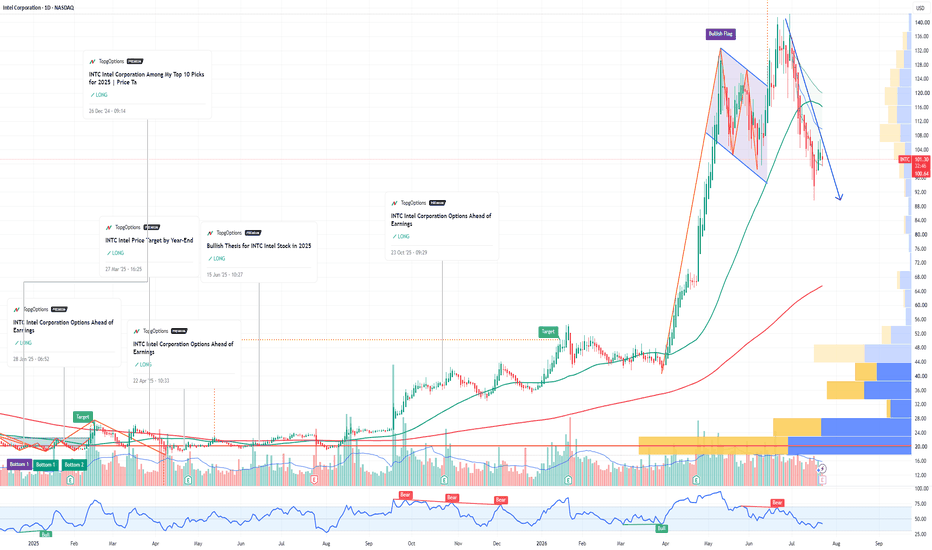
Long

INTC: Shares May Retest Rising Wedge's Lower Trendline at $116Intel (INTC) shares jumped 4% in premarket trading on Friday after the chipmaker handily surpassed Wall Street's second quarter top- and bottom-line estimates, driven by the AI boom boosting sales of its server processors. The company, which has seen its shares nearly triple this year, also topped analysts' current-quarter forecasts, soothing concerns of increased AI spending.
Taking a close look at the chipmaker's chart, the shares recently broke down from a rising wedge, a chart pattern that traders interpret as potentially leading to further downside. However, following the better-than-expected results, the price looks like possibly staging a countertrend move to retest the pattern's lower trendline.
If the stock sees post-earnings follow through buying, keep a close eye on the $116 level, a location on the chart where the shares could face selling pressure near the rising wedge pattern's lower trendline, which also currently aligns closely with the downward sloping 50-day MA.
Long 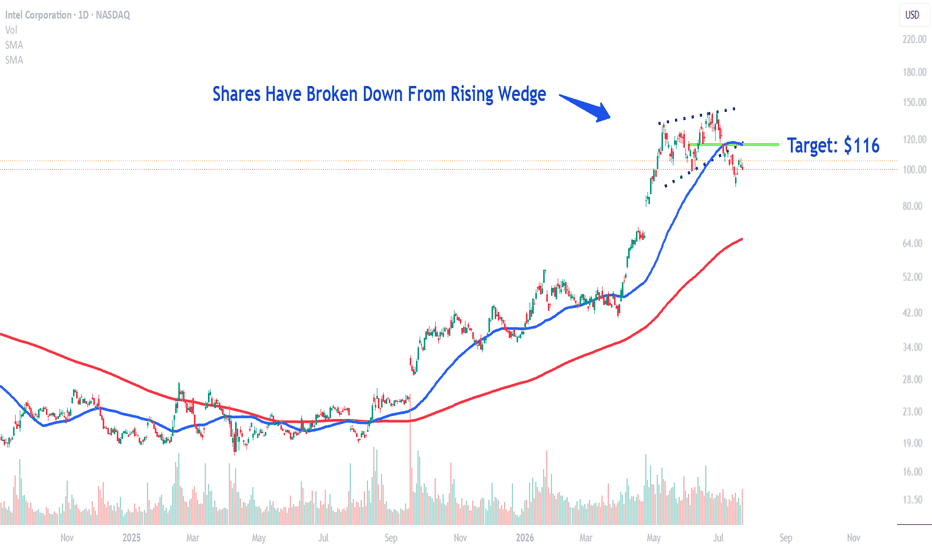
Decoding Intel’s Q2 | The Math Behind the Gross Margin RecoveryIntel Corporation has emerged as a compelling turnaround story in the semiconductor sector, driven by robust demand for AI infrastructure and steady execution under CEO LipBu Tan
Once struggling with manufacturing delays and competition, Intel is leveraging its integrated design and foundry model to capitalize on the AI boom while rebuilding investor confidence. The stock has experienced significant volatility, with a strong rally in the first half of 2026 followed by pullbacks, reflecting high expectations around its strategic pivot
Intel's Q2 2026 earnings delivered a strong beat and marked its highest revenue growth in over 15 years. Revenue reached $16.1 billion, up 25% year over year from $12.9 billion, far exceeding Wall Street expectations of around $14.4–$14.5 billion. NonGAAP EPS came in at $0.42 (versus estimates near $0.21–$0.22 and a prior year loss), while GAAP results showed a $2.16 per share loss primarily due to a large non cash mark to market charge on CHIPS Act escrowed shares. Gross margins improved markedly to 40.4% GAAP (41.8% nonGAAP), supported by higher volumes, better yields, and favorable mix
Segment performance highlighted AI momentum as the key driver. The Data Center and AI (DCAI) group surged 59% year over year to $6.3 billion, fueled by strong Xeon 6 processor ramps and enterprise/cloud demand for x86 AI infrastructure. Client Computing and Physical AI revenue grew 13% to $8.9 billion, with AI PC contributions rising notably
Intel Foundry posted $5.8 billion in revenue (up ~30–31%), advancing process technology with Intel 18A-P entering risk production and High NA EUV milestones. Operating income turned positive at $1.8 billion GAAP, a sharp reversal from prior losses
Intel provided upbeat Q3 guidance of $15.8–$16.8 billion in revenue (above $15.1 billion consensus) and nonGAAP EPS of $0.38. The company raised 2026 capex above $20 billion to support demand across products and foundry, signaling confidence despite ongoing supply constraints
While foundry losses persist ($2 billion in the quarter), progress on advanced nodes and customer collaborations (e.g with SambaNova) position Intel for potential external wins. Risks remain around execution, competition from NASDAQ:AMD , VANTAGE:NVIDIA , BCBA:TSMC and high valuation multiples
Intel's latest results underscore meaningful progress in its multi year transformation, with AI tailwinds providing a clear growth pathway amid improving operations. Investors should monitor foundry customer traction and margin sustainability in coming quarters..For those with a longer term horizon, Intel offers exposure to both traditional computing recovery and AI infrastructure expansion, though volatility is likely to persist given the ambitious scope of its investments and competitive landscape. Can Intel Reclaim Its Chip Supremacy?Earnings at a Critical Crossroads
Intel faces a crucial earnings crossroads. Red-hot AI demand aggressively battles a sluggish PC market. The company must prove its massive investments will yield profits. Recent stock price volatility reflects deep macroeconomic anxiety. Yet, management boldly pushes forward with sweeping reorganizations. The company has already reduced its global workforce by roughly 40,000 over the past two years, and it is now preparing a further, separate round of layoffs targeting its Data Center Group. This harsh economic reality ultimately tests leadership resolve.
Technology & Patent Analysis
Intel firmly anchors its comeback in cutting-edge technology. They proudly enter the Angstrom era of manufacturing. Engineers now manipulate individual atoms to build faster processors. The highly anticipated 18A node recently entered active production. This ambitious technology leverages vital patents in two specific areas:
* RibbonFET: This structural breakthrough offers revolutionary gate-all-around transistor designs.
* PowerVia: This backside power delivery routes energy efficiently from underneath the silicon.
These patented high-tech innovations maximize performance and slash power consumption. Intel aggressively protects these semiconductor breakthroughs globally. Furthermore, Intel recently secured High-NA EUV tools from ASML. They will manufacture next-generation laptop chips using this advanced machinery.
Geopolitics & Geostrategy
Geographical semiconductor concentration poses severe global risks. A localized earthquake or political conflict could halt global chip supplies. Consequently, Intel positions itself as the premier domestic foundry solution. They bring both foundational intellectual property and cutting-edge factories to American soil. The entire US economy fundamentally runs on semiconductors today. Intel's massive domestic investments ensure robust national supply chain security.
Industry Trends & Business Models
The relentless AI revolution dictates entirely new industry paradigms. Market demand heavily shifts toward advanced AI processors and cloud infrastructure. Intel decisively pivots its business model to compete effectively. They strategically opened their foundry services to external clients. Recently, Intel landed a major foundry deal with Fortinet, manufacturing the cybersecurity firm's next-generation SP6 security processor and marking Intel Foundry's first publicly named cybersecurity customer. This partnership validates Intel's open ecosystem strategy.
Cybersecurity, Science & Pharmaceuticals
Modern cybersecurity demands impenetrable hardware foundations at the silicon level. Intel and Fortinet now collaborate to advance security innovation. This partnership significantly strengthens global supply chain resilience. Fortinet trusts Intel's foundries for critical infrastructure components. Advanced silicon also accelerates global scientific and pharmaceutical breakthroughs. High-performance chips drive rapid AI drug discovery and complex genomics. Intel's computing architecture powers the massive datasets required for modern medical research.
Culture, Innovation & Leadership
Intel radically transforms its internal corporate culture to survive. The company aggressively slims down its rigid organizational structure. The data center group faces tough restructuring to improve efficiency. Management demands ruthless prioritization to catch highly agile rivals. Technicians apply immense passion to solve complex engineering challenges daily. Executive leadership insists on pioneering the AI computing future. They know market survival requires relentless, hyper-focused innovation.
Long 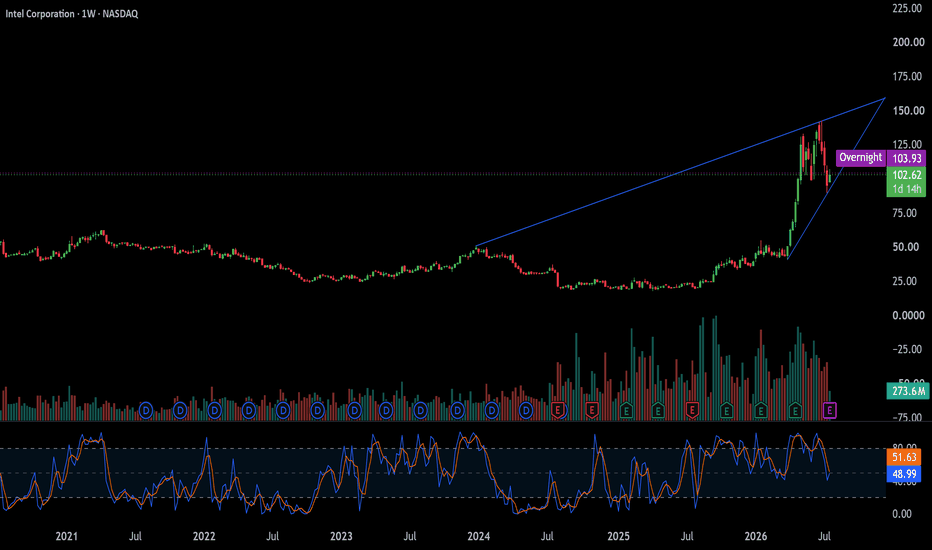
Is Washington Quietly Building the TSMC of Quantum?The semiconductor market has entered a new strategic era. Rising Taiwan Strait tensions make Western reliance on foreign fabs an unacceptable risk. Washington has responded by converting grants into ownership. The US government now holds a 9.9% stake in Intel, acquired for $8.9 billion, alongside roughly 1% of GlobalFoundries (GFS). When the state becomes a shareholder, consolidation stops being a rumor and starts becoming policy.
GlobalFoundries brings real substance to this thesis. The company earns $778 million in net income from stable, mature specialty nodes. In May 2026, it launched Quantum Technology Solutions, backed by a $375 million CHIPS Act grant. The division supports five quantum hardware modalities, including Cryo-CMOS chips on the 22nm FDX platform that operate near absolute zero. A partnership with SEALSQ adds post-quantum cryptography, while a patent portfolio exceeding 8,000 filings anchors its legal moat against rivals like Tower Semiconductor.
The article's central scenario is bold: an Intel-GFS merger that creates the TSMC of quantum computing. Intel prints silicon spin qubits on standard production lines, bypassing exotic low-yield cleanrooms. GFS contributes mature-node cash flows that offset Intel's brutal leading-edge capex, plus Synopsys RISC-V processor IP for end-to-end silicon systems. A modular, daisy-chained architecture could theoretically scale toward one million stable qubits.
Is this speculation or inevitability? The deal remains a thesis, not an announcement, and antitrust plus integration risks loom large. But the combination of sovereign equity stakes, quantum manufacturing capacity, and complementary balance sheets suggests the pieces are already on the board. The full analysis breaks down the mechanism, the risks, and the verdict.
 Long

INTC - Retesting the $100 Decision Zone?Intel (INTC) is currently pulling back toward a major support confluence after its recent bullish rally. 📉
Price is now retesting a key decision zone, formed by the intersection of:
• The $100 round number.
• The previous daily low marked in blue.
📌 As long as this confluence holds as support, we will be looking for trend-following long setups, anticipating a continuation of the broader bullish trend.
However, if sellers manage to break this support decisively, bearish pressure would likely increase, exposing the next major demand zone around $70 marked in red.
As always, rather than buying blindly into support, we will wait for bullish confirmation before considering any long positions.
Will buyers defend the $100 support zone and resume the uptrend? 🤔
⚠️ Disclaimer: This is not financial advice. Always do your own research and manage risk properly.
📚 Stick to your trading plan regarding entries, risk, and management.
Good luck! 🍀
All Strategies Are Good; If Managed Properly!
~Richard Nasr Long 
Can Intel Justify Wall Street's $200 Target?The 2026 Resurgence
Intel Corporation commands Wall Street attention in 2026. Shares skyrocketed over 470% from their 52-week low. HSBC recently issued an unprecedented $200 price target. This bold call highlights massive confidence in the tech giant. Analysts recognize Intel's pivotal role in artificial intelligence infrastructure. The company perfectly aligns with surging global demand.
Geopolitics and Geostrategy
Global tensions force nations to secure domestic technology supply chains. Intel anchors Western semiconductor independence. The company builds vital foundries across the United States and Europe. These massive facilities neutralize reliance on vulnerable overseas manufacturing. Geopolitical realities make Intel an irreplaceable asset for national security. Leaders view domestic chip production as a critical strategic imperative.
Macroeconomics and Economics
Intel exhibits powerful economic momentum in 2026. The company reported a 7% revenue increase to $13.6 billion recently. High valuation metrics reflect immense future growth expectations. The market happily prices Intel at 190 times forward earnings. AI infrastructure spending fuels this massive capital inflow. Investors eagerly fund Intel's aggressive manufacturing expansion plans.
Management, Leadership, and Culture
Lip-Bu Tan's appointment as CEO sparked a radical corporate turnaround. His visionary leadership ruthlessly targets operational efficiency. Tan replaced complacency with a fierce, competitive drive. This shift revitalized company culture and engineering execution. Teams now prioritize aggressive innovation and bold product launches. Management successfully aligns internal goals with brutal market demands.
Business Models and Industry Trends
Intel is transforming its core business model. Intel Foundry Services has secured reported engagements with major technology companies, including Apple, Tesla, SpaceX, and Google. This strategic pivot targets a massive share of the AI supply chain, though the business remains early-stage and loss-making, with external customer revenue of just $174 million against a $2.4 billion operating loss in the first quarter of 2026. The company generates its profits today from CPU sales and advanced packaging, with foundry profitability targeted as 18A yields mature toward late 2026 and 2027. Evolving industry trends demand integrated, high-capacity manufacturing solutions. Intel positions itself to capture this lucrative ecosystem as foundry engagements convert into shipped revenue.
Technology, Science, and High-Tech
Upcoming Nova Lake processors introduce disruptive technological leaps. Intel readies 22-core configurations for the gaming market. A massive 108MB bLLC cache directly rivals competitor gaming designs. The LGA-1954 socket supports up to 52 cores for workstations. Furthermore, Intel officially brought AVX-512 instructions back to client processors. This identical ISA across all cores accelerates scientific computing tremendously.
Cybersecurity and Patent Analysis
Hardware-level security remains paramount in modern silicon architectures. Intel continually integrates advanced threat detection directly into its processors. This thwarts sophisticated cyberattacks before they reach software layers. Furthermore, Intel fiercely protects its innovations through rigorous patent analysis. A vast patent portfolio secures proprietary semiconductor manufacturing techniques. These patents block competitors while generating lucrative licensing revenue.
Pharmaceutical Industry Connections
High-performance computing revolutionizes the modern pharmaceutical industry. Intel processors dramatically accelerate complex genomic sequencing processes. Advanced AI inferencing on AVX-512 hardware models molecular interactions swiftly. Pharmaceutical companies rely on this immense compute power for drug discovery. Intel directly enables breakthroughs in personalized medicine and biochemistry. Faster processing times save millions of dollars in research costs.
Conclusion
Intel executes a flawless, multi-pronged strategy in 2026. Leadership successfully navigates complex geopolitical landscapes and technological hurdles. The company leverages advanced architectures like Nova Lake to secure market dominance. Intel remains a foundational pillar of the global digital economy. Long 
Meta cloud pivot reframes the AI capex narrativeMETA | 4H Technical Analysis — Jul 6, 2026
Reports that Meta plans to monetize surplus compute capacity as a cloud service sent the stock up nearly 10%, as Wall Street reframed the $145B capex plan from a liability into a potential revenue stream. DA Davidson interpreted the move as a signal that Meta may be shifting focus from frontier AI development to monetizing computing power, noting significant upside to revenue and cash flow if the pivot materializes. UBS added that the news suggests capex expectations may no longer be skewed only to the upside. The read-across hit neo-cloud names like CoreWeave and Nebius hard, while hyperscalers Amazon, Microsoft, and Alphabet rallied on reduced capex competition concerns. Memory and semiconductor names, including Micron, AMD, Intel, and Marvell, sold off on the implication of lower AI infrastructure demand.
META has been in a well-defined descending channel since the April peak near 690, with price grinding lower through 640, 600, 580, and 540 before today's sharp reversal. Price is currently trading around 580, with EMA21 (575.75) below EMA78 (591.97), a bearish configuration that has capped every recovery attempt since the channel began.
The recent gap up is the most significant single-session move since the channel's inception, pushing price back above 580 and to above the 600 level, which represents the critical confluence of the channel’s upper bound and EMA78. RSI at 52.34 has reset from oversold lows near 30 seen during the June flush to 540, now sitting at a neutral level with room to extend higher without immediate exhaustion.
The channel structure remains intact until 600, and EMA78 are both cleared and held on a closing basis. A reclaim of 640 would mark a full structural reversal.
Key levels to watch:
Resistance: 600 / 640 / 690 (cycle high)
Support: 580 / 560 / 540 (June low) / 520 (end-March low)
Bear case: Failure to close above 600 and EMA78 would confirm the channel remains intact and the news-driven spike is being faded. A rollover back below 580 and toward 560 would keep the broader downtrend structure in control.
Bull case: A daily close above 600 and EMA78 would mark the first meaningful structural break of the descending channel. Follow-through above 640 would confirm the reversal and open the path toward a retest of the 690 cycle high, with the cloud monetization narrative providing a durable fundamental catalyst.
Bias shifts to cautiously bullish on the channel breakout attempt — the news reframes the capex narrative constructively, and RSI has reset from oversold, but the 600 and EMA78 levels must be reclaimed and held before the structural trend can be called reversed.
INTC | Intel Rides The Uptrend — Eyes On The Buy-Side Liquidity!
By analyzing the #Intel (INTC) chart on the Daily timeframe, we can see that price remains firmly within a strong uptrend, having printed a clean series of bullish BOS on its way up. As long as price holds above its Protected Low, the higher-timeframe bias stays firmly bullish.
📊 Daily Timeframe
On the Daily, the structure is textbook bullish. Notice that before printing the most recent BOS, price pulled back and reacted cleanly from the Order Block below — using it as fuel to launch the next leg higher. That's exactly the behavior we want to see in a healthy trend.
Right now, my expectation is for a similar rotation: price dips to grab the liquidity resting below, reacts from the lower Order Block ( $104.97 – $111.35 ), and then pushes higher to target the buy-side liquidity (BSL) resting overhead at $142.53 . The whole bullish thesis stays valid as long as price holds above the Protected Low at $98.16 — a decisive break below that level would be the first real warning that the trend is at risk.
⏱️ 4H / 1H Timeframe
Across the lower timeframes — the 4H and 1H — the picture is fully aligned with the Daily. The same Protected Low at $98.16 holds as the key structural level on those frames too, meaning all timeframes are telling one consistent story: buyers remain in control, and dips into the Order Block ( $104.97 – $111.35 ) are opportunities rather than threats until that low breaks.
🎯 The Bias
My base case is a corrective dip into the lower Order Block ($104.97 – $111.35) to sweep the liquidity below, followed by a bullish reaction that carries price up toward the BSL at $142.53. In my view, as long as INTC holds above the Protected Low ($98.16), every pullback into demand remains a buying opportunity rather than a reversal signal.
📰 Fundamental Backdrop
The bullish structure is backed by one of the most remarkable turnaround stories in the market this year. Intel has been on a historic run — up several hundred percent in the first half of 2026 — driven almost entirely by renewed optimism around its Foundry business. That momentum has been reinforced by a wave of analyst upgrades: HSBC recently doubled its price target to $200 (from $100) after including the foundry business in its valuation, and another top analyst hiked their target by 100%, calling the foundry story "too good to ignore." Major AI-chip foundry interest tied to names like Google, Apple, and SpaceX has kept the narrative alive. That said, the stock is not without risk — it now trades at a rich valuation, recently pulled back sharply on a broad semiconductor sell-off, and the next major catalyst is Q2 earnings on July 23, which could inject volatility in either direction. For now, though, price action and fundamentals are pointing the same way: higher.
This analysis will be updated as the market evolves. If this breakdown added value, drop a like 👍 and a comment 💬 to support the work — and share where you see Intel heading next! Best Regards, BigBeluga 🐳 The Giant's Rebirth: Long-Term Prospects for INTCIn times when the market seems on the verge of falling, opportunities arise that only the most astute investors are able to recognize. We are now witnessing one of those rare moments with INTC. The events of the last few days, in which the CEO was forced to resign or be fired, mark not just a corporate reshuffle, but perhaps a historic turning point. History teaches us that such significant leadership changes are often harbingers of recovery and growth. Watching the price-to-sales drop to levels we've only seen in the darkest times of the past indicates that we may have hit bottom. This is not just a signal, it is a once-in-a-decade chance. INTC now offers us a unique opportunity for long-term investing with minimal risk. We are not talking about short speculation; this is an investment in the future of a company that is on the cusp of new growth. If we look at the patterns of past recoveries, we see that such situations often precede multi-year upturns. Looking at all aspects, I would rate this opportunity as having a tremendous probability of success. We are facing potential huge long-term profits. This is not just an investment; it is a bet on the revitalization of a company that is now at the bottom of its cycle, but with tremendous upside potential. This may be one of those rare occasions when we can buy at the very beginning of a recovery, when all market fears turn into strategic advantages for those willing to look beyond the current news.
Horban Brothers,
Alex Kostenich Long 
Resistance Zone: 117.87 ~ 129.44
Hello?
Nice to meet you, fellow traders.
If you "follow" me, you can always get new information quickly.
Have a great day.
------------------------------------
Important zones are marked with circles and square boxes.
The 117.87 ~ 129.44 range is a high point zone and corresponds to a resistance zone.
However, if it finds support in this range and rises, there is a possibility of a stair-step upward trend.
Therefore, if it finds support around the 117.87–129.44 range and rises, it is expected to increase to the Fibonacci ratios 2.618 (160.79)–3.618 (162.17).
If it fails to rise and falls:
1st: 95.69
2nd: 70.33–79.62
We need to check if it finds support around the 1st and 2nd levels mentioned above.
Since a gap is expected to occur in the 70.33–79.62 range, if it finds support near this area, it can be considered a strong buying opportunity.
However, since the area around 96.69 corresponds to a high point from a sharp rise, it appears highly likely that it will find support in this vicinity.
-
In order to receive support at a key point or zone and continue the uptrend,
1. The uptrend must be observed while the StochRSI indicator has not entered the overbought zone.
2. The OBV indicator must be maintained above the High Line.
3. The BSSC indicator must be maintained above the 0 point.
- Currently, only the BSSC indicator is maintaining above the 0 point,
- It appears highly likely that the StochRSI indicator will enter the oversold zone,
- Since the OBV indicator appears to have fallen from the High Line, it seems likely that a support test will follow to sustain the uptrend.
-
Thank you for reading to the end.
I wish you a successful trade.
--------------------------------------------------
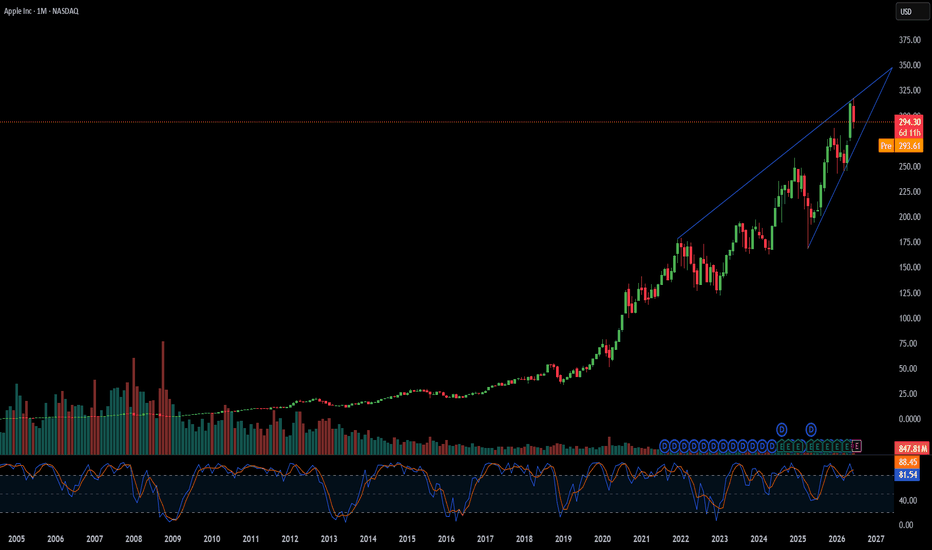
Is Apple's Real Squeeze Memory, Not Intel?Apple's real financial story is memory, not Intel. In a June 17 interview, outgoing CEO Tim Cook said product price increases were "unavoidable," describing the cost environment as a "hundred-year flood." The driver is an AI-fueled surge in memory and storage chip costs. Samsung, SK Hynix, and Micron are diverting capacity toward higher-margin high-bandwidth memory for AI data centers, pushing DRAM prices up a projected 130% in 2026 and roughly tripling the cost of some storage tiers. This is the material event: Apple's first genuinely cost-forced price hikes after years of quietly absorbing input inflation.
The margin math is what matters. TechInsights estimates the next iPhone Pro carries about $270 in added cost, a roughly 25% jump concentrated almost entirely in memory and storage rather than the processor, display, or chassis. Apple's scale lets it absorb some of that, but only to a point, and the July 30 earnings call is the real test. Gross margins holding near 46% to 48% would keep the earnings thesis intact, while a drop below 45% would force a Wall Street recalibration. Mark Gurman reports the first hikes could land in the Back-to-School window, with the iPhone 18 Pro launching at the new, higher pricing.
The Apple-Intel deal is a separate, smaller story that should not be confused with the cost problem. Trump confirmed on June 18 that Apple will use Intel's 18A-P process, but for lower-end logic chips only, while TSMC keeps more than 90% of Apple's silicon. Logic-chip diversification is strategically sensible given TSMC's capacity strain, and Cook has admitted iPhone production was constrained by TSMC's limits. But Intel makes none of Apple's memory, so the deal does nothing to ease the cost pressure driving the price hikes. Analysts rightly call it a small hedge, and Intel is not expected to challenge TSMC for advanced chips until roughly 2029.
For investors, the signal is the margin line on July 30, not the Intel headline. The memory shock is the near-term event that ends Apple's long run of price stability and tests its gross margin, while the Intel deal is long-dated optionality with minimal immediate impact, which is why Apple shares barely moved on the news. Apple weathers this better than almost any hardware maker, thanks to its scale and a Services business that cushions hardware cycles. But the era of absorbing rising input costs is over. Watch the timing and size of the price increases, and treat the Intel partnership as insurance rather than a fix.  Long