Iron Condor on SQThis is over earnings. The 90/95 bear call spread is above the 100 sma on the monthly.
The 60/55 bull put spread is below the 100/200 sma on the daily and 100sma on the weekly
Simply expecting NOT a huge gap on earnings and allow the IV to fizzle out on this one. Since we are getting $1.00+ on a $5 margin, this is 20% ROR
:)
Going for 1.02 of credit :-)
Ironcondors
Options Blueprint Series: Iron Condors for Balanced MarketsIntroduction:
In the nuanced world of options trading, the Iron Condor strategy stands out as a sophisticated yet accessible approach, especially suited for markets that exhibit a balanced demeanor. This strategy, belonging to the "Options Blueprint Series," is designed for traders who seek to harness the potential of stable markets. Iron Condors offer a way to generate profit from an underlying asset's lack of significant price movement, making it an ideal choice for periods characterized by
IWM Put Credit Spread (see related) into a ICIWM continued to fall today, so I decided to look on the call side to turn this into an Iron Condor.
Why?
1. Condors do not increase margin over a spread
2. IWM has been range bound
3. Large cushion past 2 resistance points
4. Additional Credit recieved
Opened Feb 2nd 236/238 IC for a 0.22 cent credit.
How Does Implied Volatility Effect Premium Selling Strategies?In this video I address a question from a member of my social media. I wanted to answer this for them and educate others on why paying attention to Implied Volatility is important to your probability of success and your strategy returns if you are employing Premium Selling Strategies (Iron Condors, Credit Spreads, Straddles, Strangles, Butterflies, etc.)
IRON TARIHi guys,
this week I found better opportunies buying options rather selling ( IV drop made options cheaper to buy)
So the strategy is basically the contrarian of my Tari Condor ( Have a look and subscribe for free!), and as you can see this trade is 4 weeks and 6% spread.
The sold strikes are 132 and 117, the bought strikes are almost ATM, it depends on your money managment, for a 65% of probability to get some profit.
But let's do some math: Tari Condor says we have only the 22% of possib
Watch this BEFORE taking Iron Condors! (IV Rank & Percentile)Iron Condors have been the buzz lately on my social media. People have discovered or re-discovered them because they are WORKING now! But should traders keep using them without knowing WHY they are working? If you are getting into Iron Condors you MUST watch this to understand the key metrics professional options sellers look at when placing their trades.
Tradingview cut me off at 20 minutes but I got the info in!
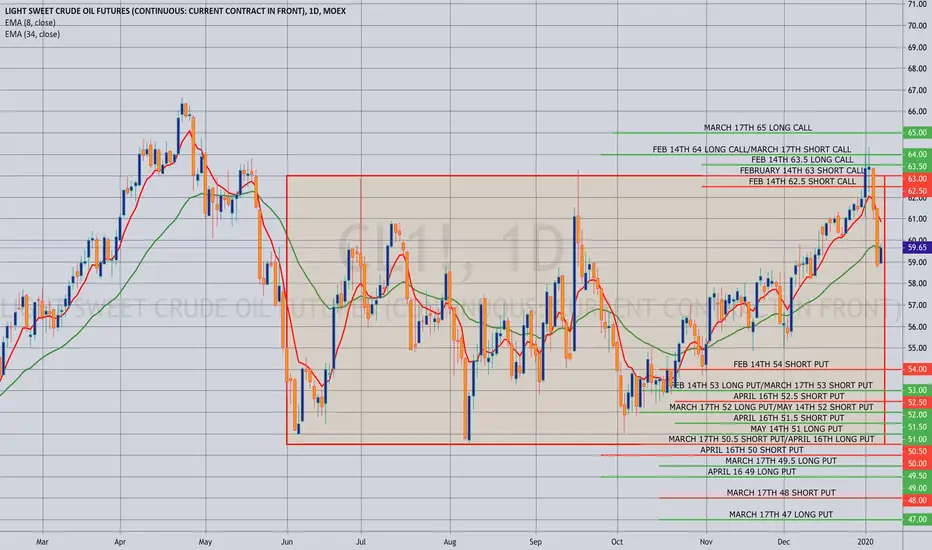
OPENING: /CL APRIL 16TH 51/52 SHORT PUT VERTICAL... for a 1.60 credit; scratch at 16.50 versus total setup value of 15.65 (i.e., currently up 16.50 - 15.65 = .85/$85).
Notes: A delta under hedge in the first expiry in which the at-the-money short straddle is paying greater than 10% of the underlying. Net delta leans short.
CLong
CLOSING: /CL FEBRUARY 14TH 53/54/63.5/63.5 IRON CONDOR... for a 3.00 debit; 3.50 ($350) realized profit; scratch at 14.40.
Notes: Taking off the remaining risk in the February cycle. Net delta remains long, which I'm fine with, since exogenous risk lies to the call side. And while I took some nice profit here, I'm still slightly underwater relative to the total extrinsic left of 15.45 or so.
C
CLOSING: /CL MARCH 17TH 47/48 SHORT PUT VERTICAL... for a .70 debit, 1.00 ($100 profit).
Notes: A bit of subtractive delta balancing. Scratch at 14.10.
C
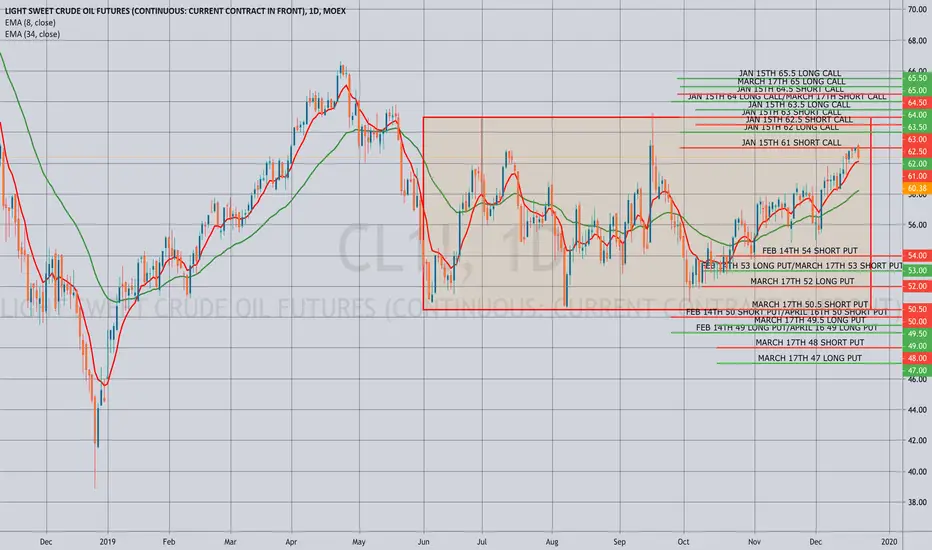
ROLLING: /CL JANUARY 15TH 62.5/63.5 SHORT CALL VERTICAL... to February 14th 62.5/63.5 short call vertical for fees only (i.e., the credit received was the same as the cost to close out the January spread, so it's a wash from that standpoint).
Notes: As with the other spread I just extended duration on, this may need a little more time to work out and/or for me to reduce cost basis.
C
CLOSING: /CL JANUARY 15TH 51/52 SHORT PUT VERTICAL... for a .20 debit, 1.00 ($100) profit.
Notes: Out of the put side in the January cycle, leaving some call side to manage running into expiry. Scratch at 19.80. I would note that /CL rank/implied isn't great here (4.3/26), so the obvious best case scenario is that I not have to roll out in this low volatility environment.
C
TSLA Iron CondorSince IV is high on tesla I'm putting on BOLD play.
This looks like low risk high reward.
270/275/360/365 Iron Condor Exp Dec 20th. 3 spreads. Credit per spread was 1.43 5 point wide.
Credit collected is $429 this will be my max loss.
30 delta call and 16 delta put I want to take my profits at around 30% max credit which will be $130 profit.
This looks like an awesome trade.
TSLA Iron Condor ContinuationTSLA looks to be trending lower as it continues toward its destination I plan to capture some profits using an iron condor.
IV is really high at around 50
180/185/240/245 $150/350 Profit/Risk June 21 EXP
Profit Target to be expected by June 10-14
Profit Target is $80 max loss is $160
This is a journal entry and not trading advice.
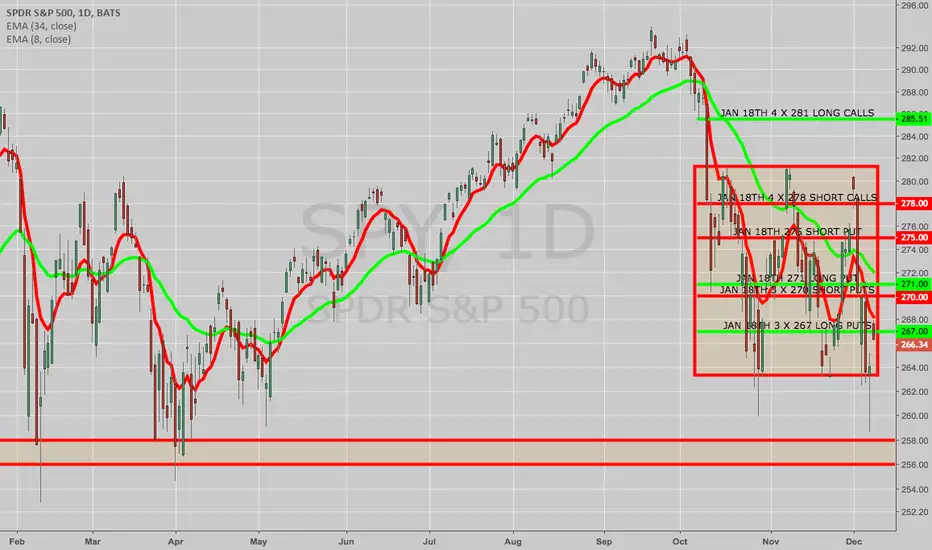
CLOSING/ROLLING/SELLING AGAINST SPY CORE POSITIONVisually, this looks like a bit of a mess ... .
As of NY open, I was left with the following spreads left over from iron condors I had put on over time and/or rolled toward current price to delta balance:
A Dec 271/275 short put vertical.
3 x Dec 267/270 short put verticals.
A Dec 280/283 short call vertical.
2 x Dec 277/281 short call verticals.
I first pulled off the call spreads, closing the 280/283 for a .15 debit, and the 2 x 277/281 for a .38/contract debit (for a net debit of .76, sinc
BROKEN OPTIONS SETUPS AND THE ART OF PATIENCEPeople have frequently mentioned to me that they can't make iron condors work for them, primarily because a single broken setup can undo a long string of profitable trades. This, of course, is a true statement if absolutely nothing is done to attempt to repair these broken trades and get them back to at least scratch or, ideally, into profit. It's all a question of patience.
Here is one of my most patience-testing trades I've been diligently working since October 2015 earnings -- YUM. I'm sh
IMPLIED VOLATILITY LULL -- A GOOD TIME TO DO HOUSEKEEPING ... .With the CBOE Volatility Index at 13-ish here, there is nary a premium selling play in the market ... .
Naturally, that can quickly change, but in the mean time, it's "housekeeping time." "Housekeeping time" is a largely boring affair:
1. Look at Setups for Delta Balancing. If you've been reading any of my posts, you'll notice that I largely concentrate on "oppositional" trades, like iron condors and short strangles. While I do look at these frequently to see whether delta balancing should
ROLLING GLD JUNE 17TH 117/120 TO JULY 1ST 118/121 SHRT CALL VERTMore housekeeping ... . Taking advantage of this down move in gold to roll the call side of this June 17th iron condor for cheaper than I could do so at the top of GLD's arc at nearly 124. I did the roll for a $28/contract debit.
Here's the complicated part: In rolling the 117/120 out to July, I was left with an unpaired short put vertical in June. I didn't want to cover it yet, since the spread had increased in value with this down move. Consequently, I sold a June 17th 121/124 short call
OPTIONS TIP: HOW TO PLAY EARNINGS (PT II)5) Look at Setups in Expiries in the Friday Immediately Following the Announcement or the Friday Thereafter. I mechanically set these up in options that expire the week following the announcement, as it gives me a little more time for the setup to work out.
6) Avoid ADR's and/or Underlyings That Aren't Scheduled to Announce on a Particular Date/Time. Next week, STX earnings are scheduled "for some time on April 15th." If STX doesn't know at this point in time whether it's going to be before m
OPTIONS TIP: HOW TO PLAY EARNINGS (PT I)Traditionally, AA's earnings announcement marks the beginning of the earnings season for me, and it announces earnings on Monday after market close. Naturally, there are tons of plays you can make, but, unfortunately, not all are ideal for premium selling or, for that matter, other options strategies that rely on a firm directional assumption (like Super Bulls/Super Bears).
Here's a short checklist for what to play and what not to play with options, with an emphasis on what to look for in prem
FOMC'S OVER -- WHAT TO DO WITH MY TESTED CREDIT SPREADS -- PT 2(Cont'd from Part I).
I then look at selling an oppositional side (in this case, the short put "wing") (1) for at least .10 more in credit than it cost me to roll the tested side; (2) with the highest probability of profit I can do that for; and (3) that does not result in an "inverted" iron condor (trust me, you do not want to try to work an inverted iron condor; an inverted short strangle is a different matter; I'll discuss that in some other post if I'm ever presented with that situation wi
FOMC'S OVER -- WHAT TO DO WITH MY "TESTED" CREDIT SPREADS? PT 1(I have to do this in two posts since I'm verbose, and can't fit it into one ... ).
Now that March FOMC is over, I'm ready to wait back in ... in a bit.
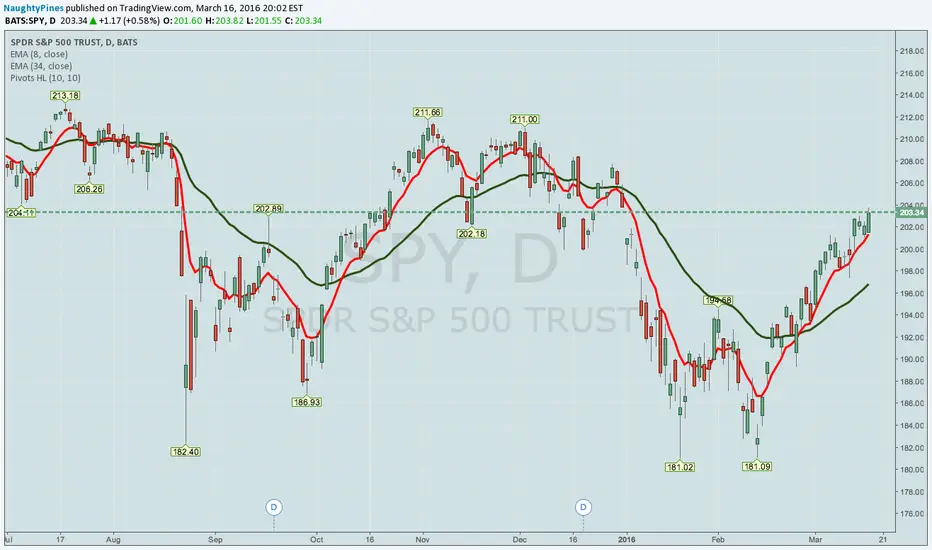
Before Draghi, I rolled my March 18th expiry SPY short call verticals out to the April 1st expiry to buy some more time, selling short put credit spreads to finance a slight strike improvement of those to 196/200, after which I proceeded to peel off the short put spreads, because, well, they were worthless after this upmove ("worthless" is a g
SPY, QQQ -- PEELING OFF PUT LAYERS OF MY MARCH 15TH "ONIONS"With the March monthly options expiry a scant two weeks and some away, I'm peeling off the short put vertical wings of my March iron condors in QQQ and SPY as they approach worthless (<.10 debit for a spread). Naturally, the hope was that price would stay well within my "target zone" for these "onions" and that I'd be able to peel off layers by covering the iron condors as a unit by mixing and matching spreads from the put sides and the call sides. However, with this first-of-the-month upmove,