Streak Reality Check - was that losing run actually unusual?Most people abandon a working strategy during a losing run rather than because of anything in the numbers. The run feels like new information. Usually it is not, and roughly how long a run you should expect is calculable before it happens.
For n trades at a win rate w, the expected longest run of losses is about:
log(n × w) / log(1 / (1 − w))
That is the standard result for the longest run of failures in n Bernoulli trials. It has one property worth sitting with: n is inside it. More trades means more chances for a long run, so the run you should expect grows as you collect data. Slowly, because it is logarithmic, but it grows.
Which is why a fixed limit — "abandon anything with a run above 10" — gets stricter the more data you have. The same strategy passes early and fails later, having done nothing different in between. This script reports the ratio of observed to expected instead, because that is the number which means the same thing at every sample size.
What the table shows
Trades (non-overlapping). How many complete trades the sample produced, and how many timed out rather than resolving.
Win rate. Measured, not assumed. The expected run depends on it heavily.
Worst losing run. The longest consecutive run of losses in the sequence.
Expected at this sample. What that trade count and win rate should produce by chance.
Observed / expected. The number you came for. Around 1.0 means the worst thing that happened was typical. Below about 1.3 a long run is a long run and not a signal. Well above it, something in that stretch is worth understanding.
Sample covers. The period measured. A run length with no period attached invites more confidence than it has earned — 3,000 bars is six weeks on a 15m chart and twelve years on a daily one.
Non-overlapping trades, and why that matters
This measures differently from its two companions, deliberately.
Edge Reality Check and Filter Reality Check resolve from every bar. That is correct for measuring a hit rate: it uses the whole sample, and the overlap does not bias an average.
It would wreck a streak measurement. Samples opened on consecutive bars share almost all of their holding window, so their outcomes are strongly correlated, and one bad stretch of price would show up as a single enormous run of losses. Compared against a formula that assumes independent trades, that returns a ratio of three or four and a verdict of catastrophe on perfectly ordinary history.
So this one opens a trade, resolves it, and only then looks for the next entry. Fewer trades from the same history, and a sequence whose runs mean something. Expect a much lower trade count than the other two give on the same chart — that is the rule working, and the table labels the row so the difference is visible rather than mysterious.
Method, and its limits
A bar spanning both stop and target counts as a loss. There is no way to know which came first from bar data, and being wrong pessimistically is the only honest resolution. It matters more here than in the companion scripts: resolving those ties optimistically would break up runs and flatter every streak on the chart.
Distances can scale with each historical bar's own ATR, so the test uses the volatility of the time rather than today's.
Trades reaching neither level within the holding window are reported as timed out, not counted as losses. Counting them as losses would manufacture runs that never happened.
Fifty resolved trades is the floor. Below that the script refuses to compare, and says so. A streak is a tail statistic and needs more sample than an average does — a hit rate stabilises long before the longest run does.
The formula assumes independent trades. If your own trades overlap in time, or fire on correlated instruments, your effective sample is smaller than your trade count, the expected run is correspondingly smaller, and your real run is worse than the ratio suggests. The non-overlapping rule handles this inside the script; it cannot handle it for the strategy you are comparing against.
It is an expectation, not a bound. Runs longer than it are ordinary. The distribution has a tail on both sides, and a single measurement on one window settles nothing — run it across several.
What it is not
It places no trades, gives no signals and predicts nothing. It cannot tell you a strategy is broken. It tells you whether a losing run is evidence of anything, which is a smaller and more useful question, and the answer is usually no.
Open source. Companion to Edge Reality Check, which measures the hit rate entering at random would have produced at your reward-to-risk, and Filter Reality Check, which tells you whether a condition you are using beats that baseline. Indicator

TURKS - Tiered Unit Risk Kernel StrategyTURKS decides how much of a long position to hold. Exposure is a graded function of where the close sits against four moving averages (20/50/100/200), so it moves in rungs rather than switching on and off. That function is monotone in price, which means it inverts: every rung has exactly one price. The panel prints those prices before they are reached — a ladder of levels at which the position gets larger or smaller, readable today.
Long-only, 0 to 1, no shorting and no leverage.
📊 THE RESULT
Twelve symbols, shipped defaults, 4-hour charts, full available history. Commission $1.50 per order, slippage 0.01xATR per side, idle cash credited nothing. b&h is buy-and-hold over the identical bars, charged nothing at all. The comparison is deliberately rigged against the strategy.
CAGR MAX DRAWDOWN CAGR / maxDD
symbol sample TURKS b&h TURKS b&h TURKS b&h
SNDK 1.3y +1406.3% +1899.0% -37.2% -56.8% 37.82 33.43
ETH 9.5y +117.3% +71.9% -54.4% -94.1% 2.16 0.76
BTC 9.5y +70.0% +54.2% -62.3% -83.9% 1.12 0.65
ARM 2.7y +62.5% +72.9% -39.8% -55.8% 1.57 1.31
TSLA 15.9y +32.7% +41.7% -57.0% -74.9% 0.57 0.56
NVDA 22.4y +25.3% +36.4% -77.0% -85.2% 0.33 0.43
AMD 21.4y +20.2% +17.3% -69.3% -96.1% 0.29 0.18
AVGO 16.8y +16.9% +39.0% -36.9% -50.3% 0.46 0.78
MU 22.4y +9.3% +19.7% -81.4% -90.9% 0.11 0.22
GOLD 13.5y +7.2% +7.7% -20.0% -35.0% 0.36 0.22
SPY 20.4y +4.4% +9.1% -40.5% -56.7% 0.11 0.16
INTC 20.4y +2.2% +8.5% -73.3% -74.2% 0.03 0.11
CAGR / maxDD is the column that settles it — return earned per unit of drawdown suffered. On that measure TURKS wins on 7 of 12. It cut maximum drawdown on 12 of 12, and beat buy-and-hold on raw return on 3.
▸ ETH — 117.3% against 71.9%, at −54.4% drawdown against −94.1%. Nearly double the return on barely half the pain.
▸ BTC — 70.0% against 54.2%, at −62.3% against −83.9%.
▸ AMD — 20.2% against 17.3%, turning a −96.1% hole into −69.3% across 21.4 years.
These are assets that spent their entire sample inside a historic bull market, measured against a benchmark paying no commission and no slippage. Halving a drawdown is ordinary. Halving it and finishing ahead is not.
BTCUSD 4h at the shipped defaults. The ladder is the green and red boxes; the envelope is the pair of curves around the mean. Bottom left is the BOOK panel reading 70.0% against 54.2% buy-and-hold at −62.3% drawdown against −83.9%, on 58.0% average exposure. Right side is the live state: what the rule targets now, where the next rung sells, where it buys back.
MU, SPY, TSLA and INTC are in that table because they were chosen to be difficult, and they behave exactly as the mechanism predicts. The rule sells strength and holds cash: it pays when a price path is violent relative to its drift, and it costs when the drift is high and the path is smooth. On a broad index it is the wrong tool — SPY 9.1% becomes 4.4%, and that number is in the table rather than left out of it.
📖 HOW TO USE IT
1 — Set your costs before you read anything. Commission ($ per order) and Typical position size ($) are the only two numbers the cost model needs; every other cost figure is a rate derived from them. A flat $1.50 is 1.9bp on an $8,000 position and 7.5bp on a $2,000 one. Leave these wrong and the panel lies to you.
2 — Pick the instrument. Single names and crypto whose drawdowns are violent relative to their drift. The table above is the guide, including the four rows that say don't.
3 — Read the ladder, not the arrows. The SELL / BUY ENGINE block prints three live numbers:
▸ Sell next above — the price at which the next rung comes off
▸ Buy back below — the price at which it goes back on
▸ Rungs sold — how much the envelope has already taken off, e.g. 12 of 20
Both prices exist now, before the move. They are not marks that appeared after one.
4 — Read the dial. The THE RULE block prints Target weight, which is what the rule says you should be holding at this instant, and Dial c / f. The POSITION block prints what you actually hold, your entry, your open return, and the round-trip cost you are currently carrying — so the gap between intention and position is always visible.
5 — Size it with c and f, not by fighting the rungs. c scales the whole position down. f is the floor you keep while the rule is off; raising it walks the book continuously toward buy-and-hold. Both tooltips print the measured frontier — the whole curve of what each step costs in return and buys in drawdown, including the region where the rule loses to simply holding less.
6 — Verify on your own symbol before trusting any of this. The BOOK panel prints Sample, CAGR against b&h, Max drawdown against b&h, CAGR/maxDD, Sharpe, Exposure and Turnover for whatever chart you are on, net of your own cost settings. Change the symbol and the whole table above regenerates for your instrument in one bar.
7 — Alerts. alert() messages ship on; JSON webhook format is a checkbox away.
🪜 HOW THE EXPOSURE IS SET
Exposure Shape picks the weighting rule. Ensemble 20/50/100/200 (graded) is the default: a slice is sold as the close drops below one more mean, bought back the same way, flat only below all four. Graded (continuous) uses one mean with an ATR ramp. Binary gate (legacy) is the original all-or-nothing rule.
Risk dial c scales the entire position down. Risk dial f is how much you keep while the rule is off. These two are the real levers, and nothing about their trade-off is hidden behind a paywall or a marketing claim — the full measured frontier is printed in the settings dialog.
Quantise Steps rounds the target to N reachable weights and requires price to clear 75% of a step before acting, so orders do not fire every bar. Ramp Width (xATR) sets how far above the mean price must travel to earn full size.
✂️ THE NADARAYA-WATSON SELL ENGINE
A trend weight cuts into weakness by construction, so it sells low: 59% of every unit the dial sells goes out below its own average cost, at 12.4 round trips a year. That is the flaw this block exists to fix. It replaces or constrains the sell side with a Gaussian kernel-regression envelope that only sells into genuine extension.
Sell Engine Mode — Dial, NWE-gated (default) keeps the dial's targets but forbids cutting while price sits below the smoother; it may still add. NWE band only turns the dial's sells off entirely. Dial + NWE (both cut) lets either one sell. Dial only leaves the envelope drawn but inert.
Sell Rungs is how much leaves on each upper-band cross: 1/N of the position. Going from 3 to 10 halved turnover, cut the share sold below basis from 16.7% to 8.9%, and pulled out-of-sample drawdown from −32.6% to −18.3%. It ships at 20, one step further along the same gradient; 10 is the last value with a formal table behind it.
Band Multiplier (3.0) and Buy-back Multiplier (2.5) set the upper and lower halfwidths in mean-absolute-deviation units. The asymmetry is the point: buying back nearer the mean than you sold restores the position before price has fully round-tripped, which is what keeps the overlay from bleeding in a chop. Bandwidth h widens and slows the smoother; it ships at 5.
🔬 HOW THIS WAS BUILT
Nine candidate signal families were tested against a matched-exposure control across 140 markets and 8,793 sessions: moving-average and momentum structure, cross-sectional relative strength, short-horizon mean reversion, volatility-of-volatility and regime transitions, drawdown state, volume, range compression, multi-timeframe agreement, and calendar seasonality. Not one was positive both in and out of sample. All nine were deleted from the codebase rather than left in as decoration.
The cleanest demonstration: take the original engine's own weight path and fire it 60 trading days late — same trades, same sizes, same turnover, same average exposure, only the dates broken. It scores better late than on time. Block-shuffling the path also beats it. A rule whose dates carry information cannot survive having them destroyed, so that engine was removed and what remains is geometry.
The stretch-proportional alternative to fixed rungs was then built and measured across 44 configurations. None beat rungs = 10. The project's pre-registered five-clause acceptance test passed all 20 graded cells — but a constant weight of 1.0 also passes three of five clauses, exactly one cell of twenty reaches p < 0.05 uncorrected (the null expectation for twenty tests), that p fails Bonferroni, and the cells are 0.985-correlated. It was reported as a failed test.
Everything left in this script survived a process designed to kill it. What remains is a sizing rule with no forecast in it: it does not predict the retest, it tells you at a price you can read now exactly what happens when one arrives.
⚙️ COSTS, AND THE SETTINGS THAT DECIDE THEM
Initial capital 150,000; commission $1.50 cash per order; no pyramiding; orders processed on bar close. Sell Engine Mode Dial, NWE-gated, Exposure Shape Ensemble 20/50/100/200 (graded), c = 1.00, f = 0.00, Quantise Steps 3, Ramp 1.0 ATR, Trend Mean 200, Cash Yield 0.00%. Envelope: bandwidth 5, multiplier 3.0, buy-back 2.5, MAE window 499, Sell Rungs 20.
TradingView's strategy() slippage is denominated in ticks, and a tick is an absolute price — one tick cannot be simultaneously correct for a $20 stock and a $1,600 one, nor for the same stock at $0.21 and at $224. It is therefore left at 0, and a proportional Slippage (xATR per side) input, shipped at 0.01, charges the cost in-script where it scales with the instrument.
Cash Yield ships at 0.00%. The rule spends much of its life partly in cash, so any yield credited lands straight on the CAGR, and one constant cannot represent a twenty-year sample where real cash paid about 0.1% for eight years and about 5% for two. Every figure in the table above was measured with it at zero.
Exits are close-only by construction — no strategy.exit, no stop=, no limit= anywhere in the shipped path, and nothing resting at a broker. The printed ladder is the memoryless level; the live quantiser is hysteretic, so the executed switch can sit up to 0.75 steps from the printed one.
© CREDIT
The envelope is a port of "Nadaraya-Watson Envelope " by LuxAlgo (www.tradingview.com), published open-source under CC BY-NC-SA 4.0. The kernel, the MAE band construction and the crossover logic are theirs. This script is published under the same licence.
Only the non-repainting, one-sided causal branch was ported. LuxAlgo's script defaults to the repainting branch, which rebuilds its curve inside barstate.islast with a two-sided kernel, so the value at bar i averages bars on both sides of i — including bars that had not happened when i closed. That branch is deliberately absent here. The measured gap between the two is about 21% of the band halfwidth, which is why the repainting version's arrows look cleaner than any live rule can be. The sizing, the rung logic and the position accounting are new.
Strategy

Drawdown [WynTrader]Drawdown
Hello my friend
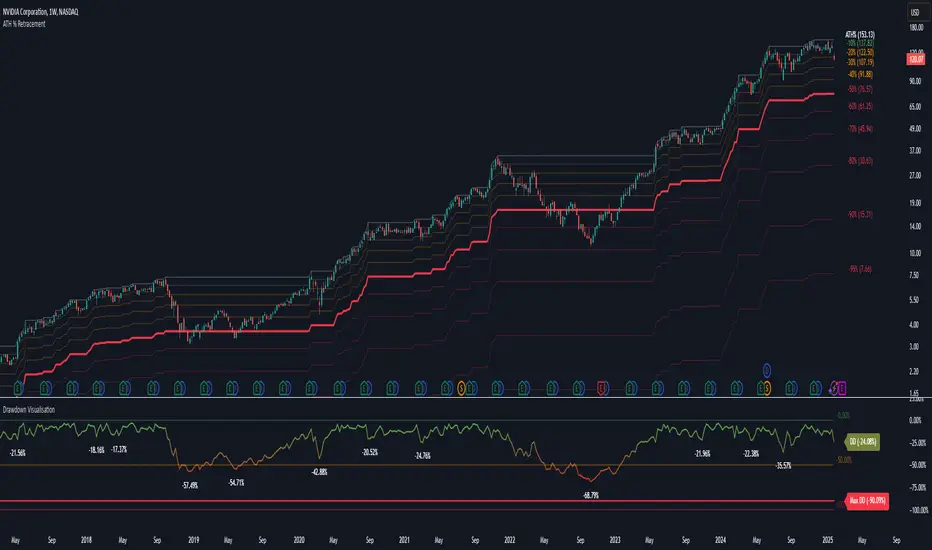
Before trading an unfamiliar asset, it's worth seeing how it survived its toughest moments — including major market crashes. This indicator reveals every significant decline a security has experienced: how far it dropped, and how long it took. Seeing a past drawdown of -54% over 13 months makes the next correction far less intimidating.
Use it to measure real risk, set realistic expectations, and trade with more confidence.
█ CONCEPTS
A drawdown is the decline from a price peak to the lowest point that follows. The indicator automatically detects every peak and trough, filtering out noise to keep only declines at or above your chosen threshold (default: 20%).
█ FEATURES
Threshold — Set the minimum decline to display, so only meaningful crashes appear.
Boxes & Labels — Each drawdown is highlighted on the chart from peak to trough, labeled with its duration and amplitude (e.g., 13M -54%).
History Table — Lists every recorded drawdown with start/end dates, span, and decline %. Sortable and adjustable in size.
█ CONCLUSION
Before investing, check an asset's drawdown history: how deep, how long, did it recover? These questions reveal its true volatility and resilience. A chart without this history tells only half the story.
█ WYNTRADER
I'm not a Pine Script programmer — just a trader building tools for my own analysis. A few rough edges may remain. Enjoy!
WynTrader Indicator

Trailing Drawdown Line Futures PropFirmsSee the exact price where your trailing drawdown gets hit — before it happens.
Built for futures prop-firm traders (Apex, Topstep, MyFundedFutures, Tradeify, BluSky and similar). Enter your firm's trailing DD size, your buffer at entry and your contract count, then click your entry point on the chart. The indicator draws your liquidation line — the price where the account would breach the trailing max drawdown — and ratchets it the way the firm actually does: it trails the implied equity peak at the FULL drawdown distance, and if you enter below your prior peak the line starts closer but does not move until price beats that peak.
Features
• Works on any futures symbol automatically — the contract's point value is read from the symbol (ES, NQ, MNQ, MES, GC, CL, ZB, …). Non-USD contracts (e.g. FDAX) display in their quote currency.
• Three trailing models: Intraday (trails every new high/low — real-time-trailing firms), Bar close, and End of day (EOD-trailing firms; needs an intraday or 1D chart).
• Live buffer readout — dollars and points left before the line — in a dark info table and an on-chart label.
• Breach is latched: once the line is touched the status stays BREACHED, because a trailing max-DD hit is terminal, not a temporary state. On historical bars the intraday model errs toward flagging (the path inside a bar is unknowable) — confirm on a lower timeframe.
• Lock support: enter the price where your firm freezes the DD (breakeven lock), or let the script derive it from your start balance + equity at entry. Status flips to LOCKED.
• Exit time: set it when you close the trade — the line and buffer freeze, because real DD levels stop moving while you're flat.
• Two alert conditions: buffer below warning level, and line touched.
How to use: add to chart → click your entry point → set contracts, firm DD size and buffer at entry (from your firm dashboard) → pick the trailing model that matches your firm → optionally create the two alerts. Re-anchor for every new trade.
Honest limitations: models ONE fixed-size position on THIS symbol. Scaling in/out or holding other instruments changes your real equity path and is not modeled. Anchor on a low timeframe (1–5 min) for precision. Educational risk-visualization tool — always confirm your firm's exact drawdown rule on their own site. Indicator

Prop Firm Risk Guard I EonMetrics Prop Firm Risk Guard
Prop Firm Risk Guard is a risk dashboard and position size calculator for prop firm challenge and funded-account traders. It keeps the numbers that decide whether your account survives — the Daily Loss Limit, the Max Drawdown floor and the size of your next trade — on one screen, derived from one shared account state.
Stated plainly up front: TradingView cannot see your broker account. Your balance and today's P&L are MANUAL inputs — you type them in, the script does the limit math and the sizing math. Entry, Stop and Take Profit are also yours: the script never calculates or suggests any of them, it only draws the levels you decided on and does the arithmetic. The only live, price-driven element is the Entry/SL/TP lines and their cross alerts. No signals, no trade suggestions.
🔶 WHY ONE SCRIPT
A challenge usually fails through one compounding mistake: a trade sized without checking how much of today's loss allowance is actually left, so a routine stop-out becomes a daily breach. That check only works when the daily limit, the drawdown floor and the position size are computed from the same account state at the same moment — which is why they are one dashboard instead of separate tools you would have to cross-reference by hand. The last sizing row makes the link explicit: it compares one full stop-out against your remaining daily room and turns red BEFORE the trade if it doesn't fit.
🔶 WHAT IT DOES
Daily Loss Limit — enter your firm's daily loss % and its basis (starting or current balance). Today's P&L is a NET number, wins offset losses. Because firms word this rule two ways, both models are supported: Floor (the day has a fixed equity floor, so intraday profit adds room before it — the common model) and Hard Cap (the allowed loss is fixed, profit does not extend it). The table shows the remaining allowance in money and a status ladder: OK → CAUTION (50% used) → DANGER (80%) → BREACHED.
Max Drawdown — Static (floor fixed below the starting balance) or Trailing (floor follows the equity high-water mark). Shows the floor as an actual money level and the buffer above it, with the same status ladder.
Position sizing — risk per trade as % of balance or a fixed amount, planned entry (or live price) and stop. Returns the size in units, the forex conversion to 100k lots and the notional value. A Contract Multiplier input keeps the math correct on futures (e.g. ES = 50, GC = 100) as well as stocks, crypto and forex.
Take Profit (optional) — add your own TP price to see the R:R ratio and the money gain if it hits, using the same calculated size. If the TP sits on the wrong side of entry for your direction, the cell flags it instead of showing a meaningless ratio.
Entry / SL / TP lines — your levels drawn on the chart, with three alert conditions that fire when price crosses any of them.
🔶 HOW TO USE
1. Settings → Account: starting balance, current balance; high-water mark for trailing-drawdown firms (0 = auto).
2. Prop Firm Rules: copy the exact numbers and models from your firm's dashboard.
3. During the session, keep Today's P&L updated — the daily section only knows what you tell it.
4. Before a trade: set risk, entry and stop; read the size; make sure the last row is not red.
5. Optional: add a TP for R:R, and set alerts on the three price-cross conditions.
🔶 SETTINGS
Account (balances, high-water mark) · Prop Firm Rules (daily loss % + basis + Floor/Hard Cap, max drawdown % + Static/Trailing, profit target) · Today's P&L · Position Sizing (risk mode, entry/stop/TP, contract multiplier, lines toggle) · Table (position, text size).
This tool does the arithmetic of your firm's rules and your own trade plan. It does not know your account, does not predict anything and does not tell you what to trade.
Part of the EonMetrics toolset.
Indicator

Indicator

Market Regime & Risk DashboardAn analytics and risk dashboard. It tells you what state the market is in and how much to risk. It does NOT generate buy or sell signals and makes no claim of edge.
What it shows
- Volatility regime: realized volatility bucketed by its own percentile history (Low / Normal / High / Extreme)
- Realized volatility and its percentile rank
- Trend regime: Kaufman Efficiency Ratio bucketed into Trending / Mixed / Choppy
- ATR % of price, an ATR-based stop distance, and a fixed-fractional position size for your chosen risk percent
- Drawdown from the recent high
How to read it
Volatility regime drives position sizing: in Extreme regimes the same percent risk implies a far smaller position, and the dashboard does that maths for you. The trend regime is descriptive, not predictive.
Honest by design
- No buy/sell signals, no alpha claim. This is a measurement tool, not a prediction.
- Non-repainting: every value is a function of confirmed closes, no request.security, no future data. The current forming bar updates in real time, which is normal, not historical repaint.
- Every number is defined, with its limitations stated.
Open-source and MIT licensed.
Disclaimer: impersonal educational and analytics tool. This is not investment advice, not a personalised recommendation, and carries no performance guarantee. Past results do not predict future results. You are solely responsible for your own trading decisions. Indicator

XRS Prop Drawdown Recovery DashboardXRS Prop Drawdown Recovery Dashboard
The XRS Drawdown Recovery Dashboard is a risk management and trade planning tool designed to help traders create a structured recovery plan after experiencing drawdown in a funded account, prop firm account, or personal trading account.
Instead of increasing position size and attempting to recover losses through aggressive trading, this dashboard focuses on preserving remaining drawdown while using asymmetric risk-to-reward ratios, limited trade counts, and disciplined risk management to improve the probability of long-term account survival.
## How It Works
Select:
* Account Size
* Total Drawdown Allowance
* Remaining Drawdown
* Recovery Speed (Conservative, Balanced, or Aggressive)
The dashboard automatically calculates a dynamic recovery plan based on the amount of drawdown remaining.
The recovery engine adjusts:
* Suggested position size
* Risk per trade
* Maximum trades per day
* Stop loss distance
* Take profit distance
* Risk-to-reward ratio
* Daily loss limit
* Recovery targets
* Trading rules based on account condition
As drawdown becomes more severe, the dashboard automatically shifts into more defensive recovery modes and recommends tighter risk controls, fewer trades, and larger reward-to-risk requirements.
## Recovery Philosophy
Most traders fail recovery attempts because they increase risk as drawdown increases.
This dashboard follows the opposite approach:
* Risk decreases as drawdown increases.
* Trade frequency decreases as drawdown increases.
* Required reward-to-risk ratios increase as drawdown increases.
* Capital preservation becomes the primary objective.
The goal is not to recover losses as quickly as possible.
The goal is to recover losses while maximizing account survival.
## Recovery States
### Survival
Designed for accounts with very little drawdown remaining.
Focus:
* Smallest position sizes
* Highest reward-to-risk ratios
* One high-quality trade opportunity
* Strict capital preservation
### Critical
For accounts approaching dangerous drawdown levels.
Focus:
* Reduced trade frequency
* Limited daily exposure
* High-quality A+ setups only
### Defensive
For moderate drawdown situations.
Focus:
* Controlled risk
* Selective entries
* Balanced recovery pace
### Controlled
For healthier account conditions where recovery remains important.
Focus:
* Moderate risk allocation
* Multiple opportunities
* Consistent execution
### Normal
For accounts with substantial drawdown available.
Focus:
* Standard risk management
* Consistent process
* Controlled growth
## Suggested Usage
This tool works best when combined with:
* A proven trading strategy
* Consistent trade execution
* Defined stop losses
* Positive expectancy setups
* Strict adherence to daily loss limits
The dashboard is intended to provide a framework for disciplined decision-making and should not be used as a replacement for a complete trading plan.
## Key Features
✔ Dynamic recovery engine
✔ Position size recommendations
✔ Risk-per-trade calculations
✔ Daily loss limits
✔ Recovery state detection
✔ Maximum trade count suggestions
✔ Recovery speed adjustment
✔ Reward-to-risk optimization
✔ Drawdown management framework
## Educational Disclaimer
This indicator is provided for educational and informational purposes only.
Nothing contained within this indicator, its calculations, suggestions, or displayed recovery plans should be considered financial advice, investment advice, trading advice, or a recommendation to buy or sell any financial instrument.
Trading futures, stocks, options, forex, cryptocurrencies, and other financial products involves substantial risk and may result in significant losses, including the loss of your entire account balance.
Past performance does not guarantee future results.
All trading decisions are made solely at your own discretion and risk. You are responsible for evaluating your own financial situation, risk tolerance, and trading objectives before placing any trade.
The creator of this indicator assumes no responsibility for any trading losses, missed opportunities, or financial damages resulting from the use of this tool.
Indicator

Campaign Map - Contreras Law Version en espanol mas abajo. · English version first, Spanish below.
─────────────────────────────────
CAMPAIGN MAP — CONTRERAS' LAW
WHAT IT MEASURES
This indicator builds the historical distribution of a symbol's
campaign corrections (peak→trough declines confirmed by reversal) and
places the CURRENT correction inside that map: is it normal breathing,
a deep pullback, or statistically unusual territory?
THE OBSERVATION BEHIND IT
Contreras' Law (Jacinto Contreras, June 2026): in US large-cap
technology stocks, the typical depth of campaign corrections converges
to a structural constant (~14-15% median at campaign scale),
regardless of the symbol. What differentiates each stock is not its
median but its historical maximum tail (observed: from ~25% to ~53%
depending on the symbol, across ~11 years of hourly data on 9 names).
Operational takeaway: MONITOR WITH THE MEDIAN, SIZE WITH THE TAIL.
HOW IT WORKS
· A reversal-threshold zigzag detects campaign peaks and troughs.
· Only COMPLETED corrections (confirmed by reversal) enter the
statistics: median, 75th percentile, and historical maximum.
· The main line plots the depth of the ongoing correction, colored by
zone: normal (teal), deep (orange), unusual (red).
· Summary table with the symbol's map and current status.
· Two alerts: median cross and P75 cross.
HOW TO USE IT
· Below the median: normal breathing; the pullback alone carries no
trend-change information.
· Between median and P75: deep but normal correction.
· Above P75: statistically unusual territory. The correct reading is
NOT "it must bounce now" — it is: look for exhaustion evidence
(divergences, capitulation) and demand confirmation.
· The historical maximum (the tail) is the worst-case reference for
position sizing and campaign stops.
INPUTS
· Reversal (%): rally confirming the end of a bearish campaign.
8% = campaign scale (default). 3% = swing scale.
· Minimum depth (%): smaller corrections are excluded from the map.
10% campaign / 5% swing.
LIMITATIONS (read before use)
· Statistics do NOT repaint (completed corrections only), but the
ONGOING correction is provisional by nature: its campaign peak may
extend until the reversal confirms.
· The median convergence was observed in US large-cap tech on the
hourly timeframe; it may not hold in other sectors, assets or
timeframes. Verify it on your symbol before relying on it.
· Enough campaigns (>8-10) are required for the map to be
statistically meaningful; the indicator shows "calibrating…" until
then.
· This is a MEASUREMENT and context tool. It does not generate buy or
sell signals and guarantees no outcome. Not financial advice.
─────────────────────────────────
VERSIÓN EN ESPAÑOL
MAPA DE CAMPAÑAS — LEY DE CONTRERAS
QUÉ MIDE
Este indicador construye la distribución histórica de las correcciones
de campaña de un valor (caídas máximo→mínimo confirmadas por reversión)
y sitúa la corrección actual dentro de ese mapa: ¿es una respiración
normal, una corrección profunda o territorio inusual?
LA OBSERVACIÓN QUE LO ORIGINA
Ley de Contreras (Jacinto Contreras, junio de 2026): en valores
tecnológicos estadounidenses de alta capitalización, la profundidad
típica de las correcciones de campaña converge en una constante
estructural (~14-15% de mediana, escala campaña), independiente del
símbolo. Lo que diferencia a cada valor no es su mediana, sino su cola
máxima histórica (observado: desde ~25% hasta ~53% según el símbolo,
sobre ~11 años de datos horarios en 9 valores).
Moraleja operativa: VIGILAR CON LA MEDIANA, DIMENSIONAR CON LA COLA.
CÓMO FUNCIONA
· Un zigzag por umbral de reversión detecta picos y valles de campaña.
· Solo las correcciones COMPLETADAS (confirmadas por reversión) entran
en la estadística: mediana, percentil 75 y máximo histórico.
· La línea principal muestra la profundidad de la corrección en curso,
coloreada según la zona: normal (verde), profunda (naranja),
inusual (rojo).
· Tabla resumen con el mapa del símbolo y el estado actual.
· Dos alertas: cruce de la mediana y cruce del P75.
CÓMO USARLO
· Por debajo de la mediana: respiración normal; el retroceso no es,
por sí solo, información de cambio de tendencia.
· Entre mediana y P75: corrección profunda pero dentro de lo normal.
· Por encima del P75: territorio estadísticamente inusual. La lectura
correcta no es "ya tiene que rebotar", sino: buscar señales de
agotamiento (divergencias, capitulación) y exigir confirmación.
· El máximo histórico (la cola) es la referencia de peor caso para
dimensionar posición y stops de campaña.
PARÁMETROS
· Reversión (%): rally que confirma el fin de una campaña bajista.
8% = escala campaña (por defecto). 3% = escala swing.
· Profundidad mínima (%): correcciones menores no entran al mapa.
10% campaña / 5% swing.
LIMITACIONES (léelas antes de usar)
· Las estadísticas NO repintan (solo correcciones completadas), pero
la corrección EN CURSO es provisional por naturaleza: su máximo de
campaña puede extenderse hasta que la reversión confirme.
· La convergencia de medianas está observada en tecnológicas USA de
alta capitalización en marco horario; en otros sectores, activos o
marcos puede no cumplirse. Compruébalo en tu símbolo antes de usarlo.
· Se necesitan suficientes campañas (>8-10) para que el mapa tenga
valor estadístico; el indicador muestra "calibrando…" mientras tanto.
· Es una herramienta de MEDICIÓN y contexto. No genera señales de
compra/venta ni garantiza resultado alguno. No es asesoramiento
financiero. Indicator

Prop Firm Shield - Challenger [Quiet Edge]Your prop firm's rules, enforced at the chart. Prop Firm Shield tracks your daily-loss budget, drawdown buffer, and position size in real time — so the limit is visible the moment you are near it.
This is the Challenger tier — free, no login required. Enter your account size, starting balance, and current balance. The dashboard does the rest.
What it tracks
Daily loss budget — how much you have left, in dollars and percent
Drawdown buffer — remaining room before breach
Position size calculator — enter entry, stop, and risk % to get a recommended lot size
SAFE / CAUTION / STOP status with chart background alert
Upgrade to Operator ($19/mo) for verified firm presets (FTMO, Topstep, The5ers, MyFundedFutures), trailing drawdown, consistency rule tracker, and session close countdown.
Upgrade to Principal ($39/mo) for lot size escalation guard and an Evaluation vs Funded phase toggle — the only on-chart tool that models intraday trailing drawdown for funded accounts.
quietedgelabs.com/indicators/risk-management/prop-firm-shield Indicator

Xer0's Dual Engine Ladder AllocatorOverview
This indicator is designed for long-term investors using a "Dual Engine" portfolio strategy on M1 Finance — mixing a broad-market index fund with a leveraged counterpart in the same Pie. Instead of guessing when to buy the dip, this script provides a systematic, step-by-step roadmap for increasing your leveraged allocation as the market falls, and resetting it as the market recovers.
How It Works
The strategy is built on "Sticky All-Time High" logic. It tracks the highest close price and calculates the current drawdown from that peak, then responds with one of three scenarios:
Ladder Down (Risk On): For every defined drop step (e.g. every -5%), the indicator signals a RISK UP event — automatically calculating your new target allocation to the leveraged slice of your Pie. This forces systematic, disciplined buying at lower prices.
Recovery Reset (Risk Off): Once the market recovers by a set percentage from the bottom, the script signals a RESET — returning your allocation to the base level and locking in the gains from the dip-buying phase.
Bull Step: When the market pushes into new high territory, the script tracks each new leg up and keeps your reference point current.
Key Features
Sticky ATH Tracking: Automatically calculates true drawdown from the cycle peak
Customizable Ladder Steps: Define your own drop trigger percentage and leverage increase per step
Max Cap: Hard ceiling on leverage exposure to protect against catastrophic drawdowns
Bar Confirmation: All signals fire on daily close to avoid intraday false triggers
Visual Dashboard: Bottom-right table showing current mode, target leverage, drawdown, and recovery price target
Alert Conditions: Built-in RISK UP and RESET alerts compatible with TradingView's "Once Per Bar Close" setting
Backtested Performance (Simulated — Read Carefully)
The following results are from a Python backtest covering approximately 30 years (1996–2026), using $923/week in contributions every Friday. The strategy used two M1 Pies: Pie 1 (S&P 500 index fund / 3× S&P 500 ETF, base leverage 35%) and Pie 2 (Nasdaq-100 index fund / 3× Nasdaq-100 ETF, base leverage 25%). Tax assumptions reflect California state + federal rates for a $47K–$100K income bracket. Data prior to 2010 is synthetic, modeled from underlying index returns.
Results are hypothetical and do not represent actual trading. Past performance does not guarantee future results.
Ladder Strategy | VOO Benchmark
Total Contributed $1,395,576 | $1,395,576
Final Value (after-tax) $25,286,879 | $9,025,443
Total Return 1,711.9% | 546.7%
CAGR (on contributions) 10.1% | 6.4%
Max Drawdown -91.8% | -50.5%
Taxes Paid (CA) $5,358,907 | N/A (buy & hold)
Cash After Full Liquidation $23,500,189 | $7,171,385
The ladder strategy produced approximately 227.7% more after-tax cash than buy-and-hold VOO after full liquidation. However, the strategy experienced a maximum drawdown of -91.8% — meaning at its worst point, the portfolio lost nearly all of its value on paper. This level of volatility is not suitable for most investors and requires strong conviction and a long time horizon to hold through.
How to Use
Add this indicator to a Daily (1D) chart of your chosen index. Configure the inputs to match your risk tolerance — Base Leverage %, Drop Step %, and Max Cap %. Enter your M1 Pie name in the input field so alerts reference it by name. Set alerts using "Once Per Bar Close" and adjust your Pie allocation whenever a signal fires.
Disclaimer
This script is for informational and educational purposes only. It does not constitute financial advice. Backtested results are simulated and hypothetical — they do not account for all real-world frictions and should not be interpreted as a guarantee of future performance. Trading leveraged instruments involves significant risk, including the potential loss of your entire investment, and is not suitable for all investors. Indicator

Risk Management Calculator [tradeviZion]Risk Management Calculator - Script Description
📖 Overview
The Risk Management Calculator helps you find the optimal risk per trade based on your strategy's win rate, risk-to-reward ratio, and your tolerance for drawdowns and blowout risk. Instead of guessing a fixed 1–2%, it uses established formulas (Edge, Kelly criterion, and Risk of Ruin) to suggest a risk % that balances growth with survival.
Designed for swing traders, day traders, and systematic traders who want to size positions mathematically rather than by rule of thumb.
One risk % does not fit all. Your edge and tolerance for consecutive losses determine the best risk per trade.
Edge & Kelly - Computes your strategy edge and Full/Half/Quarter Kelly fractions
Risk of Ruin - Shows blowout probability at 1% to 10% risk, or solves for max risk given your target RoR
Consecutive Losses - Probability P(k) and drawdown at k losses for your chosen k values
Consecutive Losses Cone - Visual pane with P(k) and DD curves (2%, 3%, 5%, Rec, Max DD), k marker (vertical line + dot), best risk % for your selected k. Labels on curves; hover for tooltips. Optional legend in table.
---
⚙️ How It Works
⚪ Edge
Your edge is the expected value per unit risked. Positive edge means the strategy is profitable in expectation.
Edge = winRate × R:R − lossRate
Example: 30% win rate, 1:3 R:R → Edge = 0.30×3 − 0.70 = 0.20 (positive expectancy).
⚪ Risk of Ruin
The probability of losing your entire account. The formula uses your edge and risk fraction:
RoR ≈ ((1 − edge) / (1 + edge))^(1 / r)
where r is risk per trade. Assumes a long series of independent bets with stable edge. Lower risk per trade reduces RoR. Doubling risk increases RoR more than linearly. Approximation; may break down with skewed returns or finite horizons.
⚪ Kelly Criterion
The Kelly fraction maximizes long-run geometric growth. Full Kelly is often too aggressive; Half or Quarter Kelly is commonly used.
Full Kelly = (R:R × winRate − lossRate) / R:R
⚪ Consecutive Losses
Probability of k losses in a row:
P(k) = (1 − winRate)^k
Drawdown after k losses:
DD(k) = 1 − (1 − risk)^k
⚪ Best Risk
In Solve mode, the script finds the maximum risk % such that RoR ≤ your target. The Consecutive Losses Cone also computes a best risk % that keeps drawdown at your selected k within your Cone Max DD % limit, and uses the stricter of the two.
---
🎯 How to Use
Add the indicator to your chart (any symbol; it uses inputs only)
Enter your Account Capital , Win Rate % , and Risk-to-Reward Ratio from your backtest or live stats
Choose Mode : Solve for max risk % to get recommended risk, or Show RoR for given risk % to analyze a specific risk level
Review the Summary (Edge, Kelly, Recommended risk, Risk amount) and RoR Comparison table
Check the Consecutive Losses section to see P(k) and drawdown at your k values
Use the Probability Cone to visualize curves and the best risk % for your Cone Risk Marker k and Cone Max DD % . Hover cone labels for tooltips. Enable Cone Legend for a table legend.
---
⚙️ Settings
Core Parameters
Account Capital - Your trading capital. Used to show risk amount in dollars (e.g., 2% = $200 on $10,000).
Win Rate % - Percentage of winning trades (e.g., 30 = 30% winners, 70% losers).
Risk-to-Reward Ratio - Profit per unit risk (e.g., 3 = 1:3 R:R).
Target RoR % - Maximum acceptable Risk of Ruin. Lower = safer. Used when Mode is Solve for max risk % .
Target RoR Mode
Mode - Solve for max risk % : finds max risk within Target RoR. Show RoR for given risk % : shows RoR at Reference Risk %.
Reference Risk % - Risk % to analyze when Mode is Show RoR .
Consecutive Losses
k₁ to k₅ - Number of consecutive losses to analyze. Example: k₁=5 shows P(5) and drawdown at 5 losses in a row.
Table Settings
Color Theme - Dark, Light, Ocean Blue, Forest Green, etc.
Table Text Size - Tiny, Small, Normal, Large.
Tables Position - Left, Middle, or Right. All three tables stack vertically: Risk Management Calculator (top), Consecutive Losses Cone (middle), Consecutive Losses (bottom).
Display
Summary - Edge, Kelly, Recommended risk, Risk amount.
RoR Comparison - RoR at 1%, 2%, 3%, 5%, 7%, 10%.
Consecutive Losses - P(k) and DD table for k₁–k₅.
Probability Cone - P(k) and DD curves in a separate pane.
Cone Max k - Max consecutive losses on cone x-axis (20–100).
Cone Risk Marker k - k value highlighted with vertical line and dot.
Cone Max DD % - Max acceptable drawdown at marker k. Best risk respects this limit.
Cone Legend - Optional legend in the cone table (P(k) curve, DD curves, Rec%, best risk, k marker). Hover chart labels for the same info.
P(k) Color, DD Color, DD Rec% Color - Colors for cone curves. DD Rec% also used for best risk curve when RoR-limited (green); theme color when DD-limited.
---
⚠️ Disclaimer
This indicator is for educational and informational purposes only . It does not constitute investment advice. Past performance and backtested statistics do not guarantee future results. The RoR formula is an approximation and may not hold under skewed returns or finite horizons. Always do your own research and consider consulting a qualified financial advisor before trading.
Indicator

Indicator

Risk Command CenterRisk Command Center
Concept & Philosophy Trading psychology is the hardest edge to master. The "Risk Command Center" is designed to act as a visual accountability partner for day traders. It tackles the common problem of "Tilt" (emotional trading) by forcing you to confront your P&L and Risk Limits visually before you reach a breaking point.
Unlike automated trackers, this tool relies on Manual Accountability. By manually inputting your P&L after every trade, you engage your prefrontal cortex (logic), breaking the "trance" of emotional trading. This script visualizes your Daily Loss Limit not as a number, but as "Ammo"—a resource bar that depletes as you take risks.
Key Features
Visual Risk Bar: A health-bar style display that fills up as you approach your Max Daily Loss.
Adaptive Environment: The chart background changes color subtly (Yellow -> Orange -> Red) as your risk increases, giving you subconscious cues to slow down.
The "Tilt Guard": If you breach your Max Loss limit or hit your max "Consecutive Loss" streak, the screen locks down with a "TRADING STOPPED" enforcement label.
Session Timer: Automatically greys out the dashboard and background when the market session is closed, helping you avoid low-probability trading hours.
Strike Counter: Tracks consecutive losses to prevent "revenge trading" spirals.
How It Works This indicator does not connect to your broker (Pine Script security limitation). It operates as a Heads-Up Display (HUD) that you control:
Input: You set your Max Daily Loss (e.g., $500).
Process: As you trade, you update your Current Session P&L in the settings.
Calculation: The script calculates your % Risk Used and updates the dashboard.
Alerts: If Net P&L <= -Max Limit OR Consecutive Losses >= Max Streak, the visual alarms trigger.
How to Use This Tool
Pre-Market: Open the settings and define your Max Daily Loss Limit (e.g., $600) and Allowed Trading Session (e.g., 0930-1600).
During Trading: Keep the settings window accessible. After every closed trade, type your P&L into the Current Session P&L field.
Example: If you lose $150, type -150. If you win $300 next, change it to +150 (net).
Monitoring: Watch the "Ammo Left" and the "Risk Level" bar.
Green: Safe Zone.
Orange: Caution (75% of limit used).
Red: Breach. Walk away.
Settings Breakdown
Max Daily Loss Limit: Your hard stop for the day.
Current Session P&L: The input field for your running total.
Max Consecutive Losses: The number of losses in a row allowed before a forced break.
Allowed Trading Session: The time window where the dashboard is "Active." Outside this window, it shows "CLOSED."
Disclaimer This tool is for educational and risk-management purposes only. It cannot physically prevent you from placing trades on your broker. It is a visual aid to support disciplined trading habits. Indicator

Indicator

Risk Distribution HistogramStatistical risk visualization and analysis tool for any ticker 📊
The Risk Distribution Histogram visualizes the statistical distribution of different risk metrics for any financial instrument. It converts risk data into histograms with quartile-based color coding, so that traders can understand their risk, tail-risks, exposure patterns and make data-driven decisions based on empirical evidence rather than assumptions.
The indicator supports multiple risk calculation methods, each designed for different aspects of market analysis, from general volatility assessment to tail risk analysis.
Risk Measurement Methods
Standard Deviation
Captures raw daily price volatility by measuring the dispersion of price movements. Ideal for understanding overall market conditions and timing volatility-based strategies.
Use case: Options trading and volatility analysis.
Average True Range (ATR)
Measures true range as a percentage of price, accounting for gaps and limit moves. Valuable for position sizing across different price levels.
Use case: Position sizing and stop-loss placement.
The chart above illustrates how ATR statistical distribution can be used by looking at the ATR % of price distribution. For example, 90% of the movements are below 5%.
Downside Deviation
Only considers negative price movements, making it ideal for checking downside risk and capital protection rather than capturing upside volatility.
Use case: Downside protection strategies and stop losses.
Drawdown Analysis
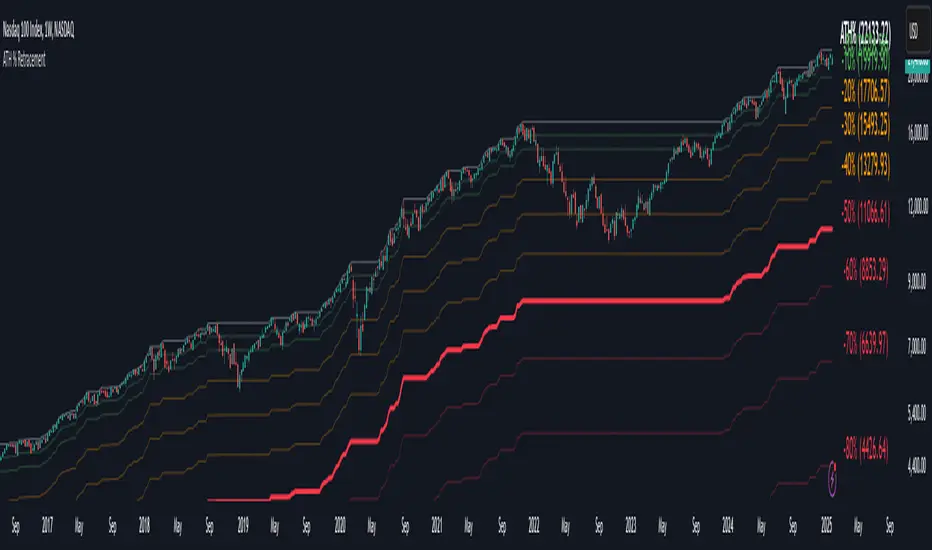
Tracks peak-to-trough declines, providing insight into maximum loss potential during different market conditions.
Use case: Risk management and capital preservation.
The chart above illustrates tale risk for the asset (TQQQ), showing that it is possible to have drawdowns higher than 20%.
Entropy-Based Risk (EVaR)
Uses information theory to quantify market uncertainty. Higher entropy values indicate more unpredictable price action, valuable for detecting regime changes.
Use case: Advanced risk modeling and tail-risk.
VIX Histogram
Incorporates the market's fear index directly into analysis, showing how current volatility expectations compare to historical patterns. The CAPITALCOM:VIX histogram is independent from the ticker on the chart.
Use case: Volatility trading and market timing.
Visual Features
The histogram uses quartile-based color coding that immediately shows where current risk levels stand relative to historical patterns:
Green (Q1): Low Risk (0-25th percentile)
Yellow (Q2): Medium-Low Risk (25-50th percentile)
Orange (Q3): Medium-High Risk (50-75th percentile)
Red (Q4): High Risk (75-100th percentile)
The data table provides detailed statistics, including:
Count Distribution: Historical observations in each bin
PMF: Percentage probability for each risk level
CDF: Cumulative probability up to each level
Current Risk Marker: Shows your current position in the distribution
Trading Applications
When current risk falls into upper quartiles (Q3 or Q4), it signals conditions are riskier than 50-75% of historical observations. This guides position sizing and portfolio adjustments.
Key applications:
Position sizing based on empirical risk distributions
Monitoring risk regime changes over time
Comparing risk patterns across timeframes
Risk distribution analysis improves trade timing by identifying when market conditions favor specific strategies.
Enter positions during low-risk periods (Q1)
Reduce exposure in high-risk periods (Q4)
Use percentile rankings for dynamic stop-loss placement
Time volatility strategies using distribution patterns
Detect regime shifts through distribution changes
Compare current conditions to historical benchmarks
Identify outlier events in tail regions
Validate quantitative models with empirical data
Configuration Options
Data Collection
Lookback Period: Control amount of historical data analyzed
Date Range Filtering: Focus on specific market periods
Sample Size Validation: Automatic reliability warnings
Histogram Customization
Bin Count: 10-50 bins for different detail levels
Auto/Manual Bin Width: Optimize for your data range
Visual Preferences: Custom colors and font sizes
Implementation Guide
Start with Standard Deviation on daily charts for the most intuitive introduction to distribution-based risk analysis.
Method Selection: Begin with Standard Deviation
Setup: Use daily charts with 20-30 bins
Interpretation: Focus on quartile transitions as signals
Monitoring: Track distribution changes for regime detection
The tool provides comprehensive statistics including mean, standard deviation, quartiles, and current position metrics like Z-score and percentile ranking.
Enjoy, and please let me know your feedback! 😊🥂 Indicator

Strategy

Indicator

Indicator

Strategy

Indicator

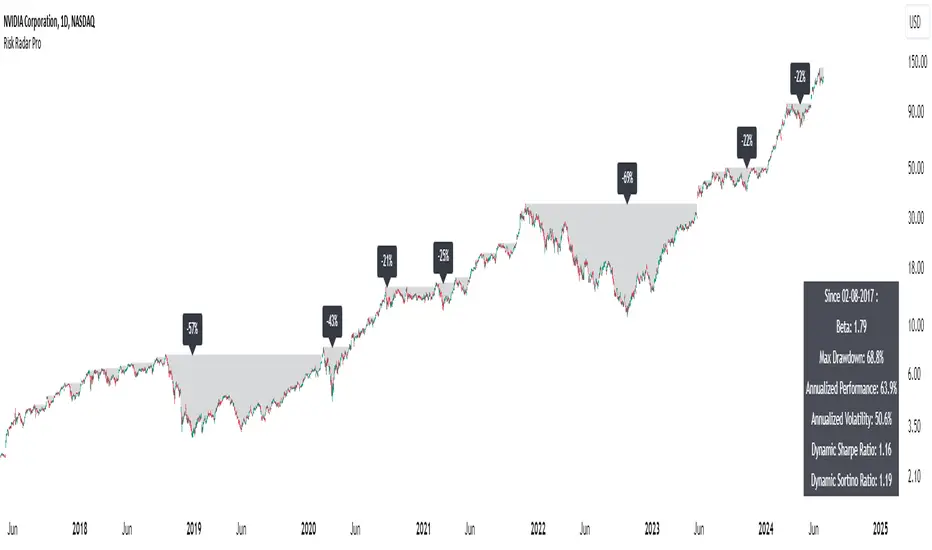
Risk Radar ProThe "Risk Radar Pro" indicator is a sophisticated tool designed to help investors and traders assess the risk and performance of their investments over a specified period. This presentation will explain each component of the indicator, how to interpret the results, and the advantages compared to traditional metrics.
The "Risk Radar Pro" indicator includes several key metrics:
● Beta
● Maximum Drawdown
● Compound Annual Growth Rate (CAGR)
● Annualized Volatility
● Dynamic Sharpe Ratio
● Dynamic Sortino Ratio
Each of these metrics is dynamically calculated using data from the entire selected period, providing a more adaptive and accurate measure of performance and risk.
1. Start Date
● Description: The date from which the calculations begin.
● Interpretation: This allows the user to set a specific period for analysis, ensuring that all metrics reflect the performance from this point onward.
2. Beta
● Description: Beta measures the volatility or systematic risk of the instrument relative to a reference index (e.g., SPY).
● Interpretation: A beta of 1 indicates that the instrument moves with the market. A beta greater than 1 indicates more volatility than the market, while a beta less than 1 indicates less volatility.
● Advantages: Unlike classic beta, which typically uses fixed historical intervals, this dynamic beta adjusts to market changes over the entire selected period, providing a more responsive measure.
3. Maximum Drawdown
● Description: The maximum observed loss from a peak to a trough before a new peak is achieved.
● Interpretation: This shows the largest single drop in value during the specified period. It is a critical measure of downside risk.
● Advantages: By tracking the maximum drawdown dynamically, the indicator can provide timely alerts when significant losses occur, allowing for better risk management.
4. Annualized Performance
● Description: The mean annual growth rate of the investment over the specified period.
● Interpretation: The Annualized Performance represents the smoothed annual rate at which the investment would have grown if it had grown at a steady rate.
● Advantages: This dynamic calculation reflects the actual long-term growth trend of the investment rather than relying on a fixed time frame.
5. Annualized Volatility
● Description: Measures the degree of variation in the instrument's returns over time, expressed as a percentage.
● Interpretation: Higher volatility indicates greater risk, as the investment's returns fluctuate more.
● Advantages: Annualized volatility calculated over the entire selected period provides a more accurate measure of risk, as it includes all market conditions encountered during that time.
6. Dynamic Sharpe Ratio
● Description: Measures the risk-adjusted return of an investment relative to its volatility.
● Choice of Risk-Free Rate Ticker: Users can select a ticker symbol to represent the risk-free rate in Sharpe ratio calculations. The default option is US03M, representing the 3-month US Treasury bill.
● Interpretation: A higher Sharpe ratio indicates better risk-adjusted returns. This ratio accounts for the risk-free rate to provide a comparison with risk-free investments.
● Advantages: By using returns and volatility over the entire period, the dynamic Sharpe ratio adjusts to changes in market conditions, offering a more accurate measure than traditional static calculations.
7. Dynamic Sortino Ratio
● Description: Similar to the Sharpe ratio, but focuses only on downside risk.
Interpretation: A higher Sortino ratio indicates better risk-adjusted returns, focusing solely on negative returns, which are more relevant to risk-averse investors.
● Choice of Risk-Free Rate Ticker: Similarly, users can choose a ticker symbol for the risk-free rate in Sortino ratio calculations. By default, this is also set to US03M.
● Advantages: This ratio's dynamic calculation considering the downside deviation over the entire period provides a more accurate measure of risk-adjusted returns in volatile markets.
Comparison with Basic Metrics
● Static vs. Dynamic Calculations: Traditional metrics often use fixed historical intervals, which may not reflect current market conditions. The dynamic calculations in "Risk Radar Pro" adjust to market changes, providing more relevant and timely information.
● Comprehensive Risk Assessment: By including metrics like maximum drawdown, Sharpe ratio, and Sortino ratio, the indicator provides a holistic view of both upside potential and downside risk.
● User Customization: Users can customize the start date, reference index, risk-free rate, and table position, tailoring the indicator to their specific needs and preferences.
Conclusion
The "Risk Radar Pro" indicator is a powerful tool for investors and traders looking to assess and manage risk more effectively. By providing dynamic, comprehensive metrics, it offers a significant advantage over traditional static calculations, ensuring that users have the most accurate and relevant information to make informed decisions.
The "Risk Radar Pro" indicator provides analytical tools and metrics for informational purposes only. It is not intended as financial advice. Users should conduct their own research and consider their individual risk tolerance and investment objectives before making any investment decisions based on the indicator's outputs. Trading and investing involve risks, including the risk of loss. Past performance is not indicative of future results. Indicator

Indicator