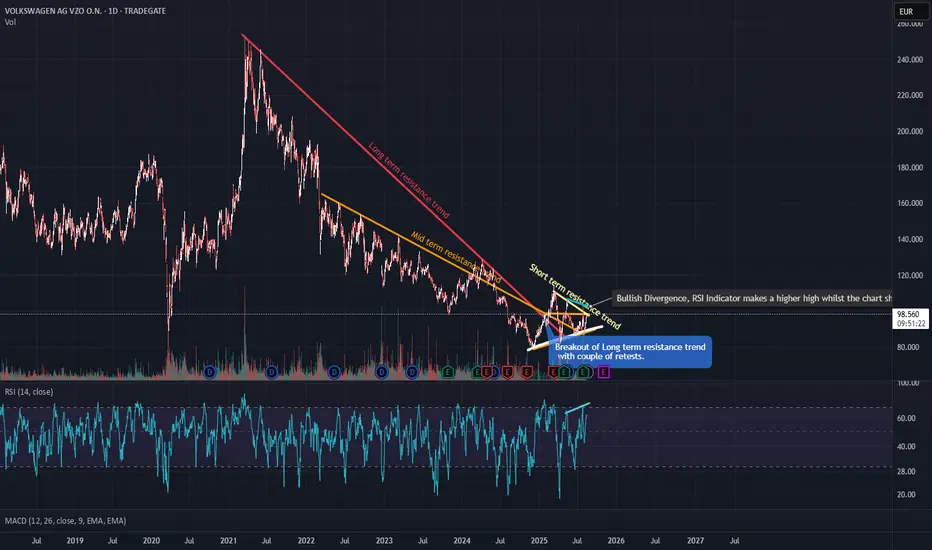
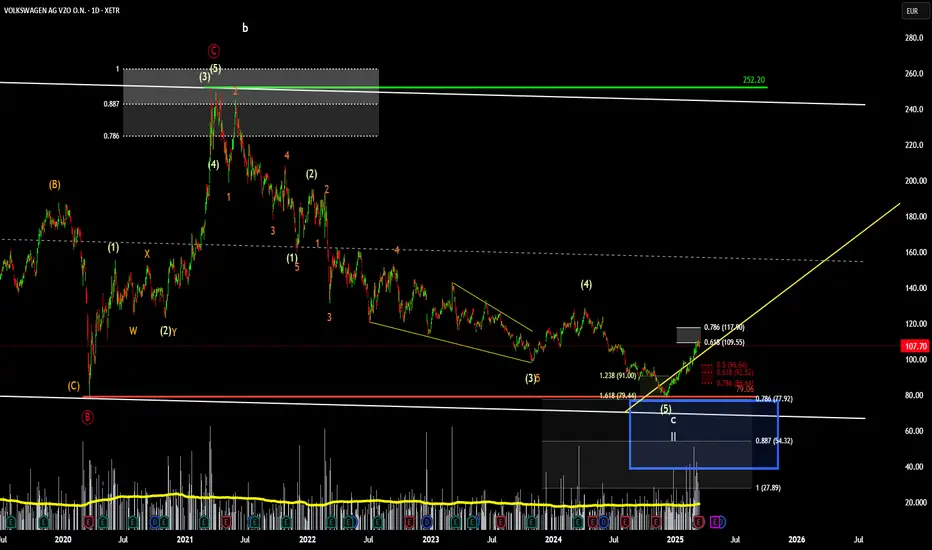
Volkswagen - One of The Greatest Value PlaysXETR:VOW
Volkswagen - 7.77x Earnings, A Falling Wedge, And A Monthly MACD Divergence. The Setup Is Building.
Volkswagen is one of the most unloved stocks in Europe right now and that is precisely what makes it interesting. Revenue for the twelve months ending June 2026 reached $375 billion, up 6.26% year-over-year. Against a consensus analyst price target of approximately €115, implying over 30% upside from current levels, the stock trades at just 7.77x TTM earnings. At a P/E TTM of just 7.77x, against a DAX average of 18-20x, you are paying less than half the price for every euro of earnings relative to the broader index. We are not dismissing the headwinds, Chinese market volume has fallen sharply, and management has flagged that planned cost cuts alone are not enough. But when a business of this scale trades at these multiples, a lot of bad news is already priced in. If margins merely stabilise, today's valuation is too low.
The Setup
VW is developing a textbook falling wedge, converging downward-sloping trendlines with six successful touches and bounces between support and resistance. Falling wedges resolve to the upside more often than not. If it breaks down instead, we are not interested, that is a falling knife and we will not be catching it.
What makes this setup particularly compelling is what is happening on the monthly timeframe simultaneously. While price has been falling, the MACD has completed a bullish crossover, a classic bullish divergence where momentum is turning before price does. On a monthly chart, where noise is significantly reduced, this signal carries real weight. It signals momentum is building while price is quietly consolidating at the end of the very tight wedge boundaries, the exact recipe for a breakout.
We are waiting for confirmation here. Despite the six-touch structure and the monthly divergence we are waiting for weekly close above wedge resistance.
Levels to Watch
Resistance 1 - horizontal price level respected multiple times
Resistance 2 - 200-day EMA, closely watched by institutions
Resistance 3 - long-term trend channel support now turned resistance
A clean break and hold above all three would confirm the full reversal of the downtrend and open the path toward a significant re-rating.
Volkswagen AG
No trades
No trades
In-depth trading ideas
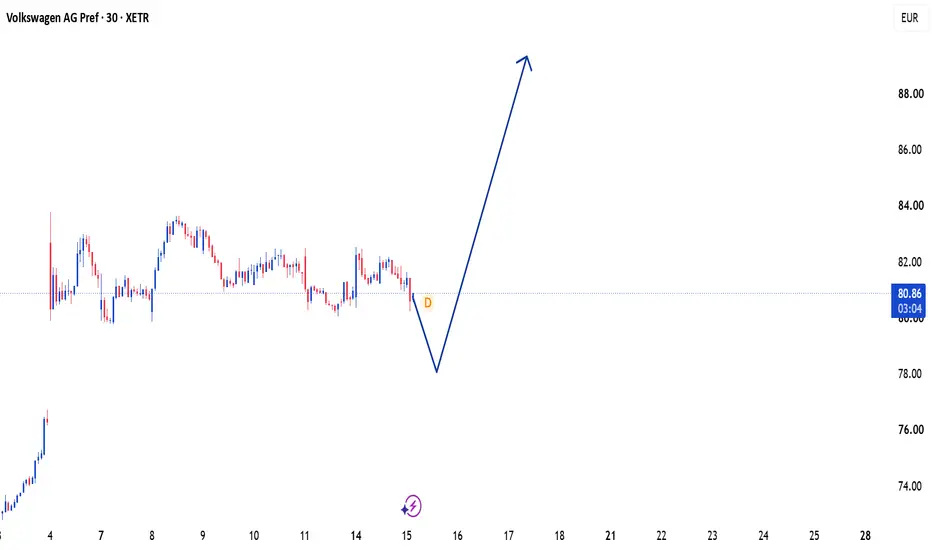
Volkswagen — Bullish Buying Setup | Upside MomentumVolkswagen is currently presenting a constructive buy-side opportunity, with the broader price structure showing signs of improving bullish momentum. The setup is focused on a potential continuation toward higher levels as buyers attempt to strengthen their control over the current market direction. 📈🔥
The analysis is based on the overall behaviour of price rather than a single candle or isolated level. The current structure suggests that downside pressure is losing influence, while the buying side is gradually becoming more prominent.
From a technical perspective, Volkswagen is developing within a structure that supports a bullish scenario. If buyers continue to maintain their influence and upward momentum expands, price could progress toward higher resistance areas and potentially establish a broader upward leg.
The key element of this setup is the relationship between price structure and momentum. Instead of reacting to short-term fluctuations, the focus remains on whether the market continues to respect the conditions generated by the trading methodology.
📊 Setup Overview
- Instrument: Volkswagen
- Bias: Bullish 📈
- Direction: Buy
- Market View: Upside continuation
- Structure: Constructive
- Momentum: Buyers gaining influence
- Approach: Technical market-structure analysis
The current environment provides an opportunity to participate in the potential upside while keeping the analysis centred around a clearly defined framework. Markets rarely move in a perfectly straight line, so short-term retracements should be viewed within the context of the larger structure rather than interpreted independently.
If the prevailing conditions remain supportive, Volkswagen could continue building upward momentum and move toward higher price territory.
🔥 Why the Setup Stands Out
The attraction of this trade comes from the developing relationship between price action, directional structure and buying pressure.
The market is showing characteristics that can support further appreciation, and the buy-side scenario remains the primary focus while those conditions remain valid.
The objective is not to predict every individual candle. It is to identify the broader opportunity, follow the established framework and allow price to reveal whether the anticipated continuation develops.
Bullish structure.
Buy-side pressure building.
Higher levels in focus. 🎯📈
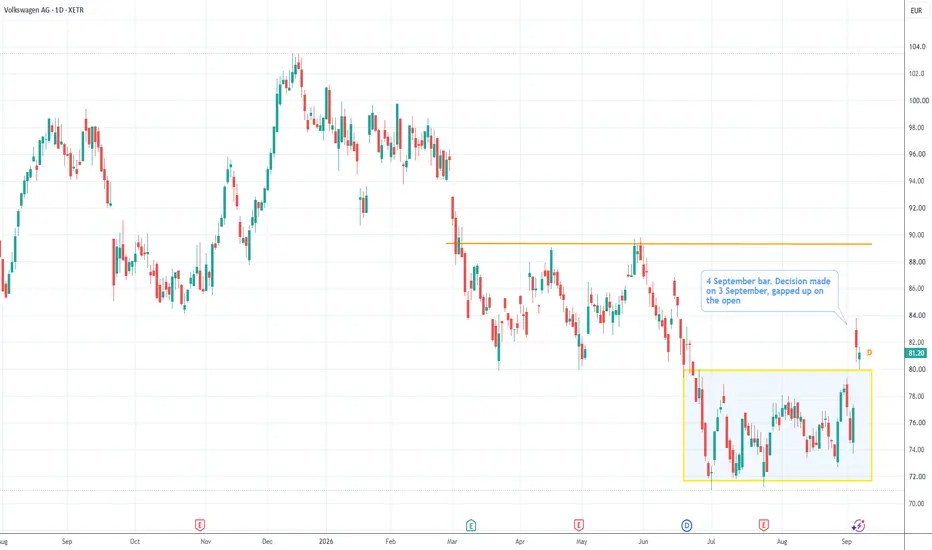
The German Auto DiscountLast Thursday evening, Volkswagen's supervisory board unanimously approved Zukunftsplan 2030 — the Future Plan. On Friday the shares closed up about 6.5% at €81.30, the strongest name in the Stoxx 600 that day.
Nothing about the company's earnings changed in those 24 hours. What changed was that a room full of people who had been unable to agree, agreed.
What was approved
Around 50,000 further positions go, management included, on top of roughly 50,000 already agreed since late 2024. The model portfolio gets cut by about half by 2035 and offering complexity by around 75% — fewer nameplates, higher volume per model, shared platforms and electronics. Capital tightens, with the 2027–2031 capex and R&D budget set below the previous planning round, and the portfolio of shareholdings slimmed by roughly a third.
The target is nine million vehicles and a nine percent operating margin by 2030. VW's operating margin in the first half of 2026 was 3.8%.
Two things were deferred, and they were the two that would have been hardest politically: a possible spin-off of the core Volkswagen brand, and immediate plant closures. Europe carries more than 500,000 units of excess capacity. Four German plants — Emden, Zwickau, Hanover and Neckarsulm — have no secured follow-on product from 2031 to 2034. The full European production concept is due by the end of June 2027.
So the plants are not closing. They are scheduled for a decision about closing, in twenty-one months.
Worth noting that closure isn't the only option for a plant. Rheinmetall's CEO publicly identified a Volkswagen site as suitable for armoured vehicle production, and another German defence manufacturer has already converted a railcar factory to build tank components. Nothing has been agreed at any of the four plants named here, but it does mean the excess capacity line has a possible buyer attached to it.
Deutsche Bank's note afterwards put it plainly: the approval removed the concern about whether the company was still capable of making hard decisions at all.
That is a repricing of decision-making capacity, not of profit. A company that cannot decide has no path to any outcome. But the plan and the result are separated by four and a half years.
Four companies, one label
German autos get discussed as a single trade. Up close, they don't behave like one.
Every German carmaker is dealing with the same headline problems. China turned from profit engine into a shrinking, hostile market. US tariffs on European-built cars have been moved, negotiated, litigated and threatened repeatedly. The EV transition arrived slower and more expensively than planned. German cost and energy stayed high while European volumes stayed below pre-Covid levels.
Same weather, four boats. But the market has not priced them anywhere close to alike, and the gap between the valuations is far wider than the gap between the businesses.
Volkswagen
The volume problem in its purest form. An operating margin around 4% and a return on equity under 3%. Nine million vehicles a year produced by a company that struggles to make money on any of them.
The market's verdict is the most extreme in the sector: roughly a fifth of book value. When a company trades there, the market is not saying "bargain." It is saying that a large share of those assets — the plants, some of the brands, the Chinese joint ventures — will not earn their cost of capital. The bad outcome is already assumed.
BMW
This is the one quietly working, and it gets much less attention than the others.
More profit than Volkswagen on 40% of the revenue, on double the operating margin and more than double the return on equity.
Here is the cleanest way to see what that's worth. The two companies earn almost exactly the same amount per share: €10.46 at Volkswagen against €10.38 at BMW. Volkswagen's shares cost €81.30. BMW's cost €62.64.
Same earnings per share, and Volkswagen costs 30% more. Because the per-share figures are near-identical, the price gap is the valuation gap.
BMW also pays a higher dividend, posted the only earnings beat in the group last quarter, and is down more this year — roughly a third against Volkswagen's fifth.
BMW's China deliveries fell about 20% in the first half. It is not immune. It has simply been hit less hard, and it went into the downturn with a stronger mix and a more flexible plant structure.
Mercedes-Benz
The China luxury story, in full. First-half China sales fell roughly 28%.
Operating margin sits between VW and BMW, and the dividend yield is the highest of the four. But it is not the cheap one — Mercedes trades at a higher multiple of earnings than Volkswagen and considerably higher than BMW, and its payout ratio is the most stretched of the group at roughly two-thirds of earnings, against under 40% at the other two.
Mercedes carries a specific structural exposure the others don't share equally: a large share of what it sells in the US is built in Europe, which makes it more sensitive than most to whatever the tariff rate turns out to be.
Porsche AG
And then there's this one.
Porsche's China deliveries fell about a third in the first half — the worst of the four. The dividend has been cut. The most recent quarter was a loss.
It trades at roughly 1.9x book, against Volkswagen's 0.2x.
There is something that partly explains the premium. Porsche's EBITDA margin is about 23.6%, comfortably the highest of the four and well ahead of Volkswagen's 15%. The business is more profitable than the loss suggests — depreciation and charges are doing the damage. The market isn't only paying for the badge.
The comparison
Trailing P/E — Volkswagen ~7.8x, BMW ~6.0x, Mercedes ~9.0x, Porsche ~40x
Price to book — Volkswagen ~0.20x, BMW ~0.5x, Mercedes ~0.5x, Porsche ~1.9x
Dividend yield — Volkswagen 6.5%, BMW 7.0%, Mercedes 7.6%, Porsche 2.4%
H1 China deliveries — Volkswagen −26%, BMW −20%, Mercedes −28%, Porsche −32%
All four reported recently, into the same conditions. Volkswagen missed expectations by about 46%. BMW beat by roughly 9%. Mercedes missed by around 10%. Porsche lost money. One quarter is noisy and auto earnings are lumpy with provisions and charges — but four companies, one set of headwinds, four different results is the argument of this whole piece in a single row.
Now look at Volkswagen and Porsche together.
Volkswagen's entire market capitalisation is about €40.8 billion. Volkswagen owns roughly 75% of Porsche AG, which the market values at about €38.7 billion — so that stake alone is worth somewhere near €29 billion.
Which implies the market values everything else inside Volkswagen — nine million vehicles a year, Audi, Škoda, SEAT, Cupra, Bentley, Lamborghini, Ducati, the Traton truck group, PowerCo, financial services — at something like €12 billion.
Caution here, because this is the kind of observation that looks like free money and isn't. VW carries a large net debt position, most of it inside captive finance. Holding-company and conglomerate discounts are completely normal and usually permanent. A stake you cannot sell is not worth the same as cash.
What the charts say
I've marked the zones where price reacted on each one
What they share: Volkswagen, BMW and Mercedes sit near the bottom of multi-year ranges.
Volkswagen has been in a trading range for about 4 years. It has bounced off a band near 69 that has now held twice. The zone above, around 101–109, is where the stock has been sold and price turned down again.
Four years of going nowhere is its own kind of information. A stock repeatedly sold at the top of its range and bought at the bottom is a stock the market has made up its mind about, and a fifth of book value is what that verdict looks like on the balance sheet. This is roughly where value investors do their shopping — after the damage, not during it.
BMW ranged widely between the high 50s and the mid 90s for four years and only arrived at the bottom of that range this summer - which puts the best numbers of the four at their lows for the first time in years.
Mercedes is also in a wide trading range. The line near 44 has held four times. In spring 2025 price fell through it and touched a lower support zone that had held since 2022. But price quickly reversed and moved up to the upper zone.
Porsche has spent more than a year inside a band roughly between 34 and 48. Its downtrend line broke over a year ago and it has been building a base since.
It's tempting to say the market has simply refused to reprice Porsche. It hasn't. Porsche fell about 65% from its 2023 peak — the worst of the four — and sits only a few percent above its all-time low. The repricing happened. It started from a level extravagant enough that losing two-thirds of the price didn't make it cheap.
What's actually shared, and what only looks shared
The headwinds are shared. The exposure isn't.
China hit all four, and hit the most expensive brands hardest — which is the opposite of what the valuations imply. Tariffs hit whoever builds in Europe and sells in America, which is Mercedes and Porsche far more than the others. Overcapacity and the German cost base are Volkswagen's problem far more than BMW's, because scale that can't be filled is only expensive when you have a lot of it. The EV transition is everyone's problem, but the money already sunk into it is very unevenly distributed.
So what it comes down to is this: the market has applied one discount to a sector containing four quite different companies, and then applied a completely separate rule to the one whose brand still commands a premium its reported earnings don't.
Whether that is a mistake or good judgement is the actual question here.
What I'd watch rather than predict
A few things that will tell you which way this goes before the 2030 targets do.
VW's June 2027 European production concept. That is the real test of whether capacity comes out or the deadline moves again.
Margin progression rather than margin targets. The gap from 3.8% to nine percent is enormous. Mid-single digits by 2028 would be a completely different story than flat.
Chinese relative share rather than absolute volume, since the whole market is shrinking and absolute numbers currently tell you as much about China as about any German carmaker.
Whether Volkswagen's next quarter looks anything like the last one. A 46% miss is one data point. Two in a row is a pattern.
And whether Porsche's premium survives another year of the numbers it has been printing. That gap closes eventually — the open question is from which direction.
Where I land personally
I might add some of these to my European dividend portfolio. Real assets that hold something in an inflationary environment. These carmakers will never move like the hot US tech and AI names, and that's fine, because that's not the job they're doing. As a European I also like holding assets in my home currency. Different portfolios, different logic, different risk profile.
And to be clear about what I'd be buying it for: two things, not one. The dividend is the part that pays for waiting. The re-rating is the part that pays if the turnaround is real. Neither alone would probably interest me much — a high yield on a business that keeps shrinking is just a slower way to lose money, and a turnaround with no income attached would mean paying to wait. Together they're a reasonable shape for me.
So this sector is naturally on my list. If I buy here, the bet is simple: that the turnaround is real, and that the market is currently paying me to wait while it happens.
Do I think the Germans can do it? On the manufacturing side, probably. This is a country that has spent a century being extremely good at building things, and Volkswagen's plan attacks the right variables — model sprawl, headcount, capital discipline, decision speed. Those are problems German industry has solved before.
What gives me more pause is the layer above the companies. Energy costs in Germany are among the highest in Europe, and that is a structural input none of these four control. They can fix their model portfolios. They cannot fix what it costs to run a factory in Lower Saxony. Some of what's weighing on these businesses is not a company problem at all.
Porsche I'd leave out either way because whatever discount I'd be buying, it isn't there. That doesn't mean the price can't go higher.
Beyond that I haven't yet decided, and the deciding is a decent mental exercise in itself. A few versions of the same idea:
Equal weight across Volkswagen, BMW and Mercedes. The lowest-conviction version — it takes the sector view without needing to be right about which company. The cost of not choosing is that you put the same money into the best-run one, and the cheapest on earnings, as into the most expensive one.
Tilted toward Volkswagen. Something like half in VW, a quarter each in the others. This is the restructuring bet: VW is by far the cheapest on assets, so it has the most to re-rate if the plan works. What you're accepting is that you're paying more per euro of current earnings than BMW asks, for a company with half the margin — and one that just missed expectations by 46%.
Tilted toward BMW. The mirror image, and the one the numbers point at more directly. Cheaper on earnings, double the margin, higher dividend, the only beat in the group last quarter. This isn't a bet on a turnaround at all — it's a bet that a company already working has been marked down with the sector and gets re-rated when the sector does.
Volkswagen alone. The highest-conviction version, and a different bet entirely — one company and timing, since it assumes the plan was the turn rather than just an event on the way. Both can be wrong independently, and the last quarter is a reminder that the operating business hasn't turned yet even if the governance has.
Or nothing yet. Wait for more data and monitor price action. After all, sidelines are a position, and there's no rule saying this has to be decided now.
Five versions, and they don't even agree on what cheap means. Volkswagen is cheapest on what it owns. BMW is cheapest on what it earns. Which of those you find more convincing decides most of the answer before you get to the weightings.
Three German carmakers is company diversification, not diversification. They share a sector, a country, a currency, a labour system and a tariff exposure. In the scenario that actually hurts — Chinese brands take another ten points of European share, or the trade situation goes the wrong way — all three go down together. It removes the risk of picking the wrong one. It does nothing about the risk of being wrong on the whole thesis.
The dividend makes the waiting bearable, not free. A 7% yield covers a 7% decline. It does not cover a 40% one. And it's calculated on earnings that have already fallen a long way — a payout that looks safe against depressed profits looks different again if profits fall further. It softens the wait. It is not a floor.
One thing before I finish
Everything above is dated 4 September 2026 and half of it will be wrong within a year. Auto data is genuinely messy — captive finance, equity-accounted joint ventures and one-off items land differently on different screens. Just check the date on anything that matters to a position.
Which of the four looks most interesting to you — the cheapest one, the best-run one, or the one whose premium hasn't cracked yet? Or no sound investment here? Feel free to get a discussion going in the comments.
Thanks for reading 😉
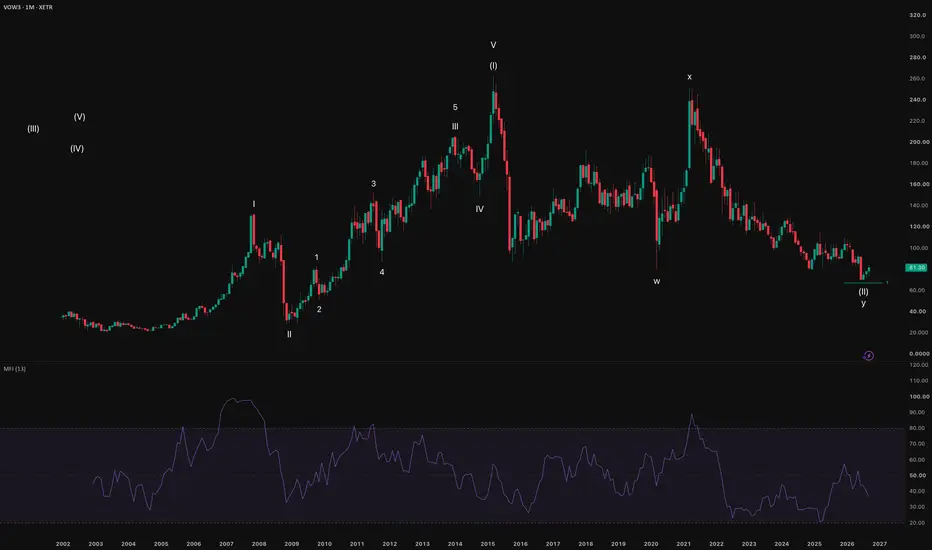
Volkswagen: A long-term bottom in the makingVolkswagen has found buyers near the end of what I count as a WXY correction on the monthly chart. Wave (II) may already be complete, but the fib.1 extension sits at 67, so there is still room for another low before the next long-term advance.
The restructuring gives me a fundamental reason to watch this setup. Volkswagen is targeting more than €6 billion in profitability improvement by 2030 through job cuts, plant consolidation and fewer models. Lower investment spending and asset sales could also help cash flow.
Strong sales growth does not have to return immediately for the business to improve. Lower costs and better margins could help rebuild confidence over time. Competition from China and weak demand remain risks, and the restructuring will take years to deliver its full benefits.
For now, price is still below some key moving averages. A sustained move back above them would give me more confidence that the trend has turned.
My view is that Volkswagen has formed a long-term bottom. Another low toward 67 would still fit that count. A sustained break below that area would make me reassess it.
Volkswagen chokes between U.S. tariffs and Chinese pressureBy Ion Jauregui – Analyst at ActivTrades
Volkswagen is facing a challenging period marked by international trade pressure, slowing demand and the structural transformation of the automotive industry. The German manufacturer reported a 10% decline in operating profit during the second quarter, to €3.5 billion, and has revised its forecasts downward, now acknowledging that its revenues in 2026 could fall by up to 3%.
The company estimates that U.S. tariffs could have an impact of up to €5 billion annually, adding pressure to margins already affected by the high costs of the transition towards electric vehicles and investment in new technologies.
Volkswagen finds itself caught between two fronts. On the one hand, U.S. trade barriers are penalising its exports and increasing costs. On the other, the offensive from Chinese electric vehicle manufacturers, with more competitive cost structures and rapid technological innovation, is reducing the historical advantage of European manufacturers.
China, which for years was one of the key markets for the German group, has become one of its main challenges, with growing competition from local brands such as BYD in the electric vehicle segment.
The stock loses ground after the Christmas rally
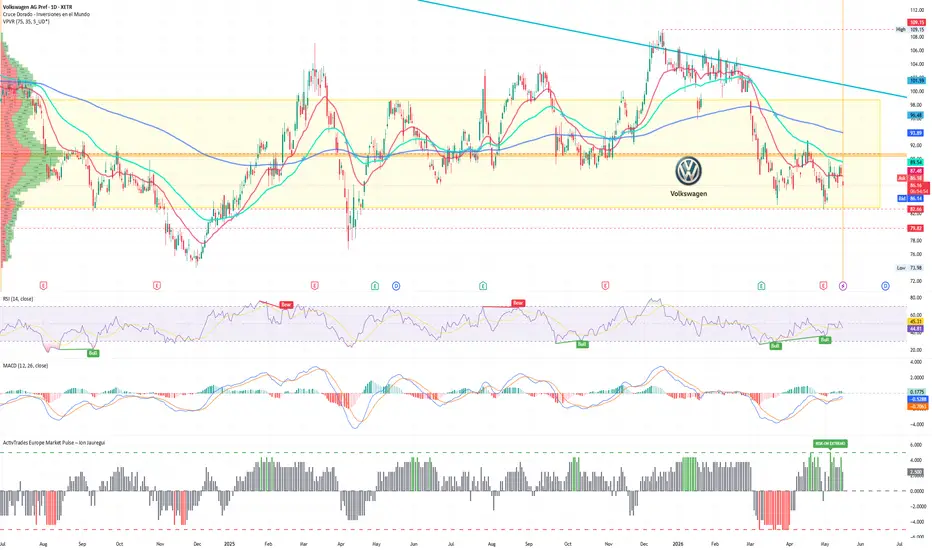
On the stock market, Volkswagen continues to reflect investors’ doubts about the group’s ability to restore profitability. The share price reached a low of €69.20 on July 1 and was trading around €72.66 during the first hours of Monday’s session.
Since the end of the Christmas rally, the stock has been losing ground from highs of €109.15, without managing to surpass the previous high of €114.20 reached in March 2025. This performance has resulted in a gradual price decline over recent months.
From a technical perspective, the daily chart’s point of control shows a highly polarised volume distribution around the previous range located at €90.82, a level that could act as a reference point for a potential price recovery.
The MACD remains in negative territory, although accompanied by a positive histogram that points towards a possible stabilisation of the bearish movement. The RSI stands at 41.08%, entering moderate oversold territory and showing initial signs of recovery.
The 50-session moving average crossed below the 200-session moving average in March, confirming a technical deterioration that subsequently extended the decline.
Meanwhile, the ActivTrades Europe Market Pulse market sentiment indicator currently shows a neutral risk environment, with no signs of excessive positioning or extreme investor sentiment.
Volkswagen remains one of Europe’s major industrial benchmarks, but the market now demands clear results in efficiency, cost reduction and the ability to compete in a new era dominated by electrification and Asian competition.
*******************************************************************************************
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and such should be considered a marketing communication.
All information has been prepared by ActivTrades ("AT"). The information does not contain a record of AT's prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance and forecasting are not a synonym of a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Political risk is unpredictable. Central bank actions can vary. Platform tools do not guarantee success.
VWAGY | Volkswagen | Q3 2026 | Week ChartVolkswagen AG-
MARKET-BEATING SCORE 0/10
Dividend yield (indicated)
5.13%
----------------------------------
Positive EPS ($1.42)
EPS growth 7.82% — supports path to +25% rebalance target.
Conservative D/E (0.67) — balance sheet resilience.
Positive FCF — real cash generation. Best long-run predictor of value creation.
Volkswagen owns so many other automobile companies like Audi, Bugatti, Bently, Ducati, Lamborghini, Porsche, and some others.
----------------------------------
Multiple Time-Frame Analysis; Color Code | Strength favors the higher timeframe.
Yearly timeframe = black
Monthly timeframe = pink
weekly = grey
daily = red
4hr = orange
1hr = yellow
15min = blue
5min = green if they are shown. (Level visibility on intervals is set to timeframe the level was found on and below to keep chart view organized.)
** Candle Science explained **
A Range = two or more consecutive color candles.
There are two types of ranges - accumulation and distribution.
DISTRIBUTION RANGES DEFINED:
When price is above a distribution range, these candles/levels act as support.
(BS) BACKSIDE Candle - First distribution candle in a distribution range. Expectation = strong reaction to price. long wicks reaching to or away from level.
(FS) FrontSide Candle - Last distribution candle in a distribution range. Expectation = reversal, create a trend in the opposite direction. Distribution candles are used as support.
ACCUMULATION RANGES DEFINED: When price is below an accumulation range, these candles/levels act as resistance.
INVERSE BACKSIDE (Inv.BS) - First Accumulation candle in an accumulation range. Expectation. = strong reaction to price. long wicks reaching to or away from level.
INVERSE FRONTSIDE (Inv.FS) - Last accumulation candle in an accumulation range. Expectation = reversal, create a trend in the opposite direction. Accumulation candles are used as resistance.
Volkswagen Long-Term Structural CompressionXETR:VOW
Volkswagen is not a short-term trading chart here. This is a multidecade structural map.
The chart shows three major reference points: 1998, 2008 and 2021. Each of these periods created an important reaction zone, but the most important message is the long-term compression between the falling macro resistance and the horizontal support area around €62.
The 2008 spike remains the most extreme event on the chart. That move was not a normal trend continuation. It was a historical distortion, a vertical repricing event followed by a full structural reset. After that peak, Volkswagen never built a clean long-term continuation structure above that region. Instead, the market started forming lower macro highs.
The 2021 peak is important because it confirms the same long-term resistance line. Price moved strongly into that area, but failed again. That rejection created another lower high relative to the 2008 event and kept Volkswagen inside the broader descending macro structure.
The dashed rising line from the 1990s and 2000s acted as a long-term trend support for years. But after the 2021 rejection, Volkswagen lost that rising structure and moved back into a weaker range. This is a major change. It tells us the old long-term upward slope is no longer controlling price.
Now the chart is moving between two important zones.
The first zone is the current lower range around €75–€90. This is where price is trying to stabilize after the 2021 decline. However, stabilization alone is not enough. The chart still remains below the falling macro resistance, so the long-term structure is still compressed.
The second and more important level is the red horizontal area around €62. This is the historical support zone. It connects old market memory from previous cycle structures and also sits near the projected meeting point of the falling resistance line in the future. If Volkswagen returns to that area, it would be a major long-term test.
That level is not just a random support. It is the area where the market would decide whether Volkswagen is still building a multi-decade base, or whether the long-term industrial auto structure is losing another major support layer.
The bullish case is simple but not confirmed yet. Volkswagen needs to hold above the long-term support region and eventually break the descending resistance that has controlled the structure since the 2008 extreme. Until that happens, every rally remains inside a larger compression pattern.
The bearish case is also simple. If the current range fails and price returns to the €62 zone, the market will be testing the most important structural support on the chart. A clean loss of that level would weaken the long-term map significantly.
So the current read is neutral to cautious.
Volkswagen is not in a clean expansion structure. It is not showing a confirmed long-term breakout. It is still trading below macro resistance, after losing the older rising trend structure.
But the chart is also not random. It is approaching the final phase of a long compression between descending resistance and historical support.
The main question is this:
Does Volkswagen defend the old structural base and prepare for a future breakout?
Or does the long-term compression resolve lower?
For now, the chart is not giving the final answer.
It is showing the test.
Volkswagen:While union tightens its stance,BYD arrives Dresden**Volkswagen (VOW3): While the union tightens its stance, BYD arrives in Dresden**
By Ion Jauregui – Analyst at ActivTrades
Volkswagen (VOW3) is once again at the center of the European market focus following recent reports on a potential industrial collaboration with BYD in Germany and growing tension between the group’s management and German trade unions.
The German manufacturer is going through one of its most challenging periods in recent years. The slowdown in demand in Europe, strong Chinese competition in electric vehicles, and the threat of new US tariffs are forcing the company to rethink its industrial structure.
## The union maintains its “red line”
According to Reuters, Volkswagen’s union representatives have reiterated their absolute rejection of plant closures in Germany, maintaining a firm stance against the restructuring plans pushed by group management.
The company is seeking to reduce production capacity to improve efficiency and protect margins, particularly in a context where the European industry is facing overcapacity against weaker demand.
However, IG Metall and the works council consider that any factory closures would represent a direct threat to German industrial employment, increasing political and social pressure on the manufacturer.
## BYD and the Dresden plant
At the same time, the market remains highly attentive to reports regarding BYD’s interest in partially using the historic Dresden plant, known as the *Gläserne Manufaktur*.
The factory stopped producing the ID.3 and currently some of its facilities have limited activity, which has fueled speculation about possible industrial agreements between Volkswagen and Chinese manufacturers.
Although Volkswagen has officially denied the existence of a definitive agreement, the possibility reflects the profound structural shift taking place in the European automotive sector. A few years ago, it would have been unthinkable for Chinese manufacturers to operate within historic German group facilities.
BYD’s potential entry also highlights the growing competitive pressure from China on European automakers, particularly in the EV segment, where Asian groups maintain significant advantages in production costs and battery development.
## The threat of US tariffs
This situation is further complicated by the commercial risk coming from the United States. The threat of imposing 25% tariffs on European automobiles could seriously affect German manufacturers such as Volkswagen, especially at a time when the sector is already facing margin deterioration and slower global growth.
The market fears that these trade tensions could force European companies to further accelerate industrial restructuring and cost-cutting processes.
---
## Technical analysis of VOW3
From a technical perspective, VOW3 continues to show a medium-term sideways structure after finding a double technical support in the impulsive zone formed in December 2024. The stock is currently trading within a wide consolidation range between €82.66 as key support and €98.76 as major resistance, while the most recent high remains at €109.15 recorded in December 2025. The uncertainty around the electric transition, combined with margin pressure and industrial costs, continues to limit the stock’s ability to develop a sustained bullish trend.
On the daily chart, a point of control zone stands near €91, where price action appears to have stabilised after recent volatility phases. The bearish moving average crossover remains in place, although the price has managed to trade sideways around the 50-day moving average, showing some short-term stabilisation.
In terms of indicators, RSI remains in neutral territory after recovering from oversold levels, while MACD is still below the zero line, although with a positive histogram, suggesting fading selling pressure without a clear return of bullish momentum.
Key resistance levels remain concentrated around the psychological €100 area, where institutional selling and profit-taking have previously emerged. On the downside, the €82–83 support zone remains the critical level to preserve the current medium-term sideways structure.
On the other hand, the ActivTrades Europe Market Pulse indicator showed a clear “risk-on” environment in previous weeks, driven by strong corporate earnings in Europe, supporting upside moves in companies such as Volkswagen. However, in the current session, the indicator has shifted back to a neutral reading, reflecting a more cautious market stance amid macroeconomic and sector uncertainty.
From a fundamental perspective, the potential rapprochement between Volkswagen and BYD at the Dresden plant adds a relevant strategic dimension. Although there is still no confirmed agreement, the market interprets this potential collaboration as a sign of industrial pragmatism: optimisation of underutilised capacity in Europe and indirect entry of Chinese manufacturers into the German production ecosystem. If materialised, this factor could act as an additional medium-term catalyst for the stock.
In the coming months, investors will remain focused on industrial agreements, union pressure, and the impact of US tariffs, all of which could define the next directional move for VOW3.
*******************************************************************************************
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and such should be considered a marketing communication.
All information has been prepared by ActivTrades ("AT"). The information does not contain a record of AT's prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance and forecasting are not a synonym of a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Political risk is unpredictable. Central bank actions can vary. Platform tools do not guarantee success.
Volkswagen Shares Hold Above 88 as Rivian Partnership Boosts Shares of Volkswagen AG are trading slightly above 88.00, stabilizing within a broader market correction. Investor sentiment improved after the company announced progress in its software partnership with Rivian Automotive.
⸻
Rivian Partnership Enters New Phase
Volkswagen confirmed that winter testing of vehicles using Rivian’s software platform was successfully completed:
• Tested at temperatures as low as –25°C
• Supports 15+ sensor systems
• Compatible with 20 electronic control units
The platform will be used in future models from:
• Volkswagen
• Audi
• Scout Motors
⸻
Major Investment in Software Strategy
Key project details:
• Initial engineering investment: €2.3 billion
• Total partnership investment: $12 billion+
• Last payment: $5.8 billion (Nov 2024)
Expected benefits:
• Up to 500,000 EVs annually
• Level 2+ autonomous driving
• Faster model development (18–24 months)
The partnership strengthens competition with:
• Tesla
• BYD
• Global EV leaders
⸻
Earnings Outlook
The Q1 report will be released April 30:
• Revenue forecast: €78.90B (vs €77.56B YoY)
• EPS forecast: €4.43
Dividend outlook:
• Previous dividend: €6.30
• Expected yield: 7–8%
• Industry median: 4.64%
⸻
Technical Analysis
Volkswagen is attempting to rebound:
• Ascending channel support: 115–96
• Sell signal weakening
Indicators:
• Alligator: bearish but weakening
• AO: corrective negative bars
➡️ Potential stabilization forming
⸻
Key Levels
Resistance
• 92.00
• 100.00
Support
• 85.00
• 75.50
⸻
Trading Scenarios
Bearish Scenario
Sell below 85.00
• Entry: 84.95
• Target: 75.50
• Stop-loss: 90.00
• Timeframe: 7 days or more
⸻
Bullish Scenario
Buy above 92.00
• Entry: 92.05
• Target: 100.00
• Stop-loss: 89.00
⸻
Outlook
Volkswagen remains supported by:
• Rivian software partnership
• EV expansion strategy
• Strong dividend outlook
• Break above 92.00 → bullish continuation
• Break below 85.00 → downside risk
Short-term outlook remains neutral with bullish potential.
Volkswagen AG - Long-Term Opportunity DevelopingVolkswagen appears to have completed a full 5-wave impulse cycle, topping out around the 2021 highs. Since then, price action has transitioned into a broader corrective phase, likely unfolding as an ABC structure.
Wave A marked the initial sell-off, followed by a Wave B recovery. Currently, price action suggests we are in Wave C, which typically represents the final leg of a correction.
From a structural perspective, the trend remains weak:
Lower highs and lower lows
No confirmed reversal yet
Price trading below key retracement levels
Key Levels
61.8% retracement (~105€): First major resistance
78.6% – 88.7% zone (~55–75€): High-probability demand zone
Long-term support (~34€): Historical floor
My Plan (Long Setup)
I am not looking to enter at current levels.
Instead, I’m watching for price to move into the 55€–75€ zone, which aligns with:
Deep Fibonacci retracement levels
Potential completion of Wave C
Long-term value area within the broader range
This zone offers a high risk/reward long opportunity if:
Price shows signs of stabilization
Selling pressure weakens
A structural shift begins (higher lows / reclaim of key levels)
Invalidation / Risk
A clean breakdown below ~55€ would suggest a deeper structural shift
No confirmation = no position
Conclusion
Volkswagen is not currently in a trend phase, but rather in a long-term corrective structure.
The focus is on patience and positioning in extreme value zones, not chasing price.
This is a planned long setup, not an active trade.
Is Europe's Industrial Crown Jewel Being Quietly Dismantled?Volkswagen Group, once the symbol of German engineering dominance and post-war European recovery, is experiencing what can only be described as a structural dismantling rather than a cyclical downturn. The company faces a perfect storm of challenges: geopolitical vulnerability exposed by the Nexperia semiconductor crisis, where China demonstrated escalation of dominance over critical supply chains, catastrophic labor cost disadvantages ($3,307 per vehicle in Germany versus $597 in China), and a complete failure of its CARIAD software division that consumed €12 billion with little to show for it. The result is unprecedented: 35,000 German job cuts by 2030, the first factory closures in 87 years, and Golf production moving to Mexico.
The technological surrender is perhaps most revealing. VW is investing $5.8 billion in American startup Rivian and $700 million in Chinese EV maker XPeng—not as strategic partnerships, but as desperate attempts to acquire the software and platform capabilities it failed to develop internally. The company that once provided technology to Chinese joint ventures now buys entire vehicle platforms from a Chinese startup founded in 2014. Meanwhile, its profit engine has collapsed: Porsche's operating profit plummeted 99% to just €40 million in Q3 2024, while VW's China market share eroded from 17% to under 13%, with only 4% share in the critical EV segment.
This isn't just corporate restructuring—it's a fundamental transfer of power. VW's "In China, For China" strategy, which moves 3,000 engineers to Hefei and creates a separate technological ecosystem under Chinese jurisdiction, effectively places the company's intellectual property and future development under the control of a systemic rival. The patent analysis confirms the shift: while BYD has built a moat of 51,000 patents focused on battery and EV technology, much of VW's portfolio protects legacy internal combustion engines—stranded assets in an electric future. What we're witnessing is not Germany adapting to competition, but Europe losing control of its most important manufacturing sector, with the engineering and innovation increasingly done by Chinese hands, on Chinese soil, under Chinese rules.
VW Bottoming Out? Long-Term Target at €186 Signals Major UpsideVolkswagen appears to have reached its bottom. The current risk-reward ratio is highly favorable. A potential retest of the €83 support level (−11%) remains possible, while the long-term upside target stands at €186, representing a potential gain of +99%.
PERSONAL JOURNAL #1 | VOLKSWAGEN [VOW3] | AUG 2025-2026Disclaimer
This is a personal journal of my exploits. This is not financial advice. Always do your own research.
Insight
Most companies are only now beginning to recovery post Covid-19, the localized correction in 2021 following Evergreen and Evergrande, as well as onset of new wars and high interest rates.
Outlook
Recovery.
VOW3 Bullish Current price at the moment of the idea: 98.50
Levels like 117 and 134 are interesting levels to take profits and repurchase on corrections of -10%
Earnings surprise was 42% which is pretty high for a big company in the automobile sector.
The chart speaks for itself, please read my comments, happy to discuss.
Volkswagen AG (VOW) – The Cheapest Military Stock in Europe? TP1: €150 – Short-term breakout
TP2: €180 – Mid-term resistance
TP3: €250 – Long-term revaluation target
Why Are We Bullish?
🔹 Defense Sector Entry?
-VW exploring military production, with CEO Oliver Blume confirming interest.
-Idle plants may be repurposed, potential Rheinmetall partnership in the works.
-Rearmament boom – Rheinmetall’s valuation already surpassed VW’s.
🔹 Financial & Growth Catalysts
-Q4 sales up 21%, 7.0% margin, 2025 revenue target +5%.
-€1B cost-cutting, strong EV & U.S. market expansion.
🔹 Bullish Technicals
-MACD Bullish Crossover + Green Histogram Bars confirm momentum.
-Bounced off long-term trendline support, signaling a strong reversal.
VW - stock may have turned around (?)VW - has had its fair share of bad news lately, however, panic and fear often times is at its peak when price is close to find the bottom.
Looking at price action and price targets it seems the wave C of II could be over which is also indicated that price bounced from the 161.8 fib expansion of wave 4 of C. Ever since then the stock has seen a steady rise that was also supported by good volume.
Now it has reached the 61.8 retracement of wave 5 and usually around that fib level price will stall and consolidate. I can even see a 5 wave motive wave up.
Now, we need to see how the price action looks like in the coming days and weeks. Hopefully it will make a higher low at around 50-61.8 % fib retracement and from there I would be looking to long the stock. The upside is quite impressive as the price may rise with over 300%.
For now, we remain neutral and are watching what happens next.
Is Volkswagen a buy?I see a lot of people on social media claiming that Volkswagen is now a good buy because the stock is undervalued, because the government will intervene, because it's not all that bad, and so on.
However, if you take a look at the weekly chart with the most basic tools, you will notice that the share is currently not sending any signs that indicate an imminent upward trend in the context of a Stage 2. The price is below a falling 30-week SMA and below a falling AVWAP from the ATH. Even though the price has risen “significantly” in the last two weeks, this should not be a reason for FOMO. Once a trend has been established, it is more likely to continue than to reverse. And as long as the chart does not improve significantly, it is more likely to be a short-term countermovement within a long-term downtrend with lower highs and lower lows. Guilty until proven innocent. For an experienced swing trader, it may be possible to take advantage of these short-term countermovements to generate profits. However, this is too risky for inexperienced traders. Sure, it could happen that the stock will continue its short term move up and establish a Stage 2 with a long term upward trend - but it is not likely. Trade the chart in front of you and listen to the market.
As Peter Lynch liked to say: "If they don't scare you out, they will wear you out."
Bottom fishing is not advisable. Let institutions do the dirty work and do not let FOMO make you trade risky setups. Wait for a clear change of the trend and sentiment.
Volkswagen - soon ready for the next bullish period (?)Today I will look at Volkswagen (VOW3).
VW has had a very tough period especially with the transition to building electric cars and uncertainty especially with european legislation and market regulations. (not a complete fundamental analysis, please search for more fundamentals elsewhere!)
My Elliott wave perspective tells me that we are closing in on a potential pivot point from where the share price could easily double and this could provide us with an excellent trading opportunity for the next years.