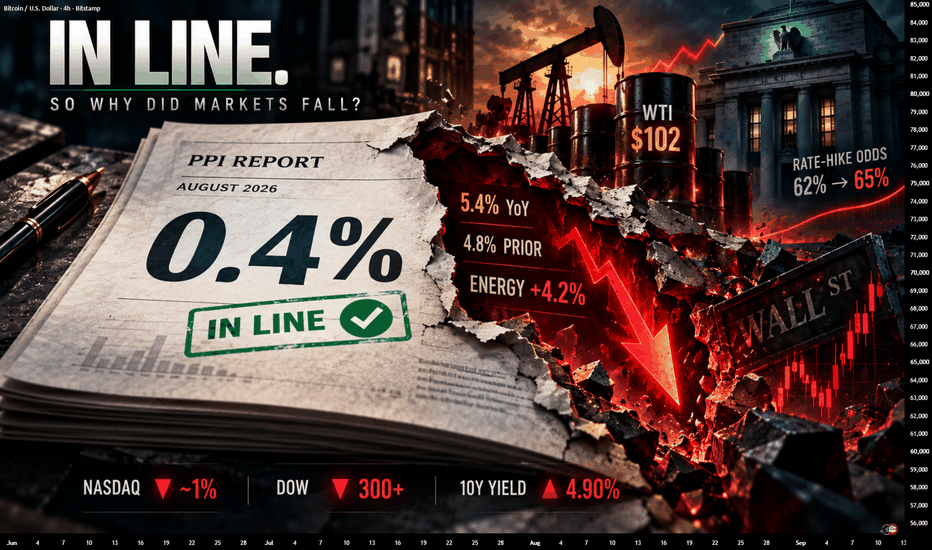
Why the PPI Report Was "in Line" But the Market Still Fell
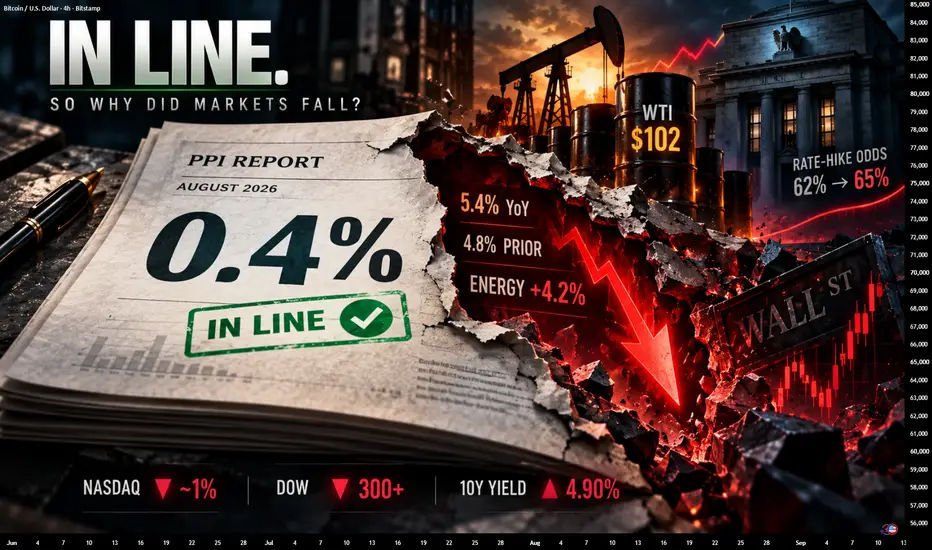
On September 10, 2026, the headline news was exactly where economists expected it to be, but the market didn't take it as a relief. Producer prices rose a modest 0.4 percent month over month in August, right in the center of what the consensus expected. By all standards, this should've been a relatively dull number. Instead, the Dow fell over 300 points , the Nasdaq dropped almost one percent , and this marked the fourth straight day of losses in major indices.
What could've happened to turn an allegedly in-line prediction of economists into a market fall, and why can " in line" sometimes be misleading ? This article will describe what exactly happened with the report, and why this in-line scenario didn't turn out to be as good for the market as it was expected to be.
What happened to the PPI report
The Producer Price Index measures the rate of price increases for businesses before their prices are passed on to consumers. In the case of the monthly producer prices, the number for August was a meager 0.4 percent , right in line with what economists had predicted almost exactly.
However, another number that came with the report told a slightly different story. In year-over-year comparisons, producer prices have accelerated to 5.4 percent , up from 4.8 percent in the previous month. It's this jump that has spooked traders, as a single month of in-line predictions in the middle of a growing year-over-year trend is a more worrying sign than anything.
Within the PPI report itself, one particular segment saw the price increase jump by a whopping 4.2 percent - energy prices .
The oil price problem was on top of the inflation data
The day on which this report was released coincided with the day on which the US crude oil prices crossed above 100 dollars a barrel , with the ongoing conflict between the US and Iran entering its eighth month. The West Texas Intermediate crude oil jumped almost 7 percent on the day, settling just above 102 dollars, with Brent crude oil closing at a record high near 108 dollars.
Since the start of the conflict, the price of WTI crude oil has climbed by over 50 percent from where it was on the day of its start, with the annual increase standing close to 79 percent . A jump in one of the most important costs for the whole economy is a worrying sign, and it landed right on top of a report showing a year-over-year acceleration in the rate of producer prices .
How is the combination of the two significant?
Going into the details, a rise in the price of oil doesn't impact just the gas price at the pump - it also makes transportation more expensive, and by extension, more expensive to manufacture and sell products. The combination of a report showing accelerating year-over-year price increases in producer prices, and a jump in one of the input costs is an alarming sign that the situation is likely to get worse, rather than improve.
It impacts the expectations held by the market for what the Federal Reserve is likely to do next. Coming into the report, the market already held a roughly 62 percent chance of an interest rate hike at the Federal Reserve at its September meeting. The combined report data and oil spike caused the probability to climb to roughly 65 percent , with traders expecting the possibility to climb even higher depending on what the following day's Consumer Price Index report says.
Why did it particularly affect expensive growth stocks?
Unlike the Dow Jones Average, the Nasdaq composite index fell by almost a full percentage point , compared to the Dow's mere 0.5 percent slide. It wasn't a coincidence, as the expensive growth stocks that comprise a majority of the Nasdaq composite index are most sensitive to the expectations of future profitability. A report that causes the future discount rate to rise is particularly impactful on their prices, with the valuation multiples taking the biggest hit .
The chip stocks in particular felt the brunt of the pain - Intel fell by over 5 percent and Micron by almost 5 percent - as the investors worried that a combination of rising interest rates and rising crude oil prices would reduce the rate of economic growth, which in turn would hurt the demand for the chips these companies make.
The most important takeaway: single data points are rarely what moves the market
It's this kind of scenario that often highlights one of the most overlooked aspects behind reading the releases. A single data point that falls right on the expected mark sounds like a confirmation that everything is under control, and the market is likely to move on without a hiccup. However, it's always a good idea to remember that the more useful information is often hidden one step below the surface, either in the year-over-year statistics in the same report or a different market moving sharply at a similar time.
The bond market was also a good indicator when it came to understanding what was going on. The 10-year yield climbed to 4.90 percent , continuing an overall run towards higher multi-year highs, which occurred alongside - not despite - the headline PPI number in line with expectations. The bond market was doing what the equity market did: reacting to the same signals coming out of the report and the simultaneous spike in the prices of crude oil as a representative of a growing set of input costs .
How can you read a report like this correctly?
Don't just look at the monthly price change , but also the year-over-year one in the same report. The year-over-year statistics for a report that's released on a monthly basis are usually more important than the comparison to the previous month.
Look out for the developments in the commodity markets at the same time as the report is released. An inflation report that comes during a spike in the price of oil or another important input cost is going to influence the market differently than one that comes out during a period of relative calm.
Be aware of the changes in the probability of rate hikes or cuts right after a report is released. Not just the movement of the equity markets, but also the bonds' reaction can tell you what the market has concluded on the matter.
Remember that expensive growth stocks and value stocks usually have different reactions to the same type of news. A report that causes the value stock index to fall less than the growth one is a sign that the market is updating its expectations.
My Conclusion
An in-line report is usually taken by the market as a neutral surprise, but the experience of September 10, 2026 shows that it rarely has as little impact as one would expect on the following day's trading. The market doesn't just look at a single month of statistics, but also the trend throughout the year in year-over-year comparisons , and the simultaneous spike in the price of one of the most important input costs in the economy serves as confirmation that the trend is indeed likely to continue.
Thank You
@VertexQore  Education
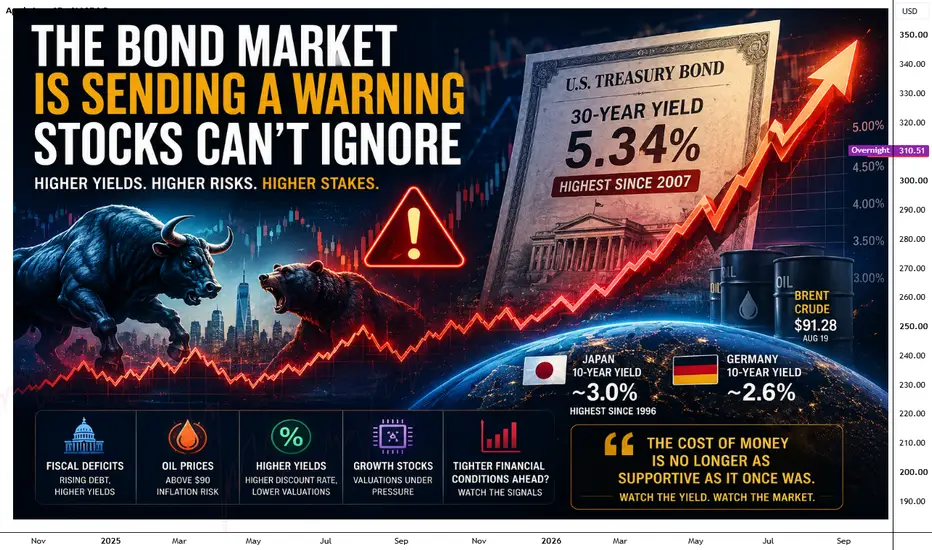
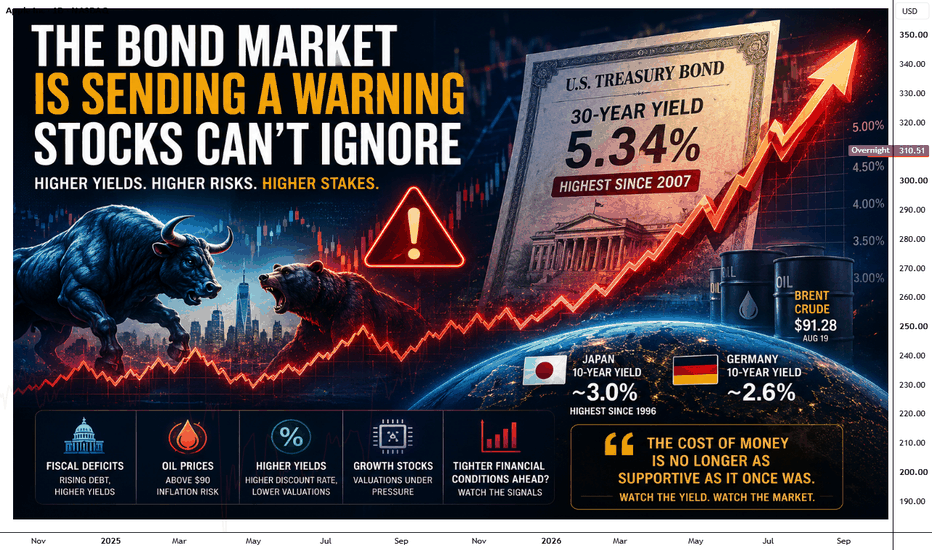
The Bond Market Is Sending a Warning Stocks Can’t IgnoreMost investors are still focused on the stock market, especially technology and AI stocks. But over the past few days, the more interesting move has been happening in bonds. U.S. Treasury yields have moved sharply higher, with the 30-year yield reaching about 5.34% on August 18, its highest level since 2007. The move has not been limited to the U.S. either. Long-term yields have also risen across major bond markets, including Germany and Japan.
Why Does This Matter for Stocks?
Bond yields may sound like a problem for bond investors, but they have a direct connection to stocks. The simplest way to think about it is that government bond yields help set the return investors can get from relatively lower-risk assets. When those yields rise, investors start asking whether expensive stocks are still worth the additional risk.
This matters even more for companies whose valuations depend heavily on profits expected several years into the future. Higher yields can reduce the present value investors place on those future earnings. That does not mean the company has suddenly become weaker. It simply means the market may decide that the stock is too expensive at its previous valuation.
The Market Is Asking for More Return
There is also a bigger reason behind the bond-market move. The U.S. government continues to run large fiscal deficits and needs to issue substantial amounts of debt. Investors are still buying Treasuries, so this is not a case of the market refusing to finance the U.S. government. But investors are demanding higher yields to compensate for concerns surrounding inflation, fiscal sustainability and the amount of debt that needs to be issued. Reuters reported that a recent 10-year Treasury auction produced a yield of 4.683%, while the 30-year yield reached 5.216% at auction.
That distinction is important. The current move should not be described as a Treasury “buyers’ strike.” Demand for U.S. government debt remains substantial. The bigger story is that investors want to be paid more for taking on longer-term interest-rate and fiscal risks.
Oil Is Making the Situation More Difficult
The bond-market story is happening at the same time as another problem: higher oil prices. Brent crude was around $91.28 a barrel on August 19, with uncertainty around exports through the Strait of Hormuz adding to supply concerns. Higher energy prices can make the inflation outlook more difficult, especially if elevated oil prices persist.
This is important because the market would prefer to see inflation moving lower while long-term borrowing costs are already under pressure. Instead, investors are dealing with higher oil prices alongside elevated bond yields. That combination can make the outlook for interest-rate cuts more complicated and can keep pressure on long-duration assets such as growth stocks.
Japan Is Now Part of the Story:
Japan deserves attention as well. Its 10-year government bond yield is approaching 3%, a level not seen since 1996. That is a major shift for a market that spent decades operating with exceptionally low interest rates. Reuters notes that the move reflects inflation concerns, fiscal worries and expectations around further Bank of Japan policy changes.
Higher Japanese yields do not automatically mean Japanese investors will bring money home, and it would be too early to assume a large repatriation of global assets. But the change does make Japanese bonds relatively more attractive than they were during the ultra-low-rate era. That is one reason global investors are paying much closer attention to Japan's bond market.
This Is Where Growth Stocks Can Feel the Pressure:
The recent performance of technology stocks gives us a practical example. On August 18, Wall Street came under pressure as higher oil prices and elevated Treasury yields added to concerns around inflation and economic uncertainty. Technology stocks led the decline, with semiconductor shares among the weakest areas of the market.
That does not prove that higher yields will cause a long-term technology selloff. Stock prices are influenced by many things, including earnings, economic growth, positioning and investor sentiment. But when a market is trading at high valuations, rising yields can make investors less willing to pay a premium for future growth.
This is particularly relevant to the AI trade. The AI investment story is still developing, but investors are increasingly asking whether the earnings growth expected from massive AI spending will justify the prices already being assigned to some companies. When the risk-free rate rises, that valuation question becomes harder rather than easier.
The Bond Market Is Not Predicting a Crash
This is where it is important not to overreact. Rising bond yields do not automatically mean a stock-market crash is coming. Stocks can continue to rise even while yields move higher, particularly when corporate earnings and economic growth remain strong. What matters is the combination of the move and the market's reaction to it.
A slow increase in yields may be absorbed without much damage. A rapid increase, especially if it happens alongside higher oil prices and weakening economic expectations, can be much more uncomfortable for equities.
That is why the reaction in stocks is probably more important than any single yield level.
What Should Traders Watch Now?
The 10-year and 30-year Treasury yields are worth watching closely, but they should not be looked at in isolation. The more useful signal will come from the relationship between bonds and equities.
If yields stay elevated but the S&P 500 and Nasdaq remain strong, investors may simply be adjusting to a higher-rate environment. If yields continue rising while growth stocks, semiconductors and other high-valuation areas begin losing important support levels, the message becomes more concerning.
Oil is another piece of the puzzle. So are credit markets. If higher Treasury yields, elevated oil prices and widening credit spreads begin appearing together, financial conditions would be getting tighter across the market.
The Real Warning:
The bond market is not saying that stocks must crash. It is saying something more subtle: the cost of money is no longer as supportive as it once was.
Long-term U.S. yields are near multi-year highs, Japan's 10-year yield is approaching levels last seen in the 1990s, oil is above $90, and investors are demanding more return to hold long-term government debt.
For equity investors, that creates a very different background environment from the years when cheap money supported higher valuations. The stock market will ultimately decide whether this becomes a major problem or simply another period of volatility. But right now, ignoring the bond market would be a mistake.
The next important signal for stocks may not come from a stock chart at all. It may come from the yield on a Treasury bond.
By @BrightRally_Research on @TradingView  Education
10-Year Treasuries Into FOMC: What to Expect1. Big Picture: What’s Been Driving Bonds?
Over the past several months, the U.S. Treasury market has been defined by diverging forces across the curve, the short end (2Y, 5Y) pricing near-term monetary policy outcomes and the long end (10Y, 30Y) reflecting inflation persistence, fiscal supply, and long-horizon term premium.
The short end has behaved like a proxy for rate-cut expectations, compressing aggressively whenever inflation cools or recession probability ticks higher. Meanwhile, the long end has been more sensitive to duration demand, bond auctions, and forward-looking macro risk, often moving independently when supply shocks or inflation surprises hit the tape.
The result? A curve driven by two narratives: policy timing vs long-run risk.
This sets the stage for next week’s meeting and the reaction likely depends less on the cut itself and more on the messaging around rate trajectory.
2. What did the Market do?
Following the U.S.–China tariff escalation in April (formerly referred to casually as the “Trump Tariff War,” though a better description is the Tariff Re-Escalation Phase), the ZN stabilized. Buyers stepped in between May to July 2025, compressing price toward the 112'08'0 region, which is a key daily resistance zone.
In early September, momentum shifted. Buyers overwhelmed offers and lifted prices through 112'08'0, and the move appears linked to expectations of a softer policy stance and improving forward inflation indicators during the first week of September.
Sellers responded at 113'07'0 area and market has been trapped in a three-month range between 113'25'0 high and 112'08'0 low.
This week, price rotated from the top of range and swept through the composite LVN 113'00'0 to 112'24'0, near the 1st 3 weeks of November composite VPOC.
3. What to Expect: Scenarios Into FOMC Week
Until the rate decision, compression seems likely.
Expect 2 way indecision before FOMC:
Expect two-way trade between 113'03'0 (LVN) and 112'24'0 (1st 3 weeks of Nov composite VPOC) as the market waits for the FOMC.
Bearish Scenario (Base case):
If sellers hold at 113'03'0, continuation lower toward 112'07'0 (range low / composite VAL)
Bullish Scenario:
If buyers reclaim 113'03'0 decisively, possible market move back up to 113'23'0 (Daily Range high), keeping the multi-month balance intact and potentially positioning for a breakout if FOMC guidance surprises dovish.
4. FOMC Risk: What Could Surprise the Market?
The market is currently pricing ~88.6% probability of a 25bps cut which means the cut itself is not the event. The surprise lies in the tone.
🟢 Bullish Bond Reaction (Yields lower) if:
Forward guidance hints at a sequence of cuts, not a one-off
Growth risks emphasized > inflation risks
Dovish dissent or language suggesting easing bias remains intact
🔴 Bearish Bond Reaction (Yields higher) if:
The Fed downplays future cuts or signals higher-for-longer
Inflation risk is prioritized
Dot-plot or press Q&A implies only one cut on table
Conclusion
Unless the press conference delivers a clear dovish or hawkish surprise, expect a similar indecisive, two-way response in the markets, similar to past FOMC market reactions.
What’s your call on ZN and the bond markets going into the week of FOMC? Drop a comment and give a boost so more traders can weigh in.
Disclaimer: This is not financial advice. Analysis is for educational purposes only; trade your own plan and manage risk.
 Short

Global Bond and Fixed Income Markets1. Introduction
The global bond and fixed income markets form the backbone of the world’s financial system. These markets are where governments, corporations, and institutions raise capital by issuing debt instruments—promises to repay borrowed funds with interest. Bonds, treasury bills, notes, and other fixed-income securities collectively represent trillions of dollars in outstanding obligations, making this one of the largest and most liquid asset classes globally.
Unlike equity markets, where investors purchase ownership stakes in companies, the fixed income market revolves around lending. Investors essentially become creditors, earning predictable income through periodic coupon payments and principal repayment upon maturity. The stability and reliability of these returns make bonds a cornerstone for institutional investors, central banks, and individuals seeking steady income or capital preservation.
In 2025, the total global bond market exceeds $140 trillion, spanning government debt, corporate bonds, municipal debt, supranational issuances, and structured credit instruments. The market’s depth, liquidity, and risk-return spectrum make it indispensable to modern finance, influencing monetary policy, interest rates, and economic growth worldwide.
2. The Role and Importance of Fixed Income Markets
The global fixed income market serves several critical economic functions:
Capital Formation:
Governments and corporations issue bonds to fund infrastructure projects, corporate expansion, research, and public programs. Without bond markets, large-scale financing would rely solely on bank loans, limiting growth.
Monetary Policy Implementation:
Central banks conduct open market operations primarily using government securities. By buying or selling these securities, they manage liquidity, control interest rates, and influence inflation.
Benchmark for Other Assets:
Government bond yields act as a benchmark for pricing corporate bonds, equities, and even mortgages. The risk-free rate, derived from sovereign bonds, forms the foundation for asset valuation models globally.
Portfolio Diversification and Risk Management:
Bonds often move inversely to equities during downturns, providing diversification benefits. Institutional investors use them to balance portfolio risk and stabilize returns.
Safe-Haven Investment:
During financial uncertainty or geopolitical instability, investors flock to high-quality government bonds (such as U.S. Treasuries or German Bunds), seeking safety and liquidity.
3. Major Segments of the Global Bond Market
The fixed income universe comprises several segments, each catering to different issuers, investors, and risk profiles.
3.1. Government Bonds
Issued by national governments, these are considered the safest investments in the market.
Sovereign Bonds: Examples include U.S. Treasuries, U.K. Gilts, Japanese Government Bonds (JGBs), and Indian Government Securities (G-Secs).
Emerging Market Debt: Countries like Brazil, Mexico, or South Africa issue bonds denominated in local or foreign currency. These carry higher yields due to higher default risk.
Government bonds are critical for monetary policy, as their yields reflect market expectations of inflation and interest rates.
3.2. Corporate Bonds
Corporations issue bonds to raise capital for operations, expansion, or refinancing existing debt.
Investment-Grade Bonds: Issued by financially strong corporations (rated BBB- or higher).
High-Yield (Junk) Bonds: Issued by riskier companies offering higher yields to compensate for credit risk.
Corporate bonds are vital for economic expansion, providing businesses with an alternative to equity financing.
3.3. Municipal Bonds
Issued by states, cities, or local authorities to finance public projects like roads, hospitals, and schools. In countries like the U.S., municipal bonds offer tax-exempt interest income, making them attractive to individual investors.
3.4. Supranational and Sovereign Agency Bonds
Organizations such as the World Bank, European Investment Bank (EIB), or Asian Development Bank (ADB) issue bonds to fund development projects. These securities often enjoy high credit ratings and are used to promote sustainable financing globally.
3.5. Structured and Securitized Products
These include Mortgage-Backed Securities (MBS), Asset-Backed Securities (ABS), and Collateralized Debt Obligations (CDOs). They pool loans or receivables and repackage them into tradable securities. Structured finance became notorious after the 2008 financial crisis but remains a vital part of credit markets.
4. Key Participants in the Global Bond Market
Issuers:
Governments, municipalities, corporations, and supranational agencies.
Their objective is to raise funds at the lowest possible cost.
Investors:
Institutional Investors: Pension funds, insurance companies, mutual funds, and sovereign wealth funds dominate demand due to their large asset bases and need for steady returns.
Retail Investors: Participate through direct purchases or mutual funds.
Foreign Investors: Often buy sovereign and corporate bonds for yield diversification and currency exposure.
Intermediaries:
Investment banks underwrite and distribute bond issues.
Dealers, brokers, and electronic trading platforms facilitate secondary market trading.
Regulators and Rating Agencies:
Agencies like Moody’s, S&P Global, and Fitch Ratings assess issuer creditworthiness.
Regulators (like the SEC, ESMA, or SEBI) oversee transparency, disclosure, and market integrity.
5. Bond Valuation and Pricing Mechanisms
The value of a bond depends primarily on three factors — coupon rate, maturity, and prevailing market interest rates.
5.1. Present Value of Cash Flows
A bond’s price equals the present value of its future cash flows (coupons and principal). When market interest rates rise, bond prices fall, and vice versa. This inverse relationship between yields and prices defines fixed income market dynamics.
5.2. Yield Measures
Current Yield: Annual coupon divided by current price.
Yield to Maturity (YTM): The internal rate of return if held to maturity.
Yield Spread: The difference between yields of different securities, indicating relative risk.
5.3. Credit and Duration Risk
Credit Risk: Possibility of default by the issuer.
Duration: Measures bond price sensitivity to interest rate changes. Longer-duration bonds are more sensitive to rate movements.
6. Global Market Size and Regional Overview
6.1. United States
The U.S. has the world’s largest bond market, valued over $50 trillion. U.S. Treasuries are considered the global benchmark for risk-free assets. The Federal Reserve’s actions in buying or selling Treasuries directly impact global liquidity.
6.2. Europe
The Eurozone bond market includes German Bunds (considered ultra-safe) and peripheral debt from countries like Italy, Spain, and Greece. The European Central Bank (ECB) manages yields via quantitative easing and bond-buying programs.
6.3. Asia-Pacific
Japan’s bond market, dominated by JGBs, is the largest in Asia, though yields remain extremely low. China’s bond market has grown rapidly, becoming a key avenue for global investors seeking exposure to yuan-denominated assets. India’s G-Sec market is expanding, supported by reforms that enhance foreign participation.
6.4. Emerging Markets
Countries in Latin America, Africa, and Eastern Europe issue both local and dollar-denominated bonds. These offer higher returns but carry risks such as currency depreciation and political instability.
7. Fixed Income Derivatives and Innovations
Derivatives based on bonds—such as futures, options, swaps, and credit default swaps (CDS)—allow investors to hedge or speculate on interest rate and credit movements.
Interest Rate Swaps: Exchange fixed and floating rate payments to manage rate exposure.
Credit Default Swaps: Provide insurance against bond default.
Bond Futures: Allow hedging of portfolio value against rate changes.
The rise of Exchange-Traded Funds (ETFs) and green bonds has further diversified access and objectives within fixed income investing.
8. Influence of Macroeconomic Factors
Bond markets are deeply intertwined with macroeconomic conditions.
Interest Rates:
Central banks’ rate decisions directly affect bond yields. A rate hike lowers bond prices, while cuts drive them higher.
Inflation:
Rising inflation erodes the real return of fixed-income securities, leading investors to demand higher yields.
Fiscal Policy:
Government deficits increase bond supply, potentially pushing yields upward.
Currency Movements:
Exchange rate fluctuations impact returns on foreign-denominated bonds.
Global Risk Sentiment:
During crises, investors move funds from risky assets to safe-haven bonds, causing yield compression in developed markets.
9. Technological Evolution and Market Infrastructure
Modern bond markets are increasingly electronic, transparent, and efficient.
Electronic Trading Platforms: Platforms like Tradeweb and MarketAxess have revolutionized secondary bond trading.
Blockchain and Tokenization: Tokenized bonds and blockchain-based settlements are improving speed, transparency, and cost efficiency.
AI and Big Data Analytics: Used for credit analysis, risk modeling, and market forecasting.
These innovations are making fixed income markets more accessible and integrated across borders.
10. ESG and Green Bond Revolution
Environmental, Social, and Governance (ESG) investing has reshaped the bond landscape. Green bonds finance environmentally sustainable projects such as renewable energy and clean transportation.
The global green bond market surpassed $2 trillion in cumulative issuance by 2025.
Sustainability-linked bonds tie coupon payments to ESG performance metrics, promoting responsible corporate behavior.
Governments, development banks, and corporations alike are leveraging ESG bonds to align with global climate goals and attract sustainability-focused investors.
Conclusion
The global bond and fixed income markets are the quiet yet powerful engines of global finance. They enable governments to fund development, corporations to grow, and investors to achieve stability and income.
In an era marked by technological transformation, sustainability goals, and shifting monetary landscapes, fixed income markets are evolving rapidly. The interplay of interest rates, inflation, and global capital flows continues to shape their dynamics.
As the world transitions into a more interconnected, digital, and climate-conscious financial system, the bond market remains indispensable—not just as a financing mechanism but as the foundation upon which the modern economy rests.
The ability of fixed income markets to adapt—through innovation, transparency, and sustainability—will determine their continued strength and relevance in the decades ahead.  Long

VAGX ETF: A Hidden Gem in an Era of Economic UncertaintyIn a world of shifting economic tides, investors are constantly searching for assets that offer both stability and growth potential. The Vanguard Global Aggregate Bond UCITS ETF (VAGX) may be one such opportunity, quietly accumulating strength amid global economic fluctuations.
Understanding VAGX ETF’s Accumulation Phase
VAGX tracks the Bloomberg Global Aggregate Float Adjusted and Scaled (CHF Hedged) index, which includes a diversified mix of corporate and government bonds. Since its inception in September 2021, the ETF has steadily grown, accumulating assets and reinvesting interest income to enhance long-term value. With 8,891 holdings and a low expense ratio of 0.10%, it offers broad exposure to global fixed-income markets.
Macroeconomic Landscape: Tariffs, Inflation, and Interest Rates
The global economy is at a critical juncture, with policy shifts and trade tensions shaping investment strategies. Key factors influencing VAGX’s potential include:
Tariffs & Trade Tensions: Recent tariff escalations have heightened uncertainty, impacting global trade and economic growth. This environment makes bond-based ETFs like VAGX attractive as investors seek stability.
Inflation Trends: Inflation is projected to moderate slightly in 2025, but remains a concern for central banks. Bond ETFs, particularly those with investment-grade holdings, can serve as a hedge against inflationary pressures.
Interest Rate Outlook: The Federal Reserve’s stance on interest rates has been influenced by inflation and trade policies. While rate cuts may be delayed, fixed-income assets like VAGX can provide a reliable store of value in uncertain times.
Why VAGX Could Be a Strong Long-Term Holding
Diversification: Exposure to global bonds mitigates risk compared to single-market investments.
Accumulating Nature: Interest income is reinvested, compounding returns over time.
Hedged Against Currency Fluctuations: CHF hedging reduces volatility from exchange rate movements.
Low Expense Ratio: At 0.10%, it remains cost-efficient for long-term investors.
Final Thoughts
As the global economy navigates inflationary pressures, trade uncertainties, and interest rate shifts, VAGX ETF stands out as a stable, accumulating asset with strong long-term potential. Investors looking for a reliable store of value and gradual appreciation may find this ETF an attractive addition to their portfolios.
SIX:VAGX INDEX:BTCUSD SP:SPX TVC:DXY OANDA:XAUUSD BITSTAMP:BTCUSD $ EURONEXT:N100 SIX:SMI TVC:SXY  Long

U.S. Aggregate T-Bond Market. Fears & Greed Awakening. Series IIIt's gone 3 weeks or so, since Mr. Trump has secured a win over his Democrat-rival Kamala Harris in the 2024 U.S. presidential election, as it declared by the Associated Press.
Since that, a lot of stocks soared in a meme-style mode, while Bitcoin almost cleared $100,000 and Dogecoin soared amid Trump-fueled crypto rally.
However macro data still stoke fears over a possible recession and the notion that the Federal Reserve could be too slow with cutting interest rates. Non-farm payroll added just 12K new places last month. And the ISM manufacturing index, a barometer of factory activity in the U.S., came in at 46.5%, worse than expected and a signal of economic contraction.
Fresh ISM release is scheduled on Dec 02, 2024 (47.5 points forecasted), and labor market data is on the radars on Friday, Dec 06 (+183K non-farm payroll forecasted).
The main technical graph is for U.S. Core Aggregate T-Bond Market ETF (AGG), in total return format, and it indicates on Reversed Head-and-Shoulders technical structure in development, as it's been discussed in earlier published ideas.
Moreover, huge 200-Week SMA breakthrough is on the investments radars also.
What does it mean for Bond Market?.. Potentially "Good", to jump to all-time high.
... and for Stock Market?.. Potentially "Also Good", until it reach the fever pitch.
US Markets Defy Tradition: Stocks and Bonds Rise Together◉ Introduction
The relationship between bond yields and stock prices is crucial in understanding financial markets. Generally, bond yields and stock prices exhibit an inverse relationship, meaning that as bond yields rise, stock prices tend to fall, and vice versa. This dynamic is influenced by several factors, including opportunity costs, corporate financing costs, investor behaviour, and economic conditions.
◉ Opportunity Cost of Investing in Equities
● Definition: Bond yields represent the return on fixed-income investments. When bond yields increase, they provide a benchmark for what investors expect from equities.
● Impact: Higher bond yields make stocks less attractive unless they can offer significantly higher returns.
● Example: If a 10-year government bond yields 7%, investors may require at least a 12% return from stocks (including a risk premium of around 5%) to justify the additional risk. If expected stock returns fall below this level, investors may shift their capital from stocks to bonds, leading to a decline in stock prices.
◉ Corporate Financing Costs
● Definition: Rising bond yields increase the cost of borrowing for companies.
● Impact: Higher interest expenses can reduce corporate profits and cash flow, leading to lower stock valuations.
● Example: If a company’s debt interest rises from 5% to 8%, its net income may decrease significantly due to higher interest payments. This can prompt investors to reassess the company’s stock value negatively.
◉ Investor Behaviour and Market Dynamics
● Definition: Investor sentiment plays a significant role in the bond-stock relationship.
● Impact: When bond yields rise, many investors may sell stocks in favour of bonds, seeking safer returns.
● Example: During periods of economic uncertainty, such as the COVID-19 pandemic in early 2020, rising bond yields led many investors to move capital into bonds, resulting in significant declines in stock indices like the S&P 500.
◉ Economic Conditions and Inflation Expectations
● Definition: Bond yields are influenced by inflation expectations and overall economic growth.
● Impact: Rising inflation typically leads to higher bond yields, which can negatively impact stock prices as investors anticipate reduced future earnings.
● Example: Following the 2008 financial crisis, low inflation kept bond yields down, supporting rising stock prices as investors sought higher returns from equities amid low yields on bonds.
◉ Historical Context and Trends
● Definition: Historically, lower bond yields correlate with higher stock prices due to lower discount rates on future cash flows.
● Impact: Low borrowing costs encourage corporate investment and growth.
● Example: The bull market from 2009 to 2020 was fueled by persistently low Treasury yields, allowing companies to borrow cheaply and reinvest in growth initiatives.
◉ The Role of Defaults in Bond Yields
● Definition: The probability of default significantly influences bond yields.
● Impact: Increased default risk leads to higher required yields on corporate bonds, prompting a flight to safer government bonds.
● Example: During the 2008 financial crisis, rising default expectations for many companies resulted in corporate bonds offering higher yields as investors sought safety in government securities.
◉ Recent Market Trends: A Post-Election Analysis
The recent market trends following Donald Trump's election as President of the United States have been quite remarkable. Typically, when equity prices rise, bond yields fall, and vice versa. However, over the last month, both equity prices and bond yields have increased simultaneously.
This unusual phenomenon can be attributed to investor expectations of Trump's economic policies. The equity market has experienced a significant surge, with major indices like the S&P 500 and the Dow Jones Industrial Average reaching new highs. This rally is largely driven by expectations of:
● Corporate Tax Reductions: Expected to boost corporate earnings and drive economic growth.
● Infrastructure Spending: Anticipated to create new job opportunities and stimulate economic activity.
● Deregulation: Expected to reduce compliance costs and promote business growth.
On the other hand, the bond market has experienced a significant rise in yields, driven by investor expectations of higher inflation and higher interest rates. This is largely due to Trump's economic policies, which are expected to lead to higher borrowing costs due to unchanged or higher interest rates, causing bond prices to decline and yields to rise.
◉ Conclusion
The recent rise in bond yields and stock prices marks a significant change from past trends. This shift shows how economic policy, investor feelings, and market forces interact, emphasizing the constantly changing nature of global financial markets.  Education

Short 
Short 
 Short

Title: Ringgit Rally Fuels Foreign Bond Inflows: A Deep DiveThe Malaysian ringgit has experienced a substantial appreciation, driven by robust foreign investment in the domestic bond market. A surge in capital inflows, totaling RM5.5 billion in July alone, has propelled the ringgit's performance. This analysis delves into the underlying economic factors driving this trend, examining key indicators and assessing the outlook for sustained growth. While the current trajectory is promising, investors must remain cognizant of potential global economic headwinds.
Key Points:
Strong foreign inflows into Malaysian bonds
Ringgit's appreciation driven by multiple factors
Deep dive into economic indicators shaping USD/MYR
Assessment of Malaysia's economic fundamentals
Cautious outlook amid potential global challenges
Key Drivers of the Ringgit Rally:
Currency Appreciation: Investors are buying bonds unhedged, betting on further ringgit gains.
Strong Domestic Economy: Malaysia's economic robustness and expected interest rate stability bolster investor confidence.
Global Factors: Anticipated Federal Reserve rate cuts weakening the USD benefit the ringgit.
Economic Indicators Influencing USD/MYR:
Interest Rate Differentials: Higher local rates attract foreign capital, strengthening the ringgit.
Inflation Rates: Low inflation supports currency value.
T rade Balance: Surpluses strengthen the ringgit, reflecting Malaysia's export strength.
Economic Growth: Domestic consumption and government spending drive economic growth, enhancing the ringgit's appeal.
Political Stability: A stable political climate attracts investment, supporting the currency.
Global Economic Conditions: Global trends and geopolitical events affect investor risk appetite and currency flows.
Outlook:
Malaysia's diversified economy, fiscal prudence, and growing middle class underpin the ringgit's strength. Efforts to boost foreign direct investment and exports further support currency appreciation. However, global uncertainties, US monetary policy shifts, and geopolitical tensions could introduce volatility. Short 
Macro Monday 30~U.S. Net Treasury International Capital FlowsMacro Monday 30
U.S. Net Treasury International Capital Flows
In essence the U.S. Net Treasury International Capital Flows (US TIC Flows) refer to the movement of funds into or out of the United States through the purchase or sale of U.S. Treasury securities by foreign investors and governments. These flows of capital are an essential component of the overall balance of payments, reflecting the financial transactions between the United States and the rest of the world.
What does the data represent exactly?
The U.S. Treasury International Capital (TIC) system is compiled by the U.S. Department of the Treasury and provides information on cross-border financial transactions. The TIC data include details on purchases and sales of various U.S. financial assets and liabilities, such as Treasury securities, corporate bonds, equities, and banking flows.
In simple terms the Foreign Purchases of U.S. Securities (inflows) are taken away from the U.S. Purchases of Foreign Securities (outflows) to present a overall net figure. The net result of these two components determines whether there is a net inflow or outflow of capital.
What are the drivers of positive & negative flows?
Positive Flows (>0 on chart)
POSITIVE FLOWS in U.S Net Treasury International Capital result from factors such as attractive U.S. interest rates, a stable domestic economy, and global uncertainty that drives foreign investors to seek the safety of U.S. Treasury securities. During these periods, there is a net inflow of capital into the United States pressing the number higher above zero.
Negative Flows (<0 on chart)
Conversely, NEGATIVE FLOWS occur when other countries offer higher returns, there are concerns about the U.S. economic outlook, or global risk aversion prompts investors to repatriate funds. Exchange rate movements also play a role, as a stronger U.S. dollar can make U.S. assets less appealing.
The interplay of the above mentioned factors influences the direction of international capital flows, which impacts the balance of purchases and sales of U.S. Treasury securities by foreign and domestic investor.
Now that we have a general sense of what’s driving the data, and what makes an overall net positive and or net negative flow, let’s have a look at the chart.
The Chart
✅ Since Jan 2019 there has been an upward trend in Treasury Inflows into the U.S (Black Arrow).
❌This upward trend had one sudden interruption causing a decline from Mar - May 2023 going from positive inflows of $114B to negative outflows of $159.4B, the timing of which coincided with the 2023 U.S Banking Crisis where three small-to-mid size U.S. banks failed.
✅ Since the Banking Crisis in May 2023 Treasury Capital flows have moved from overall negative outflows of $159.4B to overall positive inflows of $260.2B. A major turn around and reversion to the long term trend.
✅The recent surge in positive inflows to $260.2B are the highest recorded since August 2022 ($275B)
In summary inflows to U.S Treasuries have been in an general uptrend since January 2019 with one brief interruption from Mar – May 2023 and inflows have increased significantly in recent months and look like they may be about to take out the Aug 2022 highs.
Recession Patterns
1. More isolated recessions that were not globally systemic events led to positive net inflows into the U.S. Treasury however larger global events led to outflows from U.S. Treasuries, particularly if those global events involved the U.S. engaging in foreign conflicts.
▫️ During the DotCom Crash (No. 3 on the chart) – The tech sector was badly hit but it was not necessarily a global recession with the associated geopolitical turmoil. Foreign investors sought safety in the U.S. Treasury Market during this time.
▫️ Similarly during the brief Gulf War Recession (No. 4 on the chart) you can see that initially, there was increased net inflows however in Jan 1991 inflows sharply turned to outflows which coincided with the U.S. led invasion of Kuwait (a response to Iraq’s invasion of Kuwait). This was considered a global event and thus led to an exodus of outflows and repatriation of funds from the U.S Treasury Market.
▫️ More recently during the Great Financial Crisis (no. 2 on the chart) and the COVID-19 Crash (No. 1 on the chart) there was a significant outflow from U.S. Treasuries due to the magnitude of these global events. You can imagine foreign market participants clawing funds back into their respective countries to batten the hatches and get into a defensive financial position with global systemic risks high. Better to have a bird in the hand than two in the bush when the bush is on fire.
▫️One other pattern worth mentioning is highlighted in yellow on the chart with an A, B and C. Prior to the Great Financial Crisis and COVID-19 crashes we first had a reduction in overall U.S. Net Treasuries of $373B (A on chart) and $393B (B on chart), respectively. Within 13 to 16 months of both treasure drawdowns we had a recession. We recently had a drop of $437B (C on chart) which ended in May 2023. If history repeats and we had a recession within 13-16 months of this happening, this would be sometime between June and Sept 2024. An alternative view would be that the increase in declines from $373B (A) to $393B (B) to $437B (C) may correspond with the shortening timeframes from 16 months(A) to 13 months(B) to potentially 10 months(C) for the current $437B drop (C on the chart). This would suggest March/April 2024 as a potential recession timeframe (based on the historic reductive time pattern).
The U.S. Net Treasury International Capital Flows is a fascinating chart to keep an eye on and should be added to the economic data armory as it will help us interpret what is really going on in the treasury market (there is a lot of false narratives out there ATM). It is also useful in informing us on what the global perspective is in terms of systemic risk vs isolated risk, and also from a historic recessionary standpoint offers value.
The best investors in the world call the bond market the market of truth but I have found it hard to find a chart that illustrates this through a global lens UNTIL today. This chart captures that beautifully.
Thanks for coming along again
PUKA Long 
Long 
Short 
Short