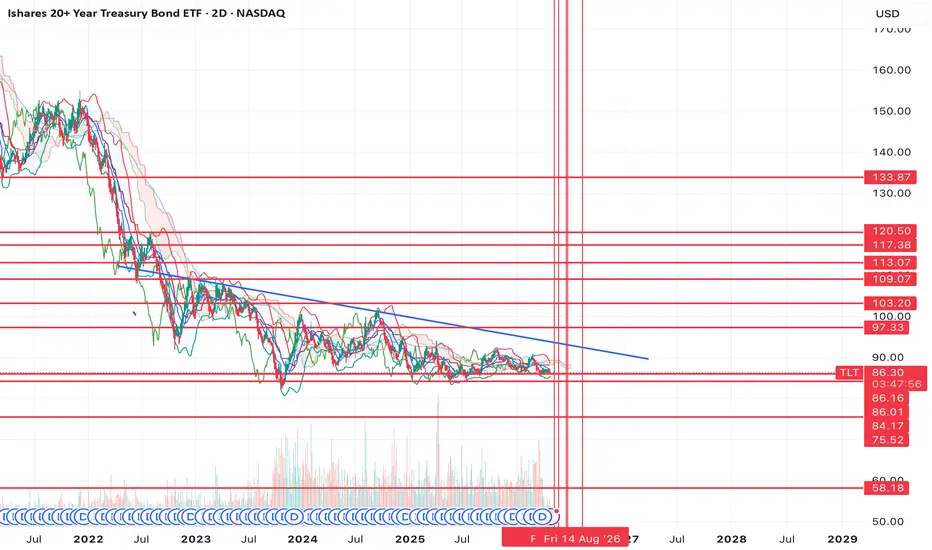
Long

EUR/USD Rises as U.S. Dollar Buckles Under Bond-Market StressEUR/USD traded higher on Thursday, August 20 as the U.S. Dollar came under pressure after Treasury moved to expand long-dated bond buybacks in an effort to calm stress at the long end of the curve. The move initially pulled yields lower and hit the U.S. Dollar, with markets treating it as a signal that policymakers are becoming more sensitive to the rise in long-term borrowing costs. The Euro caught the bid, but the rally was more about U.S. Dollar weakness than a sudden improvement in the Eurozone growth story.
For the Eurozone, the ECB rate path remains defined by inflation risk rather than economic strength. Higher energy prices and lingering supply pressures are keeping another ECB hike on the table, even as growth across the bloc remains uneven. That gives the Euro some support, but it is not a clean bullish setup. EUR/USD is moving because the U.S. side of the trade is cracking first: bond-market stress, Fed uncertainty, and a U.S. Dollar long trade that is being forced to unwind.
EUR/USD broke above the descending trendline that has capped rallies since the January spike, cleared the moving-average cluster, and pushed into the mid-1.16s. That shifts the short-term structure from “sell every rally” to “respect the breakout.” The Euro is no longer stuck underneath the downtrend. It has forced the U.S. Dollar back onto defense.
The current setup may favor buying pullbacks into 1.1620-1.1600, using a close back below 1.1550 as the line in the sand. If buyers defend that zone, EUR/USD has room toward 1.1750, then 1.1800. That 1.1800 area is the next major test because it lines up with the spring failure zone. It would likewise line up with the Dollar Index ( TVC:DXY ) returning towards its yearly lows. For shorts, the setup is not “sell because it rallied.” The better bearish case needs time because it would be a failed breakout: price loses 1.1600, slips back under the moving-average cluster, and momentum rolls over. Until that happens, fading the Euro is fighting the tape. A Skeptical Trader's Guide to Trading Repeated Failed BreakoutsTechnical patterns often look straightforward in textbooks. A recognizable formation develops, price eventually breaks through a key level, and traders begin evaluating potential opportunities. In reality, however, markets are rarely that cooperative.
One of the more challenging situations traders face occurs when a pattern appears valid, yet repeatedly fails to deliver the anticipated breakout. Each failed attempt chips away at confidence. The pattern may still be technically intact, but the market's inability to follow through can create growing skepticism among participants.
This distinction is important because technical analysis is not only about identifying patterns. It is also about understanding how market participants are reacting to those patterns.
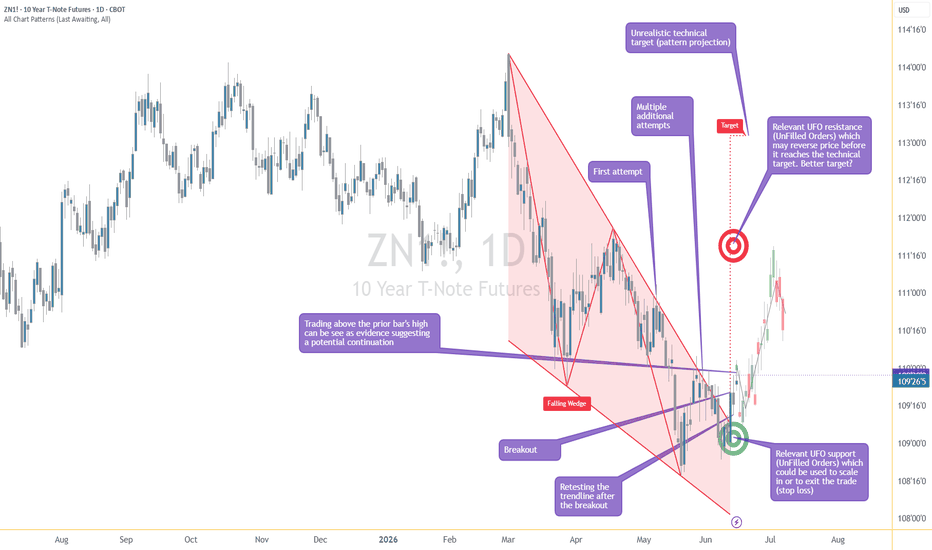
The daily chart of 10-Year T-Note Futures provides an interesting case study of this concept. A Falling Wedge pattern developed over several months and eventually produced an upside breakout. Yet before that breakout finally gained traction, multiple attempts had already failed.
For some traders, those repeated failures may have been enough to justify a more conservative approach.
Rather than focusing on predicting what would happen next, this article examines how a trader might manage uncertainty when a technical pattern begins to lose credibility after several unsuccessful breakout attempts.
Understanding the Falling Wedge
The Falling Wedge is a chart pattern characterized by two downward-sloping trendlines that gradually converge over time. As the pattern develops, price fluctuations become progressively narrower, suggesting a reduction in downside momentum.
From a technical perspective, the pattern is often interpreted as a potential reversal or continuation formation depending on the broader market context. The key observation is that sellers continue pushing prices lower, but each subsequent push tends to lose strength.
Eventually, price reaches a point where a breakout above the upper trendline becomes possible.
Many technical traders monitor these formations because they provide clearly defined boundaries. The pattern itself offers structure, while the breakout provides a framework for developing a trading hypothesis.
However, one important reality is frequently overlooked.
Patterns do not exist in a vacuum.
The quality of a breakout often depends on what happened before the breakout occurred.
A breakout that succeeds on the first attempt may be viewed differently than a breakout that follows multiple failed attempts.
This distinction becomes particularly relevant in the case study shown on the chart.
When a Pattern Starts Losing Credibility
One of the most valuable lessons technical analysis can teach is that markets are ultimately driven by participant behavior.
A chart pattern can remain technically valid for weeks or months. Nevertheless, if traders repeatedly observe failed breakout attempts, confidence in the pattern may gradually deteriorate.
This phenomenon can be described as pattern fatigue.
Pattern fatigue occurs when a market repeatedly attempts to move in a particular direction but fails to sustain momentum. Over time, participants become increasingly skeptical about the probability of success.
The Falling Wedge shown on the chart illustrates this concept particularly well.
Throughout May, multiple attempts were made to break above the upper trendline of the pattern. Each attempt appeared promising initially, only to reverse and fall back into the structure.
From a purely technical perspective, the pattern remained valid.
From a psychological perspective, however, confidence was likely declining.
A trader observing these repeated failures might reasonably begin asking several questions:
Is the pattern still relevant?
Are buyers truly in control?
Is this breakout attempt any different from the previous ones?
Should additional confirmation be required before acting?
These questions reflect a healthy degree of skepticism.
In many cases, skepticism is not a weakness. It can be a risk-management tool.
The objective is not to become permanently bearish or bullish. The objective is simply to require stronger evidence before committing capital.
This is where trading styles often begin to diverge.
Aggressive Traders Versus Conservative Traders
Not all traders approach chart patterns the same way.
An aggressive breakout trader may choose to enter as soon as price moves beyond the trendline. The logic is straightforward: if the breakout succeeds, entering early may provide favorable positioning.
There is nothing inherently wrong with this approach.
However, repeated breakout failures can cause some traders to modify their process.
A more conservative trader may decide that the pattern itself is no longer sufficient evidence.
Instead, additional confirmation may be required.
This confirmation can take many forms:
Increased volume.
Stronger momentum.
A successful retest.
Market structure confirmation.
Support and resistance validation.
A continuation signal following a pullback.
The key idea is simple.
The more uncertainty created by previous failed attempts, the more evidence some traders may require before entering a position.
The chart provides an excellent example of how such an approach could be implemented.
Conservative Alternative #1: Waiting for the Pullback
After the eventual breakout occurred, one possible approach would have been to avoid chasing price immediately.
This concept is especially relevant after a series of failed breakouts.
Repeated failures often condition traders to expect disappointment. As a result, buying immediately after a breakout can feel uncomfortable.
A more conservative trader may instead choose to wait for price to revisit an area of support.
On the chart, a relevant buy-side UFO (UnFilled Orders) support zone was located between:
109’12’0 and 108’27’0
Interestingly, price retraced into that area immediately following the breakout.
For traders using market structure alongside technical patterns, this retracement provided an opportunity to evaluate whether buyers were still willing to defend previously identified support.
Rather than entering during the breakout itself, the trader could have waited for price to return toward the support zone and then assessed whether the original bullish thesis remained intact.
This approach introduces an important advantage.
Instead of reacting emotionally to the breakout, the trader allows the market to provide additional information.
The retracement becomes a test.
If buyers continue defending the support area, confidence in the breakout may increase.
If support fails, the trader avoids participating in a potentially unsuccessful setup.
Neither outcome guarantees success.
The objective is simply to improve decision quality through patience.
Conservative Alternative #2: Waiting for Confirmation After the Pullback
Some traders may choose to be even more selective.
For them, the retracement itself is still not enough.
After multiple failed breakout attempts, they may require evidence that buyers have regained control following the pullback.
This is where continuation confirmation becomes relevant.
On the chart, the retracement day established a clear high and low.
Once price subsequently traded above the high of that retracement day, the market provided another piece of information.
Buyers were no longer merely defending support.
They were actively pushing price beyond the prior day's range.
From a price-action perspective, this behavior can be interpreted as evidence of renewed upside participation.
Again, this does not guarantee that prices will continue higher.
No chart pattern can provide certainty.
However, for a trader who has already witnessed several failed breakouts, this additional confirmation may help justify participation.
The important lesson is not whether the trade ultimately succeeds.
The important lesson is understanding how confirmation can be layered into a trading process when confidence in a pattern has been weakened by repeated failures.
A technical pattern does not become more reliable simply because it has existed for longer.
In some situations, repeated failures may justify raising the standard of evidence before acting.
What If the Pattern Works? What If It Fails?
Every trading hypothesis eventually arrives at two critical questions:
What happens if the market moves in the anticipated direction?
What happens if the market proves the hypothesis wrong?
Surprisingly, many traders spend far more time thinking about the first question than the second.
Yet from a risk management perspective, both deserve equal attention.
In the case of the Falling Wedge shown on the chart, a traditional chart-pattern trader might begin by calculating a projected target.
This process typically involves measuring the height of the pattern and projecting that distance from the breakout point.
Applying this methodology to the current structure produces a projected objective near:
113’03’0
There is nothing inherently wrong with this technique. It has been used by technical analysts for decades and provides a systematic way of estimating potential price movement.
However, projected targets have one notable limitation.
They are purely mathematical.
The calculation itself does not consider the actual structure of the market that exists between the breakout point and the projected destination.
This is where some traders may choose to incorporate additional layers of analysis.
Looking Beyond the Pattern Projection
One challenge with pattern projections is that markets rarely move in straight lines.
Even when a pattern functions as expected, price frequently encounters support and resistance levels before reaching a theoretical objective.
Ignoring those areas can sometimes result in unrealistic expectations.
The chart highlights several relevant UFO resistance zones positioned below the projected target.
The first significant resistance area begins near:
111’12’5
This observation creates an interesting dilemma.
Should a trader focus exclusively on the textbook pattern target?
Or should market structure influence trade management decisions?
Reasonable traders may reach different conclusions.
Some may continue targeting the full projected objective.
Others may decide that the presence of meaningful resistance justifies a more conservative approach.
In this case, a trader emphasizing market structure might view 111’12’5 as a logical area to evaluate potential profit-taking decisions.
The rationale is straightforward.
If sellers have previously demonstrated interest in that region, price could encounter friction before reaching the larger technical projection.
The objective is not to predict a reversal.
Rather, it is to acknowledge the existence of nearby market structure that could influence future price behavior.
This distinction is important because risk management is often less about certainty and more about preparation.
Defining Invalidation
While traders frequently discuss entry techniques and profit objectives, invalidation is equally important.
Every trading idea begins with a hypothesis.
In this example, the hypothesis may be summarized as follows:
The Falling Wedge breakout remains valid and buyers continue to maintain control above support.
If that assumption proves incorrect, the trader needs a predefined mechanism for exiting the position.
Returning to the chart, the previously discussed UFO support zone extends between:
109’12’0 and 108’27’0
For traders using this area as a key component of their analysis, a move below the lower boundary may suggest that the bullish thesis is weakening.
More importantly, it could indicate that the breakout itself has failed.
This concept highlights one of the advantages of combining chart patterns with market structure.
The pattern identifies opportunity.
The surrounding structure helps define invalidation.
Rather than placing a stop loss at an arbitrary distance, some traders prefer using levels that directly challenge the assumptions underlying the trade.
If the market moves beneath the support zone, the original rationale for participating may no longer be present.
Whether the trader ultimately exits or reassesses the situation becomes a matter of individual process, but the principle remains the same:
A hypothesis should always include a mechanism for determining when it is no longer valid.
Understanding Treasury Futures That Trade in Fractions
Treasury futures are unique compared to many other futures contracts because they are quoted using fractional pricing conventions.
Traders familiar with stock indices, energy products, currencies, or metals often encounter a learning curve when first analyzing Treasury markets.
Instead of conventional decimal pricing, Treasury futures are generally quoted in points and fractions of a point.
For example, a quotation such as:
109’12’0
should not be interpreted in the same manner as a stock trading at 109.12.
Treasury futures use a fractional system where each tick equals 1/2 of 1/32 of one point.
This convention dates back many years and remains widely used throughout fixed-income markets.
Understanding this pricing methodology is important because even relatively small price movements can represent meaningful changes in contract value.
For newer market participants, Treasury futures may initially appear unusual compared to other futures markets.
However, once the fractional pricing structure becomes familiar, chart interpretation becomes considerably easier.
The key takeaway is simple:
Always understand how a market is quoted before evaluating risk, reward, or position sizing.
10-Year T-Note Futures Contract Specifications
The 10-Year Treasury Note Futures contract is one of the most actively followed interest-rate futures products.
Some key contract characteristics include:
Contract size: $100,000 face value of a U.S. Treasury Note.
Tick value: 1/2 of 1/32 of one point = $15.625 per contract.
Margin requirement: ~$1875 per contract.
Margin requirements are subject to change, traders should always verify current figures directly through their brokerage provider before evaluating a trade.
Because Treasury futures reflect expectations and activity within the fixed-income market, they are frequently monitored by traders, portfolio managers, hedgers, and institutional participants seeking exposure to interest-rate movements.
The contract's liquidity and long history make it a widely recognized benchmark within the Treasury futures complex.
Illustrative Trade Case Study
Using the chart as an educational example, a conservative trader might construct the following hypothetical framework:
Observe the Falling Wedge breakout.
Recognize the existence of multiple failed breakout attempts.
Wait for a retracement rather than immediately chasing the breakout.
Monitor the UFO support zone between 109’12’0 and 108’27’0.
Wait for price to demonstrate renewed upside decisiveness.
Observe price trading above the retracement day's high.
Use nearby UFO resistance around 111’12’5 as a potential area of interest.
Use a stop below the UFO support zone to define invalidation.
This example is not intended to suggest future market direction.
Instead, it demonstrates how additional confirmation can be incorporated into a trading process after repeated breakout failures create skepticism.
The educational lesson is not whether the trade succeeds.
The educational lesson is how a trader might adapt their process when confidence in a pattern has been weakened by prior unsuccessful attempts.
Risk Management: The Real Lesson Behind the Pattern
Many discussions about technical analysis focus on finding opportunities.
Far fewer discussions focus on managing uncertainty.
Yet uncertainty is the one characteristic present in every market.
The most valuable lesson from this chart may not be the Falling Wedge itself.
It may be the decision-making process surrounding the pattern.
Repeated failures created doubt.
Rather than ignoring that doubt, a conservative trader could choose to respond by requiring additional confirmation.
That confirmation might come from:
A successful retest.
Support validation.
Stronger price action.
Market structure alignment.
Trading above a key reference level.
Different traders will have different standards.
What matters is having a process.
A technical pattern should never be viewed as certainty.
It is merely a framework for organizing probabilities.
Risk management remains the mechanism that protects traders when those probabilities fail to materialize.
Conclusion
The Falling Wedge pattern discussed in this case study ultimately produced an upside breakout, but the path leading to that breakout is arguably more educational than the breakout itself.
Multiple failed attempts during May likely reduced confidence among many market participants. A trader who had witnessed those failures may have chosen not to trust the next breakout immediately.
Instead, patience could have become part of the strategy.
Waiting for a retracement.
Waiting for support to hold.
Waiting for price to trade above the retracement day's high.
Each additional requirement raises the threshold of evidence needed before participation.
Whether one agrees with that approach or not, the underlying principle remains valuable.
A technical pattern does not necessarily become more convincing simply because it remains on the chart longer.
Sometimes repeated failures justify becoming more selective.
In those situations, skepticism is not necessarily a sign of indecision.
It may simply be another form of risk management.
Data Consideration
When charting futures, the data provided could be delayed. Traders working with the ticker symbols discussed in this idea may prefer to use CME Group real-time data plan on TradingView: www.tradingview.com - This consideration is particularly important for shorter-term traders, whereas it may be less critical for those focused on longer-term trading strategies.
General Disclaimer
The trade ideas presented herein are solely for illustrative purposes forming a part of a case study intended to demonstrate key principles in risk management within the context of the specific market scenarios discussed. These ideas are not to be interpreted as investment recommendations or financial advice. They do not endorse or promote any specific trading strategies, financial products, or services. The information provided is based on data believed to be reliable; however, its accuracy or completeness cannot be guaranteed. Trading in financial markets involves risks, including the potential loss of principal. Each individual should conduct their own research and consult with professional financial advisors before making any investment decisions. The author or publisher of this content bears no responsibility for any actions taken based on the information provided or for any resultant financial or other losses.  Education
US 10Y Yield Holds Above Key Moving Averages as Momentum CoolsThe US Government Bonds 10-Year Yield remains in an elevated structure on the daily chart, with price holding above both the 50-day SMA near 4.39% and the 200-day SMA near 4.20%. This keeps the broader technical backdrop constructive, as the shorter-term average continues to trend above the longer-term average following the earlier upside shift.
Recent price action shows a pullback from the May high near the 4.70% area, followed by stabilization around the prior breakout zone near 4.45%. The latest candle has moved back above that level, suggesting buyers are attempting to defend former resistance as support. As long as yields remain above the rising 50-day SMA, the near-term structure may continue to lean bullish, though the recent rejection from the highs shows momentum has moderated.
The MACD remains above the zero line but has crossed lower, reflecting cooling upside momentum after the strong May advance. This does not necessarily invalidate the broader trend, but it does suggest the market may be moving from impulse into consolidation. RSI has also eased from elevated territory and is now recovering toward the mid-to-upper range, indicating momentum is no longer stretched while still holding above the neutral zone.
Overall, the chart presents a mildly bullish-to-neutral bias. The uptrend remains supported by price positioning above the 50-day and 200-day moving averages, while MACD and RSI point to a short-term pause after a strong rally. A continued hold above the 4.45% region would support the case for consolidation at higher levels, while weakness back below the 50-day SMA would signal a deeper reset in momentum.
-MW  Long

Long 
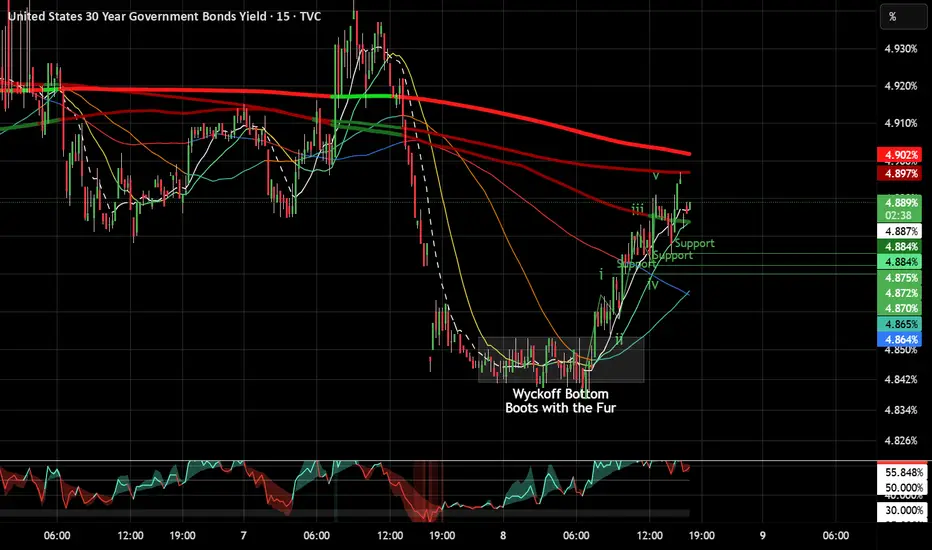
Bullish unless we close under 3.875%Not financial advice.
Comment if you please.
A new uptrend has been established in bond yields as we look back. The accumulation bottoming pattern is very textbook.
chartschool.stockcharts.com
“…all the fluctuations in the market and in all the various stocks should be studied as if they were the result of one man’s operations. Let us call him the Composite Man, who, in theory, sits behind the scenes and manipulates the stocks to your disadvantage if you do not understand the game as he plays it; and to your great profit if you do understand it.”
(The Richard D. Wyckoff Course in Stock Market Science and Technique, section 9, p. 1-2)
Based on his years of observations of the market activities of large operators, Wyckoff taught that:
The Composite Man carefully plans, executes, and concludes his campaigns.
The Composite Man attracts the public to buy a stock in which he has accumulated a sizeable line of shares by making many transactions involving many shares, in effect advertising his stock by creating the appearance of a “broad market.”
One must study individual stock charts with the purpose of judging the behavior of the stock and the motives of those large operators who dominate it.
With study and practice, one can acquire the ability to interpret the motives behind the action that a chart portrays. Wyckoff and his associates believed that if you could understand the market behavior of the Composite Man, you could identify many trading and investment opportunities early enough to profit from them. Long 
Long 
Short 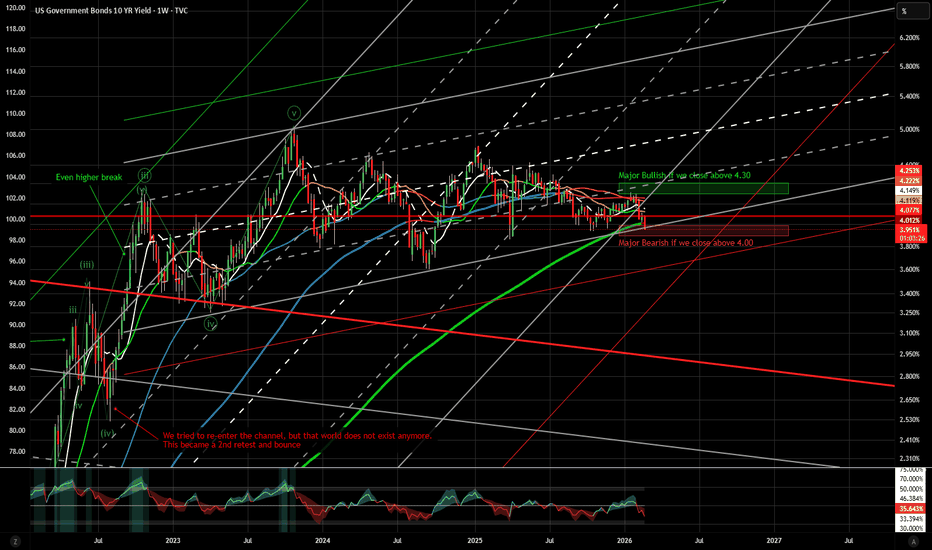
Long 
Long 
Long 
10-Year Treasuries Into FOMC: What to Expect1. Big Picture: What’s Been Driving Bonds?
Over the past several months, the U.S. Treasury market has been defined by diverging forces across the curve, the short end (2Y, 5Y) pricing near-term monetary policy outcomes and the long end (10Y, 30Y) reflecting inflation persistence, fiscal supply, and long-horizon term premium.
The short end has behaved like a proxy for rate-cut expectations, compressing aggressively whenever inflation cools or recession probability ticks higher. Meanwhile, the long end has been more sensitive to duration demand, bond auctions, and forward-looking macro risk, often moving independently when supply shocks or inflation surprises hit the tape.
The result? A curve driven by two narratives: policy timing vs long-run risk.
This sets the stage for next week’s meeting and the reaction likely depends less on the cut itself and more on the messaging around rate trajectory.
2. What did the Market do?
Following the U.S.–China tariff escalation in April (formerly referred to casually as the “Trump Tariff War,” though a better description is the Tariff Re-Escalation Phase), the ZN stabilized. Buyers stepped in between May to July 2025, compressing price toward the 112'08'0 region, which is a key daily resistance zone.
In early September, momentum shifted. Buyers overwhelmed offers and lifted prices through 112'08'0, and the move appears linked to expectations of a softer policy stance and improving forward inflation indicators during the first week of September.
Sellers responded at 113'07'0 area and market has been trapped in a three-month range between 113'25'0 high and 112'08'0 low.
This week, price rotated from the top of range and swept through the composite LVN 113'00'0 to 112'24'0, near the 1st 3 weeks of November composite VPOC.
3. What to Expect: Scenarios Into FOMC Week
Until the rate decision, compression seems likely.
Expect 2 way indecision before FOMC:
Expect two-way trade between 113'03'0 (LVN) and 112'24'0 (1st 3 weeks of Nov composite VPOC) as the market waits for the FOMC.
Bearish Scenario (Base case):
If sellers hold at 113'03'0, continuation lower toward 112'07'0 (range low / composite VAL)
Bullish Scenario:
If buyers reclaim 113'03'0 decisively, possible market move back up to 113'23'0 (Daily Range high), keeping the multi-month balance intact and potentially positioning for a breakout if FOMC guidance surprises dovish.
4. FOMC Risk: What Could Surprise the Market?
The market is currently pricing ~88.6% probability of a 25bps cut which means the cut itself is not the event. The surprise lies in the tone.
🟢 Bullish Bond Reaction (Yields lower) if:
Forward guidance hints at a sequence of cuts, not a one-off
Growth risks emphasized > inflation risks
Dovish dissent or language suggesting easing bias remains intact
🔴 Bearish Bond Reaction (Yields higher) if:
The Fed downplays future cuts or signals higher-for-longer
Inflation risk is prioritized
Dot-plot or press Q&A implies only one cut on table
Conclusion
Unless the press conference delivers a clear dovish or hawkish surprise, expect a similar indecisive, two-way response in the markets, similar to past FOMC market reactions.
What’s your call on ZN and the bond markets going into the week of FOMC? Drop a comment and give a boost so more traders can weigh in.
Disclaimer: This is not financial advice. Analysis is for educational purposes only; trade your own plan and manage risk.
Short 
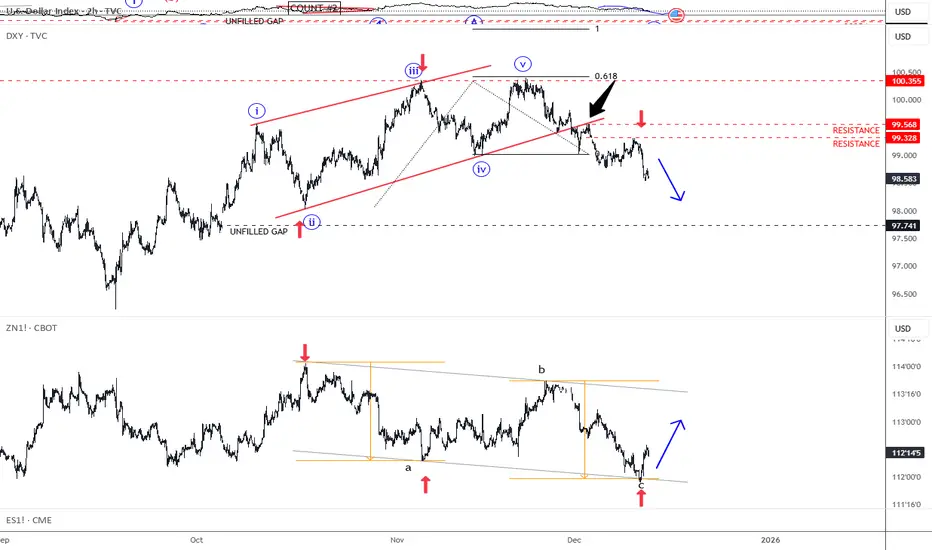
Fed Cuts, Treasuries Bounce, Dollar Slips FurtherGood morning traders! The Fed cut interest rates by 0.25% yesterday, marking the third straight cut. A few members dissented, showing the committee isn’t fully aligned. They proceeded with the cut as the job market continues to cool, even though inflation is still sticking around. The Fed also hinted this could be the last cut for a while and announced plans to start buying short-term Treasuries to keep liquidity stable. The US dollar remains under bearish pressure, while stocks hold steady, keeping the risk-on sentiment intact. This momentum could carry into year-end, we should just be aware of potential short-term pullbacks. USDollar Index - DXY remains nicely bearish, supported by 10Y US Treasury chart, as anticipated. If we consider that 10Y US Notes chart is now turning back to bullish mode, then DXY could easily see more weakness at least towards the open/unfilled GAP at 97.74 area. Projecting Interest Rates Beyond the Current Fed RegimeCBOT: 10-Year T-Notes Futures ( CBOT:ZN1! )
Since hitting an all-time high (ATH) of 48,431 on November 12th, the Dow Jones Industrial Average lost 1,841 points, or -3.8%, to 46,590 on Monday.
Meanwhile, the Nasdaq Composite has lost over 1,300 points, or -5.5%, from its ATH of 24,020. The S&P 500 is down 250 points, or -3.6%, from 6,920. Both the Nasdaq and the S&P reached their ATH on October 29th.
Cryptocurrencies have been harder hit than stocks. Today, Bitcoin prices dropped below $90,000, a whopping 29% drawdown since the King of Crypto hit ATH of $126,080. An entire year of gains has been erased.
Two key market forces are driving the US stock market downtrend.
Firstly, Wall Street grew worried about the AI bubble bursting. Earlier this month, “Big Short” investor Michael Burry grabbed headlines after his Scion Investment’s 13F filing showed bearish bets on Nvidia (NVDA) and Palantir (PLTR). Last week, Softbank offloaded all 32.1 million shares of NVDA it held. This is followed by Peter Thiel’s hedge fund, which sold off all 537,742 shares of NVDA on Monday.
On my October 27th commentary, I discussed that heavy exposure in High Tech stocks (64%) made Nasdaq very venerable. The Dow could weather the downturn better with a lower weight (21%). The recent market trend resonates with my theory.
Secondly, the Federal Reserve has turned hawkish on monetary policy. The Fed made the last rate cut on October 29th, without the aid of updated economic data due to US government shutdown. Fed officials have warned that further rate cuts are not a sure thing if new data does not support policy easing.
On October 27th, the odds for a December cut were 98.5%, according to data from the CME FedWatch tool. Today, it went down sharply to just 57%. Not cutting has the same effect as raising expected interest rates, which tends to drive down stock valuation.
www.cmegroup.com
The Future is Less Uncertain than the Present
In my view, the market obsession with what the Fed Chair says day by day is overblown. Anybody remember a quote from Alan Greenspan? While modeling short-term decisions into long-term trends, we risk overlooking the impact from changing of guards at the Fed.
The current Fed Chair’s term will end in May 2026. Between now and then, there are four FOMC rate-setting meetings: December 9-10, 2025, January 27-28, March 17-18 and April 28-29 in 2026. What could possibly happen in four meetings:
• If the Fed is hawkish and refuses to cut rates, the policy Fed Funds rate could stay at the current 375-400 bp range.
• If the Fed turns dovish and cut 25bp every time, Fed Funds could be at 275-300 bp.
In recent meetings, the Fed no longer had consensus in its policy votes. Each decision is like a toss-up. If we only focus on the short term, trading results could be very volatile.
The next Fed Chair will be nominated by President Trump and confirmed by the Senate. We know for a fact that the President favors aggressive rate cuts to support the economy. Only someone who is 100% in agreement with the President could get nominated.
Latest news indicates that five candidates have made it to the final list to be considered for a Fed Chair nomination. They are Michelle Bowman, Christopher Waller, Kevin Warsh, Kevin Hassett and Rick Rieder.
If the Senate confirmation gets delayed, the President could pick a current Fed governor as Acting Chair. Whoever that may be, he or she will have to align with the President in terms of the direction of monetary policy. Gone with the independent central bank.
Even though we have no idea what happens next month, we could still form a good estimate of what the Fed will do in the next 2-1/2 years, starting in June 2026.
In my opinion, the expected policy rate will eventually go down to 1.0-1.5%, or even lower. This is not what the Fed currently says. Instead, I am forming an opinion based on a new Fed regime with a new Chair and multiple Fed governors supporting rate cuts.
With that in mind, we can now discuss trade strategies going beyond the next Fed meeting. We don’t have to wait a long time for everything to move in places. Once a new Fed Chair candidate is announced, the market will start pricing a different interest rate trajectory. Latest news suggests that the President may be meeting with three candidates after the Thanksgiving holiday.
Trading with 10 Year T-Notes Futures
As I mentioned earlier, US stocks have the risk of AI bubble bursting. We could wait a while to see how things play out. My trade idea today is a pure play on interest rates.
We know that Treasury prices are negatively correlated with interest rates. When rates go down, prices will likely go up. Our major chart illustrates this relationship.
CBOT 10-Year Treasury Notes Futures have a face value of $100,000 at maturity. The March 2026 contract (ZNH6) is currently quoting 112'240, equivalent to $112.75. Buying or selling one contract requires an initial margin of $1,875.
The 10Y futures are one of the most liquid futures contracts in the world. According to CME Group data, trade volume on November 17th was 1,779,688 contracts. Open Interest (OI) is 5,748,386 contracts at market close. OI is notional term is $574.8 billion.
In the next three FOMC meeting cycles, the contract prices could go either way depending on how the Fed votes. However, as soon as the President nominate his Fed Chair candidate, Treasury prices would get a big boost as the market will price in the new and lowered expected interest rates.
Hypothetically, if ZNH6 moves up 1% to $113.8775, the $1.1275 price gain would translate into $1,127.5 for a long futures position, given each dollar gain in price quotation equals $1,000 per contract. Using the initial margin of $1,875 as a cost base, the trade would produce a theoretical return of 60.1% (=1127.5/1875).
The long futures position will lose money if the Fed puts rate cuts on hold, and the new Fed Chair candidate is not announced in the next three months.
Happy Trading.
Disclaimers
*Trade ideas cited above are for illustration only, as an integral part of a case study to demonstrate the fundamental concepts in risk management under the market scenarios being discussed. They shall not be construed as investment recommendations or advice. Nor are they used to promote any specific products, or services.
CME Real-time Market Data help identify trading set-ups and express my market views. If you have futures in your trading portfolio, you can check out on CME Group data plans available that suit your trading needs www.tradingview.com
Long 
 Short

Long 
Economic Red Alert: China Dumps $8.2T in US BondsThe Great Unwinding: How a World of Excess Supply and Fading Demand Is Fueling a Crisis of Confidence
The global financial system, long accustomed to the steady hum of predictable economic cycles, is now being jolted by a dissonant chord. It is the sound of a fundamental paradigm shift, a tectonic realignment where the twin forces of overwhelming supply and evaporating demand are grinding against each other, creating fissures in the very bedrock of the world economy. This is not a distant, theoretical threat; its tremors are being felt in real-time. The most recent and dramatic of these tremors was a stark, headline-grabbing move from Beijing: China’s abrupt sale of $8.2 trillion in U.S. Treasuries, a move that coincided with and exacerbated a precipitous decline in the U.S. dollar. While the sale itself is a single data point, it is far more than a routine portfolio adjustment. It is a symptom of a deeper malaise and a powerful accelerant for a crisis of confidence that is spreading through the arteries of global finance. The era of easy growth and limitless demand is over. We have entered the Great Unwinding, a period where the cracks from years of excess are beginning to show, and the consequences will be felt broadly, from sovereign balance sheets to household budgets.
To understand the gravity of the current moment, one must first diagnose the core imbalance plaguing the global economy. It is a classic, almost textbook, economic problem scaled to an unprecedented global level: a glut of supply crashing against a wall of weakening demand. This imbalance was born from the chaotic response to the COVID-19 pandemic. In 2020 and 2021, as governments unleashed trillions in fiscal stimulus and central banks flooded the system with liquidity, a massive demand signal was sent through the global supply chain. Consumers, flush with cash and stuck at home, ordered goods at a voracious pace. Companies, believing this trend was the new normal, ramped up production, chartered their own ships, and built up massive inventories of everything from semiconductors and furniture to automobiles and apparel. The prevailing logic was that demand was insatiable and the primary challenge was overcoming supply-side bottlenecks.
Now, the bullwhip has cracked back with a vengeance. The stimulus has faded, and the landscape has been radically altered by the most aggressive coordinated monetary tightening in modern history. Central banks, led by the U.S. Federal Reserve, hiked interest rates at a blistering pace to combat the very inflation their earlier policies had helped fuel. The effect has been a chilling of economic activity across the board. Demand, once thought to be boundless, has fallen off a cliff. Households, their pandemic-era savings depleted and their purchasing power eroded by stubborn inflation, are now contending with cripplingly high interest rates. The cost of financing a home, a car, or even a credit card balance has soared, forcing a dramatic retrenchment in consumer spending. Businesses, facing the same high borrowing costs, are shelving expansion plans, cutting capital expenditures, and desperately trying to offload the mountains of inventory they accumulated just a year or two prior.
This has created a world of profound excess. Warehouses are overflowing. Shipping rates have collapsed from their pandemic peaks. Companies that were once scrambling for microchips are now announcing production cuts due to a glut. This oversupply is deflationary in nature, putting immense downward pressure on corporate profit margins. Businesses are caught in a vise: their costs remain elevated due to sticky wage inflation and higher energy prices, while their ability to pass on these costs is vanishing as consumer demand evaporates. This is the breeding ground for the "cracks" that are now becoming visible. The first casualties are the so-called "zombie companies"—firms that were only able to survive in a zero-interest-rate environment by constantly refinancing their debt. With borrowing costs now prohibitively high, they are facing a wave of defaults. The commercial real estate sector, already hollowed out by the work-from-home trend, is buckling under the weight of maturing loans that cannot be refinanced on favorable terms. Regional banks, laden with low-yielding, long-duration bonds and exposed to failing commercial property loans, are showing signs of systemic stress. The cracks are not isolated; they are interconnected, threatening a chain reaction of deleveraging and asset fire sales.
It is against this precarious backdrop of a weakening U.S. economy and a global supply glut that China’s sale of U.S. Treasuries must be interpreted. The move is not occurring in a vacuum. It is a calculated action within a deeply fragile geopolitical and economic context, and it carries multiple, overlapping meanings. On one level, it is a clear continuation of China’s long-term strategic objective of de-dollarization. For years, Beijing has been wary of its deep financial entanglement with its primary geopolitical rival. The freezing of Russia’s foreign currency reserves following the invasion of Ukraine served as a stark wake-up call, demonstrating how the dollar-centric financial system could be weaponized. By gradually reducing its holdings of U.S. debt, China seeks to insulate itself from potential U.S. sanctions and chip away at the dollar's status as the world's undisputed reserve currency. This $8.2 trillion sale is another deliberate step on that long march.
However, there are more immediate and tactical motivations at play. China is grappling with its own severe economic crisis. The nation is battling deflation, a collapsing property sector, and record-high youth unemployment. In this environment, its primary objective is to stabilize its own currency, the Yuan, which has been under intense downward pressure. A key strategy for achieving this is to intervene in currency markets. Paradoxically, this intervention often requires selling U.S. Treasuries. The process involves the People's Bank of China selling its Treasury holdings to obtain U.S. dollars, and then selling those dollars in the open market to buy up Yuan, thereby supporting its value. So, while the headline reads as an attack on U.S. assets, it is also a sign of China's own domestic weakness—a desperate measure to defend its own financial stability by using its vast reserves.
Regardless of the primary motivation—be it strategic de-dollarization or tactical currency management—the timing and impact of the sale are profoundly significant. It comes at a moment of peak vulnerability for the U.S. dollar and the Treasury market. The dollar has been extending massive losses not because of China’s actions alone, but because the underlying fundamentals of the U.S. economy are deteriorating. Markets are increasingly pricing in a pivot from the Federal Reserve, anticipating that the "cracks" in the economy will force it to end its tightening cycle and begin cutting interest rates sooner rather than later. This expectation of lower future yields makes the dollar less attractive to foreign investors, causing it to weaken against other major currencies.
China’s sale acts as a powerful accelerant to this trend. The U.S. Treasury market is supposed to be the deepest, most liquid, and safest financial market in the world. It is the bedrock upon which the entire global financial system is built. When a major creditor like China becomes a conspicuous seller, it sends a powerful signal. It introduces a new source of supply into a market that is already struggling to absorb the massive amount of debt being issued by the U.S. government to fund its budget deficits. This creates a dangerous feedback loop. More supply of Treasuries puts downward pressure on their prices, which in turn pushes up their yields. Higher Treasury yields translate directly into higher borrowing costs for the entire U.S. economy, further squeezing households and businesses, deepening the economic slowdown, and increasing the pressure on the Fed to cut rates, which in turn further weakens the dollar. China’s action, therefore, pours fuel on the fire, eroding confidence in the very asset that is meant to be the ultimate safe haven.
The contagion from this dynamic—a weakening U.S. economy, a falling dollar, and an unstable Treasury market—will not be contained within American borders. The cracks will spread globally, creating a volatile and unpredictable environment for all nations. For emerging markets, the situation is a double-edged sword. A weaker dollar is traditionally a tailwind for these economies, as it reduces the burden of their dollar-denominated debts. However, this benefit is likely to be completely overshadowed by the collapse in global demand. As the U.S. and other major economies slow down, their demand for raw materials, manufactured goods, and services from the developing world will plummet, devastating the export-driven models of many emerging nations. They will find themselves caught between lower debt servicing costs and a collapse in their primary source of income.
For other developed economies like Europe and Japan, the consequences are more straightforwardly negative. A rapidly falling dollar means a rapidly rising Euro and Yen. This makes their exports more expensive and less competitive on the global market, acting as a significant drag on their own already fragile economies. The European Central Bank and the Bank of Japan will find themselves in an impossible position. If they cut interest rates to weaken their currencies and support their exporters, they risk re-igniting inflation. If they hold rates firm, they risk allowing their currencies to appreciate to levels that could push their economies into a deep recession. This currency turmoil, originating from the weakness in the U.S., effectively exports America’s economic problems to the rest of the world.
Furthermore, the instability in the U.S. Treasury market has profound implications for every financial institution on the planet. Central banks, commercial banks, pension funds, and insurance companies all hold U.S. Treasuries as their primary reserve asset. The assumption has always been that this asset is risk-free and its value is stable. The recent volatility and the high-profile selling by a major state actor challenge this core assumption. This forces a global repricing of risk. If the "risk-free" asset is no longer truly risk-free, then the premium required to hold any other, riskier asset—from corporate bonds to equities—must increase. This leads to a tightening of financial conditions globally, starving the world economy of credit and investment at the precise moment it is most needed.
In conclusion, the abrupt sale of $8.2 trillion in U.S. Treasuries by China is far more than a fleeting headline. It is a critical data point that illuminates the precarious state of the global economy. It is a manifestation of the Great Unwinding, a painful transition away from an era of limitless, debt-fueled demand and toward a new reality defined by excess supply, faltering consumption, and escalating geopolitical friction. The underlying cause of this instability is the deep imbalance created by years of policy missteps, which have left the world with a glut of goods and a mountain of debt. The weakening U.S. economy and the resulting slide in the dollar are the natural consequences of this imbalance. China’s actions serve as both a symptom of this weakness and a catalyst for a deeper crisis of confidence in the U.S.-centric financial system. The cracks are no longer hypothetical; they are appearing in the banking sector, in corporate credit markets, and now in the bedrock of the system itself—the U.S. Treasury market. The tremors from this shift will be felt broadly, ushering in a period of heightened volatility, economic pain, and a fundamental reordering of the global financial landscape.
 Short

Short